Article
Offset account setups that actually work for sole traders
The cleanest offset setup for a sole trader working from home is simple: separate business trading, tax/GST and personal/offset accounts, then pay yourself a regular “wage” into the offset. This keeps lenders calm, the ATO ring‑fenced and your home loan interest down.
Key Takeaway
The best offset account setup for sole traders working from home is a three‑account structure: one business trading account, one separate tax/GST holding account, and a personal everyday account linked to a home loan offset, with regular transfers treated as a “wage”. This aligns with lender preferences that favour clear, separated cashflows and improves approval odds within 3–6 months. The actionable step is to open and relabel accounts this week, then run all ATO money through a ring‑fenced holding account, not your offset.
For sole traders working from home, the best offset setup is simple: keep business and ATO money away from your home loan, and pay yourself a steady “wage” into a clean offset-linked personal account. That usually means three main accounts: business trading, tax/GST holding, and a personal everyday account feeding your offset.
This structure keeps lenders happy, protects your family home from business risk, and still lets you smash down interest.
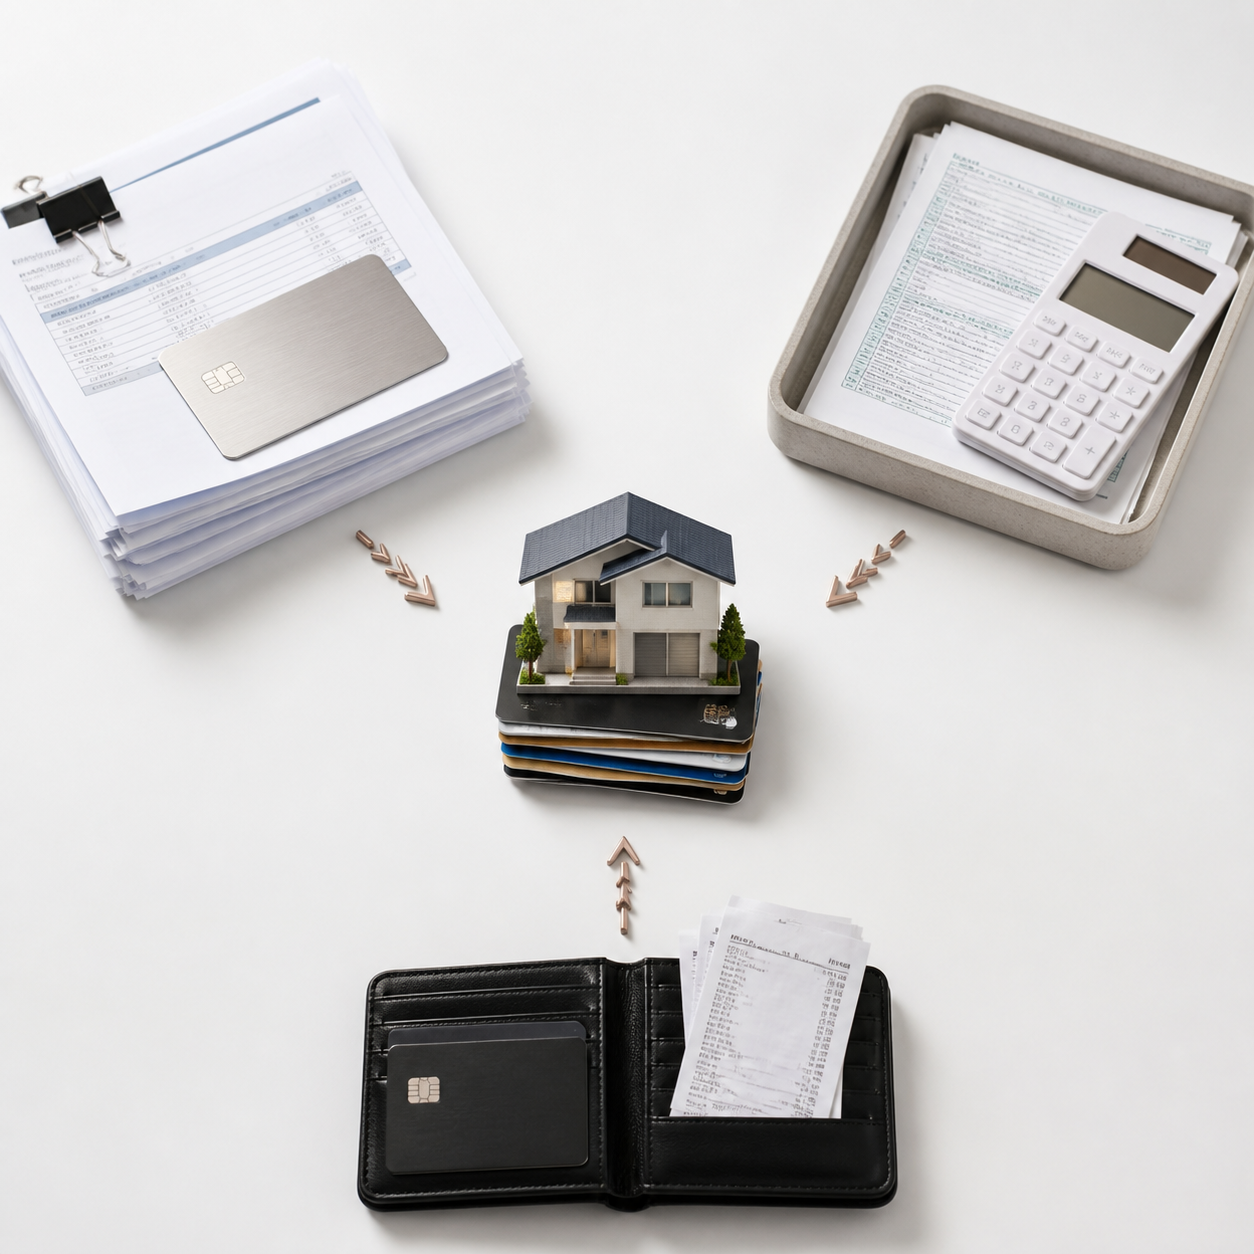
The core setup: three accounts plus your offset
For most home‑based sole traders, a three‑account structure works best:
- Business trading account – all client income in, business expenses out.
- Tax/GST/PAYG holding account – ring‑fence ATO money as it comes in.
- Personal everyday account + linked offset – your “salary” lands here and flows into the offset.
This is the same discipline lenders love to see in your bank statements over 3–6 months. It’s also consistent with the three‑account model we use in /insights/red-flags-mixed-business-personal-accounts-spook-lenders-fix.
How the money should flow
- Step 1 – Client pays invoice into your business trading account.
- Step 2 – Move the tax/GST portion (often 25–35% of income, depending on your rate and GST) into your tax holding account.
- Step 3 – Transfer a fixed “wage” (say $4,500 a month) from business to your personal everyday account.
- Step 4 – Sweep surplus from your personal account into the offset each week or month.
ATO money never touches your offset. Business expenses never come from your offset. That’s the key discipline.
Why not just run everything through the offset?
Mixing business and personal in your offset looks clever short‑term but creates three big problems:
- Lenders see a risky business. Regular transfers from offset/redraw to cover BAS, wages or stock are a red flag that the business can’t self‑fund core costs.
- ATO money gets spent. When GST and PAYG sit in the same offset you buy groceries from, the next BAS can hurt badly.
- Tax tracing gets messy. It becomes harder for you and your accountant to prove what’s deductible, especially if you ever convert the home to an investment later.
We’ve seen many self‑employed clients in this position when reviewing their banking for a home loan. Cleaning it up is often step one before we apply, as explained in /insights/structuring-business-personal-accounts-lenders-see-real-income.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do I need my business accounts with the same bank as my home loan?▾
Can I temporarily park my GST in the offset and move it out before BAS is due?▾
What if my income is too lumpy for a fixed wage transfer?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.