Article
Buying Into a Boutique Block in Paddington or Woollahra: Finance & Strata Playbook
A decision‑grade guide to financing and assessing luxury boutique strata blocks in Paddington and Woollahra, with clear lending, valuation, strata and cashflow checks you can work through this week.
Key Takeaway
This article explains how to safely finance a luxury boutique apartment in Paddington or Woollahra, where lenders often cap LVRs at around 70–80% and strata levies can exceed $10,000 per year. It covers serviceability under APRA’s 3% buffer, valuation risk, small‑scheme strata issues, and the need for 6–12 months of total holding costs in cash or offset. Readers get a one-week checklist to test a target property and decide if it fits their risk budget.
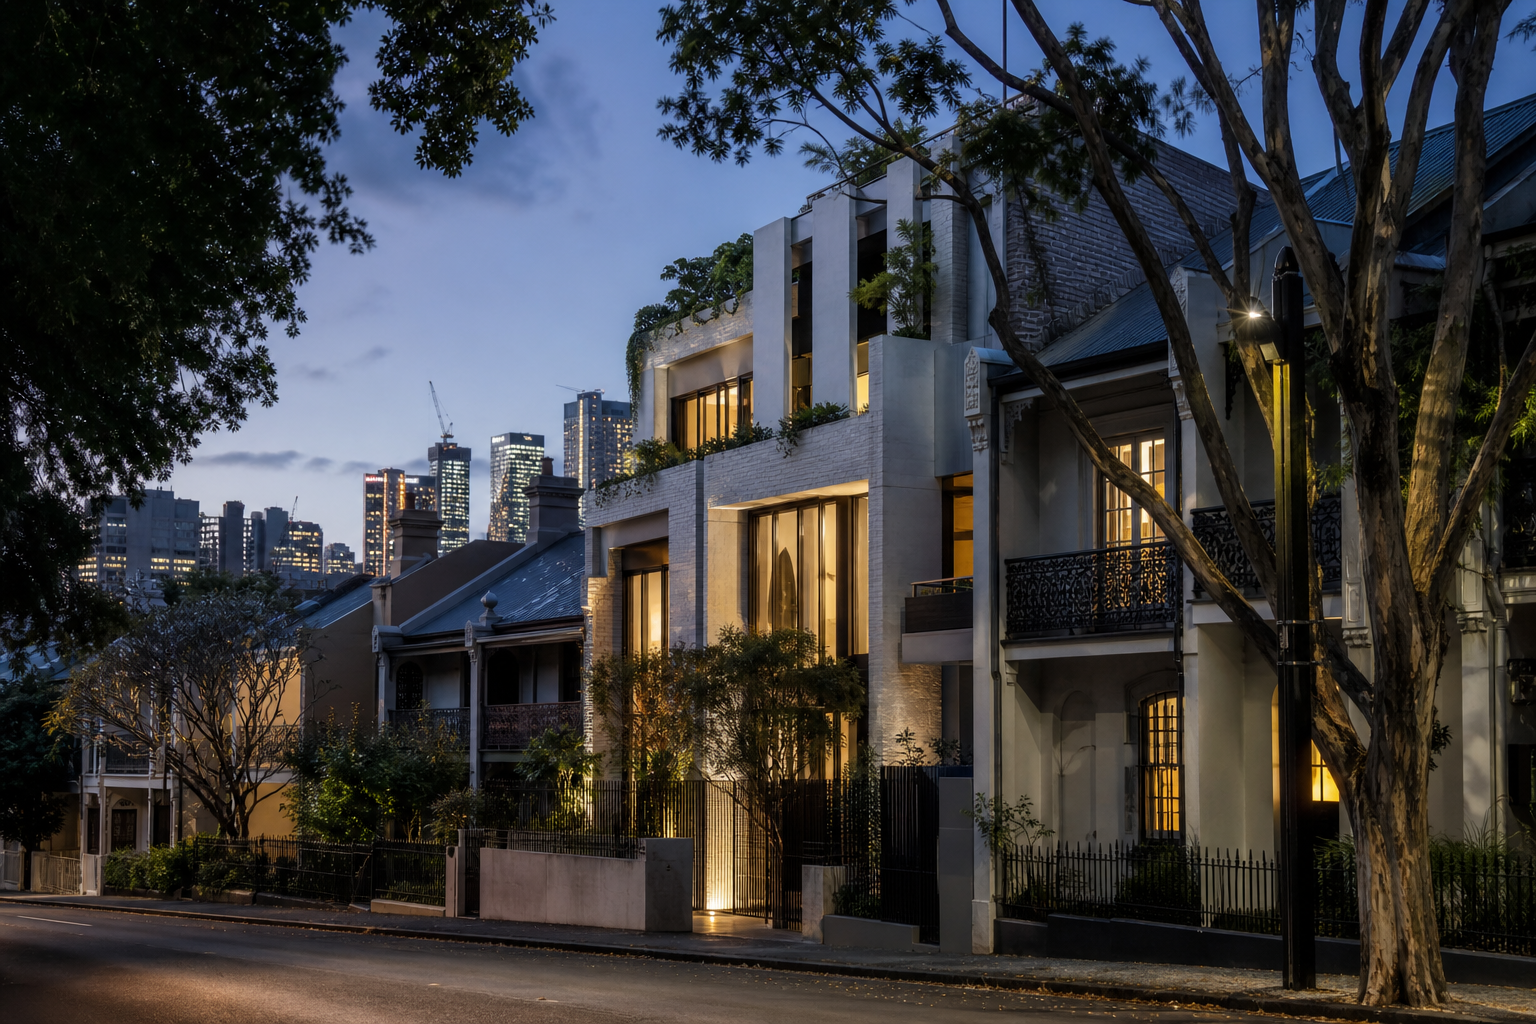
Buying into a luxury boutique block in Paddington or Woollahra is not the same as buying a generic apartment in a 200‑lot complex.
Within a 5–10 minute walk, you can see $2m warehouse conversions, $4m+ three‑bed walk‑ups, and $8m+ penthouse‑style terraces in small schemes of 3–12 lots. The properties are beautiful, but the lending and strata settings are less forgiving.
This guide is written so you can look at a specific property this week and decide, with numbers, whether it’s a safe move.
1. What makes a “luxury boutique block” in Paddington and Woollahra?
In this context, a luxury boutique block is typically:
- Located in Paddington, Woollahra, Queen Street village, Five Ways, or immediate surrounds.
- A small strata scheme (often 2–12 lots, sometimes under 20).
- High price per square metre; total prices commonly $2m–$6m+.
- Higher‑end finishes (stone, timber, joinery), often bespoke rather than standard developer stock.
- Often a conversion (warehouse, terrace subdivision, mixed‑use) rather than a big‑builder project.
From a lender’s perspective, these have three key features:
- High value, concentrated risk – a few high‑value lots instead of hundreds of cheaper ones.
- Illiquid resale market – limited comparable sales; valuations can be conservative.
- Idiosyncratic strata – bespoke bylaws, uneven levy contributions, and higher per‑lot costs.
How this changes your loan conversation
When you mix a high loan size with an unusual asset, banks and valuers tend to:
- Cap LVRs (loan‑to‑value ratios) more tightly.
- Interrogate your income and buffers more deeply.
- Scrutinise the strata report instead of treating it as a tick‑box.
If you’ve read our piece on financing high‑end apartments and penthouses in Bondi, Tamarama or Coogee, the theme is similar: the nicer and rarer the property, the more conservative the credit lens.
2. How lenders view boutique blocks in the East
2.1 Standard apartments vs boutique high‑end stock
Most major lenders classify apartments along a few axes:
- Location (metro vs regional; high‑density postcodes vs standard).
- Floor area (e.g. studios under 40–50 m² can be restricted).
- Security type (residential strata vs company title vs leasehold vs mixed‑use).
- Concentration risk (small or unusual complexes).
Luxury Paddington and Woollahra stock can trigger multiple flags at once:
- Above‑average price per m².
- Small number of lots.
- Sometimes mixed‑use zoning or commercial on ground.
- Heritage constraints that affect future works.
| Factor | Generic 100‑lot apartment in Randwick | 6‑lot luxury conversion in Paddington |
|---|---|---|
| Typical price range | $900k–$1.5m | $2.5m–$5m+ |
| LVR appetite (indicative) | Up to 90–95% with LMI | Often 70–80%, sometimes less |
| Valuation certainty | Many comparable sales | Few direct comparables |
| Strata risk | Costs spread across many owners | Each owner carries bigger share |
| Credit scrutiny | Standard | Heightened |
All figures are indicative only – actual policies vary by lender and over time.
2.2 LVRs, cash contributions and buffers
In prestige boutique blocks, realistic settings today often look like:
- Owner‑occupier: plan for 20–30% deposit + costs (stamp duty, legal, inspections). Some lenders may allow higher LVRs if the building is simple, but you don’t want your plan to rely on the most generous policy in the market.
- Investor: expect 20–30% deposit as a base assumption; more if title or use is quirky.
For high‑value Eastern Suburbs homes more broadly, we regularly recommend keeping 6–12 months of total loan repayments plus essential living costs in cash or true offset after settlement, especially for self‑employed buyers (see our Dover Heights case in /insights/self-employed-professional-buys-dover-heights-complex-income). With boutique blocks and high strata levies, add annual levies and insurances into that holding‑cost calculation.
A quick rule of thumb:
After paying your deposit and costs, aim to still hold 6–12 months of full holding costs (loan + strata + council + insurance + basic utilities) in cash or offset.
This echoes broader guidance from our Eastern Suburbs upgrade and downsizer work: buffers aren’t a luxury at this end of the market; they’re a safety rail.
3. Valuation and price risk in small luxury schemes
3.1 Why valuations can lag the contract price
Valuers need comparable sales to justify a figure. In many Paddington and Woollahra blocks there might only be:
- One sale in the last 3–5 years.
- No directly comparable apartments (different renovations, outlooks, parking, outdoor space).
- A wide range of sales on the street, from basic terraces to trophy homes.
That can lead to:
- Bank valuation at or near purchase price if the valuer is comfortable.
- Valuation shortfalls if they adopt a conservative stance.
Illustrative example:
- You agree to buy a 3‑bed, 2‑bath, 2‑car apartment in a six‑lot Woollahra block for $4.2m.
- You’re targeting an 80% LVR (loan $3.36m) with $840k deposit plus costs.
- Valuation comes back at $4.0m, citing a lack of direct comparables.
- The bank will now lend 80% of $4.0m = $3.2m, leaving a $160k gap you must fund in cash or reduce LVR.
On a tight timetable, that surprise can derail settlement.
3.2 How to reduce valuation shock
You can’t fully control the val, but you can reduce surprises:
- Get pre‑approval realistically sized – don’t rely on best‑case market value assumptions.
- Ask your broker for a desktop or upfront valuation for similar stock if possible (no addresses, but sanity‑check ranges).
- Stress‑test your deposit to absorb a 5–10% valuation shortfall. If that breaks your buffer rules, scale back the target price.
- Avoid over‑weighting agent “underbidder” stories as evidence of value.
If you’re buying while holding another property, also factor in bridging risk. Our guide on bridging finance for Eastern Suburbs upgraders walks through how to stack two loans safely under a 3% rate buffer and realistic sale assumptions.
4. Boutique strata: what can go right, and very wrong
4.1 Why small, high‑end schemes feel attractive
Fatigue with big strata is real. Buyers like boutique blocks because:
- There are fewer neighbours and often a stronger sense of community.
- Finishes are usually higher quality.
- There’s less risk of large, chaotic strata meetings.
- Often better design, light and privacy.
All of that can be true – and still sit alongside concentrated cost risk.
4.2 How levies behave in small luxury blocks
In a ten‑lot block, a $200k capital works project is $20k per lot if contributions are equal.
In a four‑lot block, the same project is $50k per lot.
And in luxury buildings, the baseline can be higher:
- More lift or mechanical systems.
- High‑end common finishes that are expensive to maintain.
- Smaller land footprint, so less ability to stage or defer works.
Indicative annual strata comparison:
| Block type | Lots | Common features | Typical annual levies (per lot) |
|---|---|---|---|
| 80‑lot mid‑market block in Randwick | 80 | Lift, basic landscaping | $5,000–$8,000 |
| 12‑lot boutique block in Paddington | 12 | Lift, quality finishes | $7,000–$12,000 |
| 4‑lot luxury conversion in Woollahra | 4 | No lift, but high‑spec | $4,000–$9,000 |
Figures are broad ranges only; we routinely see outliers above $15,000 where lifts, pools or heritage façades are involved.
4.3 Strata balance sheets in small schemes
When you read the strata report, focus on:
- Admin fund balance – should comfortably cover ordinary running costs.
- Capital works fund balance and plan – is there a funded, realistic program of major works?
- Special levies – frequency, purposes, who paid/was exempt.
- Arrears – if one owner in a 6‑lot scheme hasn’t paid levies for 18 months, that’s a tangible risk.
The test: could this building absorb a sudden $250k remediation without crippling one or two owners? If not, you need to price that risk into your offer and your buffer.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 8 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Are banks more conservative with boutique blocks in Paddington and Woollahra?▾
How much deposit do I need for a luxury boutique apartment in Woollahra?▾
How do high strata levies affect my borrowing power?▾
What should I look for in the strata report of a small luxury block?▾
Is bridging finance safe for upgrading into a boutique block?▾
How can self-employed buyers improve their chances of approval?▾
Can I use a company or trust to buy a boutique apartment?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.