Article
Structuring co‑ownership and tenants in common under new tax rules
A decision‑grade guide to co‑ownership, tenants in common and shared loans under the new CGT and negative gearing rules, with clear examples, tables and one‑week actions.
Key Takeaway
This article explains how co‑ownership, tenants in common and shared loans work under Australia’s post‑2026 changes to negative gearing and capital gains tax, and why ownership percentages must match economic contribution to avoid ATO scrutiny. It outlines how rental income, quarantined losses and CGT are split between co‑owners, with a worked example on a $900,000 investment. The piece ends by recommending clean loan splits and ATO‑ready records as the key actionable step this week.
Co‑ownership still works under the new negative gearing and CGT rules, but you must line up three things: 1) the legal ownership (joint tenants or tenants in common), 2) who actually pays and benefits, and 3) clean, split loans that match each property and tax regime. Get those aligned and you can still share deductions, manage risk and keep the ATO comfortable.
In practice, that means reviewing your co‑ownership structure now – especially if you’re planning a purchase or refinance after the 2026–27 Budget changes kick in.
1. Co‑ownership basics under updated tax settings
Joint tenants vs tenants in common – what really changes?
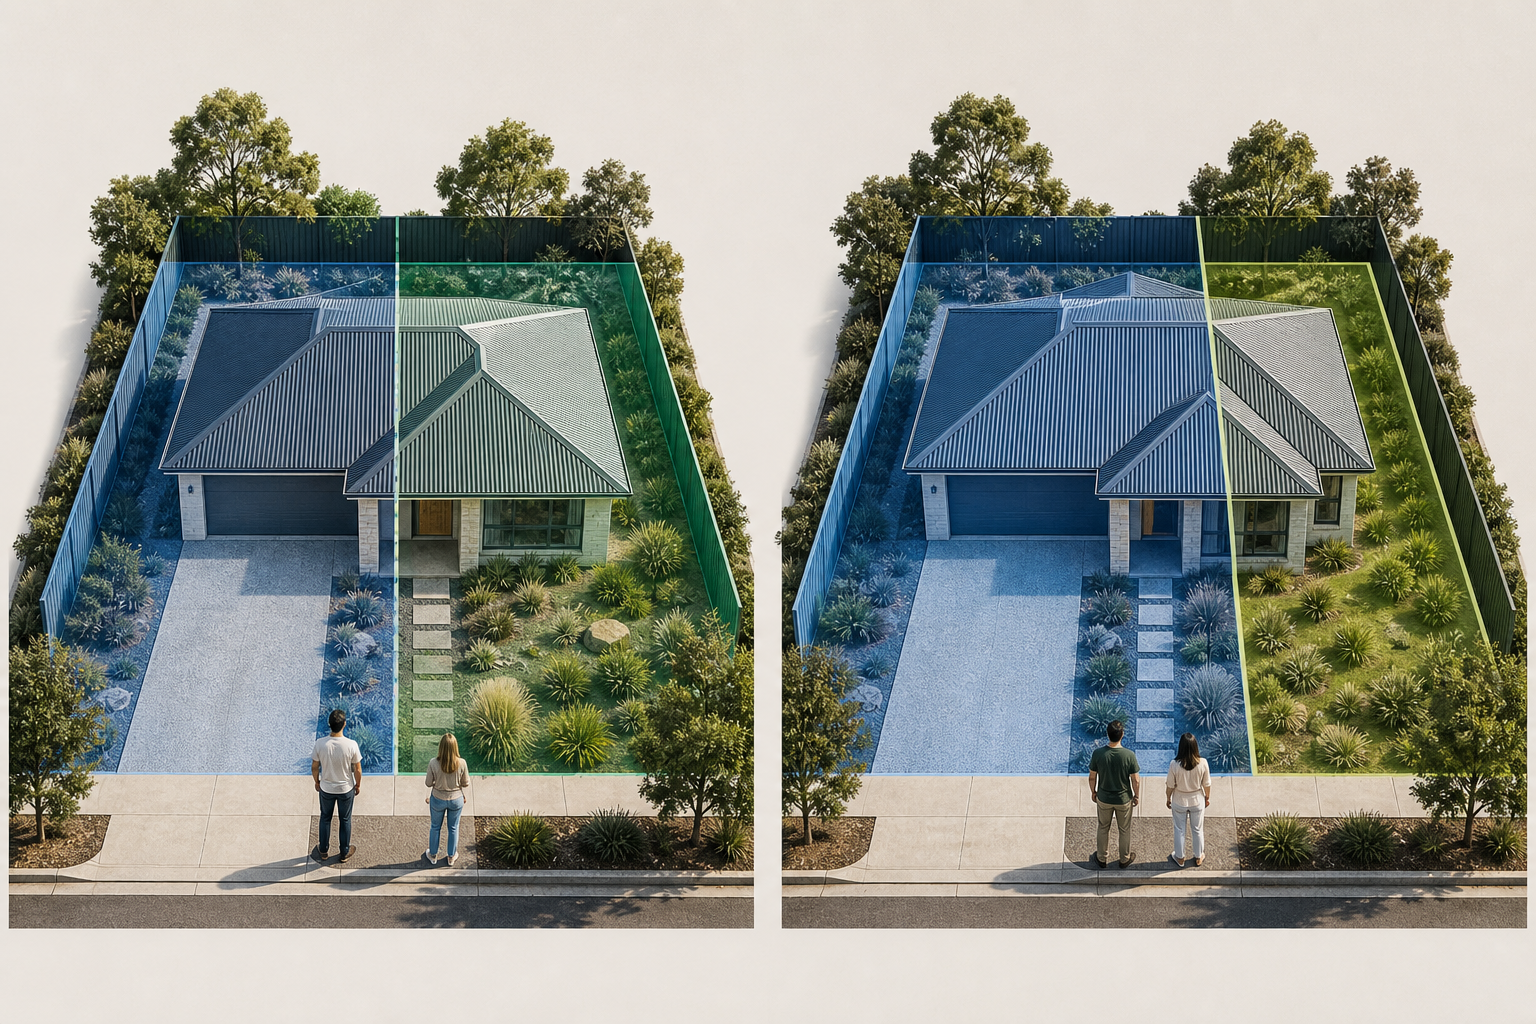
Joint tenants means each owner has an equal interest and the property passes automatically to the survivor.
Tenants in common means you can hold unequal shares (for example 70/30) and each owner’s share passes via their will.
Tax-wise:
- Rental income and deductions follow legal ownership percentages.
- Capital gains tax (CGT) is calculated separately for each owner’s share.
- New rules from 12 May 2026/1 July 2027 will split properties into grandfathered and new‑regime categories, but the split still follows ownership shares.
If one person pays most of the costs but only owns 10%, they generally only claim 10% of deductions, including any quarantined negative gearing losses.
Why the 2026–27 reforms matter for co‑owners
From 1 July 2027 (subject to final legislation):
- Negative gearing on many established residential properties will be quarantined so excess rental losses are only offset against rental income and capital gains, not salary.
- The 50% CGT discount will be largely replaced with indexation plus a higher minimum tax on gains.
- Records must be able to show which property, which loan and which taxpayer sit under which rules (see /insights/grandfathered-vs-new-investments-record-keeping-negative-gearing).
For co‑owners, that means your ownership split and loan structure will determine who carries quarantined losses and how CGT hits when you eventually sell.
2. Tenants in common and negative gearing: how to share fairly
Splits that match cash, risk and tax
Tenants in common is usually the better fit when:
- One party contributes more deposit or takes on more risk.
- Parents are helping children and want a defined equity slice.
- Partners have different tax brackets or pre‑existing properties.
But the ATO increasingly expects your ownership split to reflect real economics – who put in what, and who gets what on sale – especially once negative gearing is tighter.
Example: 70/30 tenants in common with shared loan
- Purchase price: $900,000 investment unit (established).
- Ownership: Alex 70%, Priya 30% (tenants in common).
- Joint loan: $720,000, P&I 6.5% over 30 years.
- Annual interest (approx first‑year): $46,800.
- Rent: $750/week = $39,000 p.a.
- Other expenses (rates, strata, insurance, agent, repairs etc.): $9,000.
Total annual rental result:
- Income: $39,000
- Expenses: $55,800 ($46,800 interest + $9,000 other)
- Net loss: $16,800
Split for tax (following legal shares):
- Alex (70%): loss $11,760
- Priya (30%): loss $5,040
Under the new rules for a post‑2026 established property:
- That loss is still recorded for each owner but generally quarantined to their future rental income and capital gains.
- If Alex already has several positively geared properties, the loss may be absorbed quickly.
- If Priya has no other rentals, her quarantined losses may build up for years.
Getting the ownership split wrong means one person carries unusable tax losses while the other shoulders more risk.
Comparison: 50/50 vs 70/30 tenants in common
| Scenario | Ownership split | Who contributes deposit? | Annual quarantined loss per owner* | CGT exposure per owner | Estate planning flexibility |
|---|---|---|---|---|---|
| A | 50/50 | Equal | $8,400 each | 50% each | Simple, but may not reflect real cash/risk |
| B | 70/30 | One pays 70% deposit | $11,760 / $5,040 | 70% / 30% | Better alignment with economics |
| C | 90/10 | Parent fronts 90% | $15,120 / $1,680 | 90% / 10% | Useful for parents helping kids |
*Using the $16,800 loss from the example above.
This is why one of your first steps should be a scenario model across different ownership splits, including how quarantined losses and CGT land for each party. See broader strategy framing in /insights/how-to-rethink-investment-property-selection-when-tax-rules-tighten.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How is tax handled for tenants in common co‑ownership?▾
Do we both get negative gearing if only one person pays the loan?▾
Is tenants in common better than joint tenants for investors?▾
Can parents co‑own a property their child lives in and still claim deductions?▾
Can we change our ownership split later to improve tax outcomes?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.