Article
Set Up Company and Trust Cashflow So Your Home Loan Stays Clean
How to structure company and trust cashflow so lenders see clean, stable income and your home loan stays insulated from business risk.
Key Takeaway
Australian business owners can keep their home loans ‘clean’ by separating company/trust cashflow from personal spending using dedicated trading, tax, distribution and household accounts, while paying themselves a stable wage or documented distributions for at least 6–24 months before applying for credit. Lenders typically apply a 3% serviceability buffer and prefer simple, recurring taxable income with no reliance on redraw or offsets for business working capital. Implementing a four-to-six account structure and avoiding mixed-purpose transactions materially improves borrowing power and protects the family home.
If you run a company or trust and own (or want) a home, your bank isn’t just looking at your tax returns. They’re tracing how money moves between your entities, your personal accounts and your mortgage. Clean structures make you look safer and more profitable. Messy ones can slash borrowing power and put your home at risk.
In this guide we’ll map out simple, practical company and trust cashflow setups that keep your home loan ‘clean’ in lenders’ eyes, without killing flexibility for your business.
Quick answer: what a “clean” structure looks like to a lender
A clean structure is one where:
- Business and trust cashflows run through their own accounts, not your personal or home loan accounts.
- Money comes to you in clear, taxable forms — usually salary, directors’ fees or documented dividends/distributions.
- Your home loan offset or redraw is not used as recurring business working capital.
- Loans between you, your company and your trust are documented and not quietly growing in the background.
If you can show 6–24 months of this kind of behaviour, most lenders will assess you more like a stable PAYG borrower, often boosting borrowing capacity compared with messy drawings and mixed accounts.
Why structure matters more now for business owners
1. Lenders are nervous – and they’re looking closer
Roy Morgan’s 2026 research shows over 30% of Australian mortgage holders are ‘At Risk’ of stress, with a large chunk ‘Extremely At Risk’. Combine that with a 4.35% cash rate and the standard APRA 3% serviceability buffer, and banks are combing through self‑employed files harder than they did pre‑COVID.
For company directors and trust investors, that means:
- More focus on actual bank statements, not just what you tell your accountant.
- Closer scrutiny of large transfers between your entities and personal accounts.
- Questions when they see BAS, wages or stock funded from a home loan offset.
If your accounts are tangled, you start your application on the back foot.
2. Banks lend on what they can see, not what you “really make”
This is the core theme across a few of our other guides, like:
- Structuring Your Business Income So Banks Will Actually Lend You More
- Make Your Business Bank Accounts Work For Your Home Loan
You might know that your company or trust is strong. But if income looks lumpy, undocumented or mixed in with business spending, under credit policy it often gets heavily shaded or ignored.
3. Intertwined home and business debt increases risk
From a risk point of view, using home loan redraw or offset as ongoing business working capital concentrates business risk on the family home and complicates tax deductibility. We’ve seen this across multiple case studies in our hub — once you start treating a mortgage like an overdraft, it’s much harder to protect the home if trading conditions turn.
Good structure does two jobs:
- It paints a simple, strong income picture to your lender.
- It quarantines your home as much as possible from business volatility.
Core principles: “Clean” vs “messy” in a lender’s eyes
1. One pool for business, one pool for home
A simple way to think about it:
- Business/Trust world: trading, suppliers, wages, tax, GST, business loan repayments.
- Personal/Home world: groceries, school fees, holidays, home loan, investment property costs.
Money is allowed to cross the bridge between those worlds — but only in clear, explainable packets:
- Salary or directors’ fees (via payroll or recurring transfer)
- Dividends or trust distributions (with matching resolutions and tax records)
- Properly documented loans in or out
What banks dislike seeing:
- Rent from an investment held in a family trust going straight to your personal everyday account, then back to the trust for expenses.
- Business suppliers or staff paid out of your personal account or home loan offset.
- The company constantly drawing from home loan redraw to cover BAS or wages.
2. Pay yourself like a PAYG – then layer extras
For most company and trust owners, the cleanest approach is:
- Set a stable salary/wage that your business can genuinely afford.
- Pay it into a personal everyday account, like any PAYG earner.
- Use that account to pay your home loan and household expenses.
- Top up once or twice a year with clearly documented dividends or trust distributions, if appropriate.
This theme runs through:
- How to Pay Yourself for Strong Home Loan Approval as a Director
- How Company Profits Really Boost (Or Don’t Boost) Your Borrowing
Lenders are comfortable with higher tax if it buys them simplicity and stability.
3. Avoid the “frankencashflow” monster
A red‑flag pattern looks like this:
- Business income landing in your personal account
- Personal rent and dividends landing in the company or trust
- Tax payments made from a mishmash of all of the above
- Business loan repayments coming from your home loan offset
You might still be solvent and profitable. But to a credit assessor working off bank feeds and financials, it’s a nightmare. They’ll either:
- Take longer; or
- Shade your income; or
- Decline the deal on “unverifiable income” or “unacceptable conduct”.
Recommended account structures for companies and trusts
Below are practical setups you can implement this week. We’ll start simple and build up.
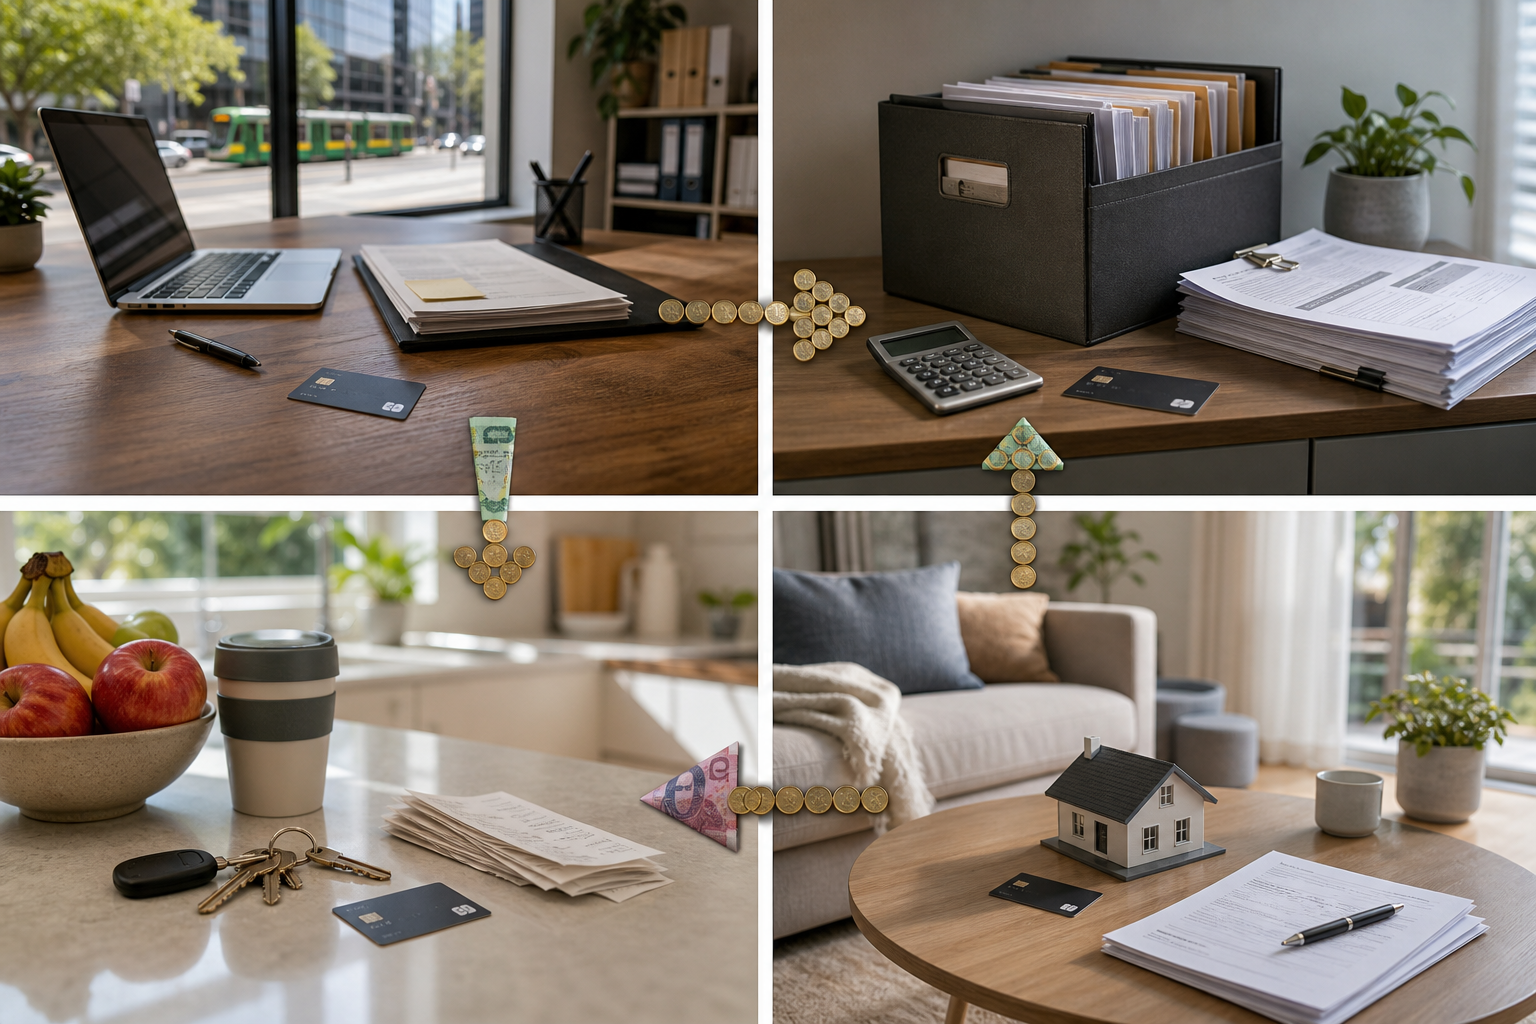
1. Baseline “four‑account” structure for a company
This is an evolution of the four‑account model we use for many small operators.
Company accounts
- Trading account – all business income in; all suppliers and operating costs out.
- Tax & GST account – regular transfers from trading to cover GST, PAYG(W) and income tax.
Personal accounts
- Household everyday account – your salary lands here; groceries, utilities, school fees go out.
- Home loan offset – holds household surplus and emergency buffer; attached to your owner‑occupier loan.
Optional extras if cashflow is bigger or more complex:
- Business savings/buffer account – for seasonal working capital.
- Capex account – for planned equipment/fit‑out spends.
But the key idea remains: no regular business expenses from the offset and no household bills from the trading account.
2. Trust + bucket company distribution structure
For a discretionary (family) trust with a bucket company:
Trust accounts
- Trust operating account – receives rent, dividends or trading income; pays trust‑level expenses and loans.
Bucket company accounts
- Company trading/holding account – receives distributions from the trust; pays company tax and any company‑level expenses.
- Company tax account – quarantines tax and franking credits.
Beneficiary accounts
- Household everyday account – receives salary/dividends from the company or distributions from the trust.
- Home loan offset – holds personal surplus.
Where people get in trouble is letting trust income bypass the trust and flow directly into personal accounts with no paperwork, or leaving large unpaid present entitlements (UPEs) sitting on the books. Lenders will often discount or ignore that income.
We cover how to make trust income usable for credit in detail here:
3. Comparison: clean vs messy structures
| Feature / Behaviour | Clean structure (lender‑friendly) | Messy structure (raises flags) |
|---|---|---|
| Business income flows | Into dedicated trading/operating account | Mixed between business, personal and home loan/offset |
| Personal spending | From household account only | From business account and sometimes directly from loan redraw |
| Home loan offset usage | Household surplus and emergency buffer only | Regular source of BAS, wages, stock or business loan repayments |
| Director drawings | Stable salary, plus occasional documented dividends | Irregular transfers labelled “drawings”, “loan”, “personal” |
| Trust distributions | Documented resolutions, clear cash transfers to beneficiary accounts | UPEs building up, distributions only on paper, cash sitting in wrong entity |
| Tax & GST | Paid from dedicated tax account | Paid from whatever account has money that day |
| Evidence for the bank | 6–24 months of simple, explainable flows and clean statements | Hard‑to‑follow patterns, unexplained transfers and inter‑entity movements |
 How you move money from your company can either support or hurt home loan approval. ### 1. Director loan accounts and home loans From a lender’s perspective, a director loan account can be either: - An asset (the company owes you money); or - A liability (you owe the company money). If you owe the company, banks may treat it like another personal debt. If it’s caught by Division 7A, there might also be minimum yearly repayments the bank…
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How far back do lenders look at my company and trust cashflow?▾
Will my home loan be declined if I’ve used redraw for business expenses?▾
Do banks prefer salary or dividends from my own company?▾
How should a family trust pay me so banks will count the income?▾
Is it OK to pay some personal bills from my business account?▾
Do I need a complex multi-entity structure to protect my home loan?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.