Article
How to Upgrade, Renovate and Move Without Smashing Your Cashflow
A practical, decision‑grade guide for upgrading to a premium home, timing your sale, and funding renovations without blowing up family or business cashflow.
Key Takeaway
This article explains how Australians can coordinate selling, buying and renovating a premium home without blowing cashflow by first calculating peak debt and setting a hard buffer floor of 3–6 months’ living and loan costs. It outlines three main sequencing options, typical temporary accommodation costs, and how to structure construction plus purchase finance using staged drawdowns rather than redraw. A worked $2m example shows why ring‑fencing business and renovation funding is critical so a slow business quarter doesn’t jeopardise the family home.
Coordinating a sale, purchase and renovation on a premium home without smashing cashflow comes down to three numbers: your peak debt, your minimum cash buffer, and the true cost and timing of the renovation. Once those are clear, you can choose a sequence (sell first, buy first, or overlap) and a finance structure that keeps you liquid even if the sale underperforms or the build runs late.
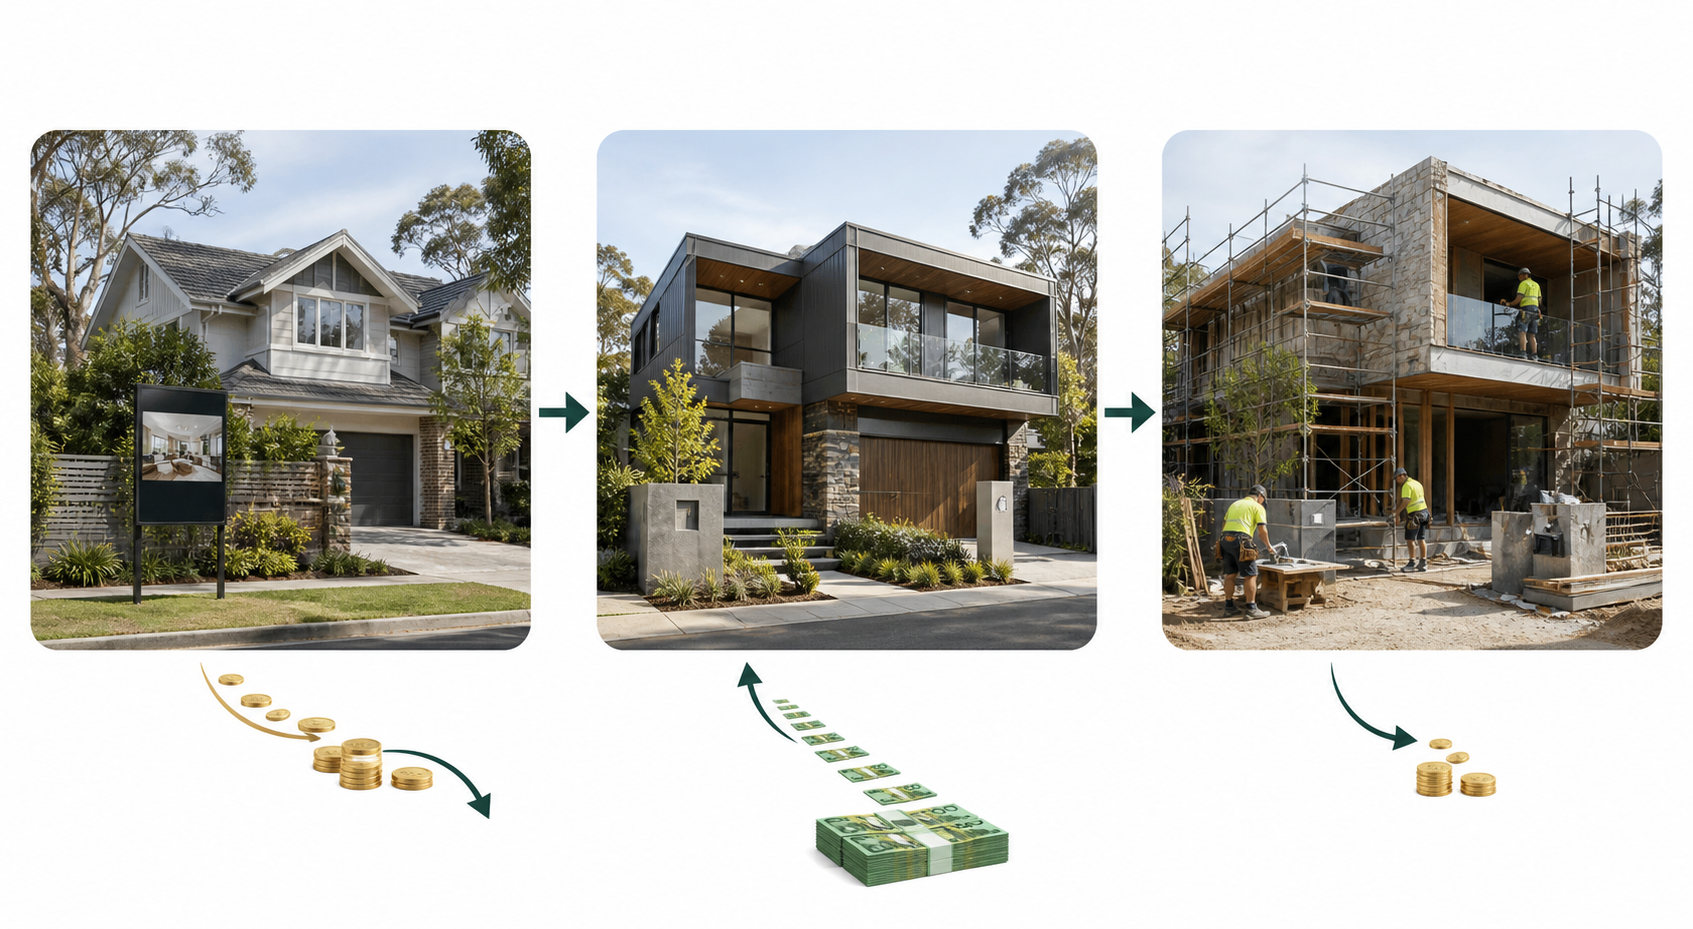
Step 1: Define your safe “peak debt” and buffer
Your peak debt is the highest combined debt you’ll hold at any point between now and when works are finished (old loan + new loan + construction funding).
For most households, a safer ceiling is:
- Total repayments comfortably covered at 6–7% interest, plus
- A 3–6 month cash buffer for living costs and loan payments, sitting in offset.
For business owners, I’d usually add:
- A separate business buffer (1–3 months of fixed costs), and
- No reliance on home loan redraw to plug business shortfalls (see also /insights/separating-business-personal-cashflow-mascot).
Worked example (Sydney upgrade):
- Current home: $1.6m, loan $700k
- Target home: $2.6m
- Planned renovation: $400k
- Stamp duty and costs: say $150k
Peak moment could be:
- Old loan $700k + new loan $2m + construction funds $400k ≈ $3.1m.
At 6.5% P&I over 25 years, that’s roughly $21k–$22k per month in repayments. If that number scares you, your plan needs to change before you sign anything.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Can I live in the house while renovating a premium home?▾
Is it safer to sell my old home before buying and renovating the new one?▾
How much contingency should I allow for a major renovation?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.