Article
How To Use Gifted Deposits For Off‑the‑Plan Without Tax Or Bank Drama
A practical guide to using family gifts for off‑the‑plan deposits without blowing up your finance approval, triggering tax problems or causing future family disputes.
Key Takeaway
Gifted deposits can be used for off‑the‑plan purchases in Australia, but banks apply strict rules around evidence, genuine savings and timing, and the ATO treats most gifts as non‑taxable to the recipient. Lenders typically want 5% of the purchase price as genuine savings and a signed gift letter confirming funds are non‑repayable, while Centrelink can still apply gifting rules for the parents. The actionable step is to document the gift clearly as gift/loan/guarantee, align it with estate plans, and have your broker pre‑test bank policy before you exchange contracts.
Buying off‑the‑plan often means tying up a big deposit well before you get the keys. For many Australians, that gap is bridged by family help. A gifted deposit can absolutely work for an off‑the‑plan purchase – but banks, the ATO and Centrelink all have rules you need to get right, and the long settlement adds extra traps.
This guide explains how banks treat gifted deposits, what counts as genuine savings, how to evidence the gift, and where the tax and family‑law landmines sit. The goal is simple: structure the gift so you can get finance approved and keep the family peace.
1. Gifted deposits off‑the‑plan: how it actually works
A gifted deposit is money given to you, usually by parents or close family, to help fund your purchase deposit with no expectation of repayment. For off‑the‑plan, the gift might cover:
- The 10% contract deposit at exchange
- Top‑up funds closer to settlement if the valuation comes in short
- Extra cash to keep your buffers intact when rates and costs move over the 18–36 month build
1.1 Typical off‑the‑plan deposit structure
For a $800,000 off‑the‑plan unit:
- 10% deposit at exchange: $80,000
- Remaining 90% ($720,000) due at settlement, usually funded by a home loan
A gifted deposit could:
- Provide part or all of the $80,000 at exchange; and/or
- Sit in your account as additional buffer so you don’t empty every last cent.
If your parents don’t want to hand over cash straight away, they might instead back a deposit bond or bank guarantee, or release equity as explained in /insights/structuring-equity-releases-deposit-bonds-off-the-plan.
1.2 Why off‑the‑plan makes gifts trickier
Compared with a normal purchase, off‑the‑plan adds three complications:
- Time gap – Banks re‑assess your position at settlement, often 18–36 months later.
- Valuation risk – If the final valuation is lower than the contract price, you may need more cash or a bigger gift.
- Policy drift – Bank and tax rules can change between exchange and settlement.
That’s why you should treat the family gift as part of a broader risk plan, not just a quick way to ‘get the deposit sorted’. The risk checklist in /insights/risk-management-checklist-mixing-guarantees-gifts-schemes-off-the-plan is worth having beside you as you read this.
2. Bank rules: when gifted funds are and aren’t OK
Each lender has its own policy, but most follow a similar pattern.
2.1 Genuine savings vs non‑genuine savings
Genuine savings are funds you have saved yourself over time – typically money held in your name in a bank account for at least 3 months.
For many lenders:
- First‑home buyers need at least 5% of the purchase price as genuine savings if borrowing above 80% LVR.
- A family gift on its own is usually classed as non‑genuine savings.
Some lenders are more flexible if:
- You have strong income and low debts; or
- You’ve been paying rent on time with a formal lease and can show a 6–12 month history.
Key idea: a gift can absolutely form part of your deposit. The question is whether the lender will accept 100% gifted deposit, or require some of your own genuine savings as well.
2.2 How much gift is too much?
Indicatively (policies change and differ by lender):
- 80% LVR or below – Many banks are relaxed if the entire 20% deposit is gifted, provided there’s a clear gift letter and your borrowing capacity is strong.
- Above 80% LVR – Most lenders want at least 5% of the purchase price in genuine savings. A 90% LVR loan on $800,000 means:
- Minimum 5% genuine savings: $40,000
- Remaining 5% of the deposit plus costs could be gifted.
Some specialist lenders will allow 100% gifted deposit at high LVRs, but pricing and conditions can be tougher.
2.3 Off‑the‑plan twist: re‑checking the gift at settlement
Because off‑the‑plan settlements are so far away, banks usually:
- Confirm at pre‑approval stage that the gift is expected
- Re‑check bank statements 1–3 months before settlement to see the funds actually there
If your parents were planning to drip‑feed the gift over time, this can bite. The lender wants to see the full deposit and costs available in the lead‑up to settlement, not just a promise.
2.4 Acceptable sources of gifted funds
Most mainstream lenders are comfortable with gifts from:
- Parents
- Grandparents
- Siblings (sometimes)
- Very long‑term partners or spouses
They are more cautious with gifts from:
- New partners
- Friends
- Overseas donors where source of funds is unclear
There’s also an anti‑money‑laundering (AML/CTF) overlay. Large overseas transfers may trigger extra questions or delays.
3. Evidence banks want: gift letters and money trails
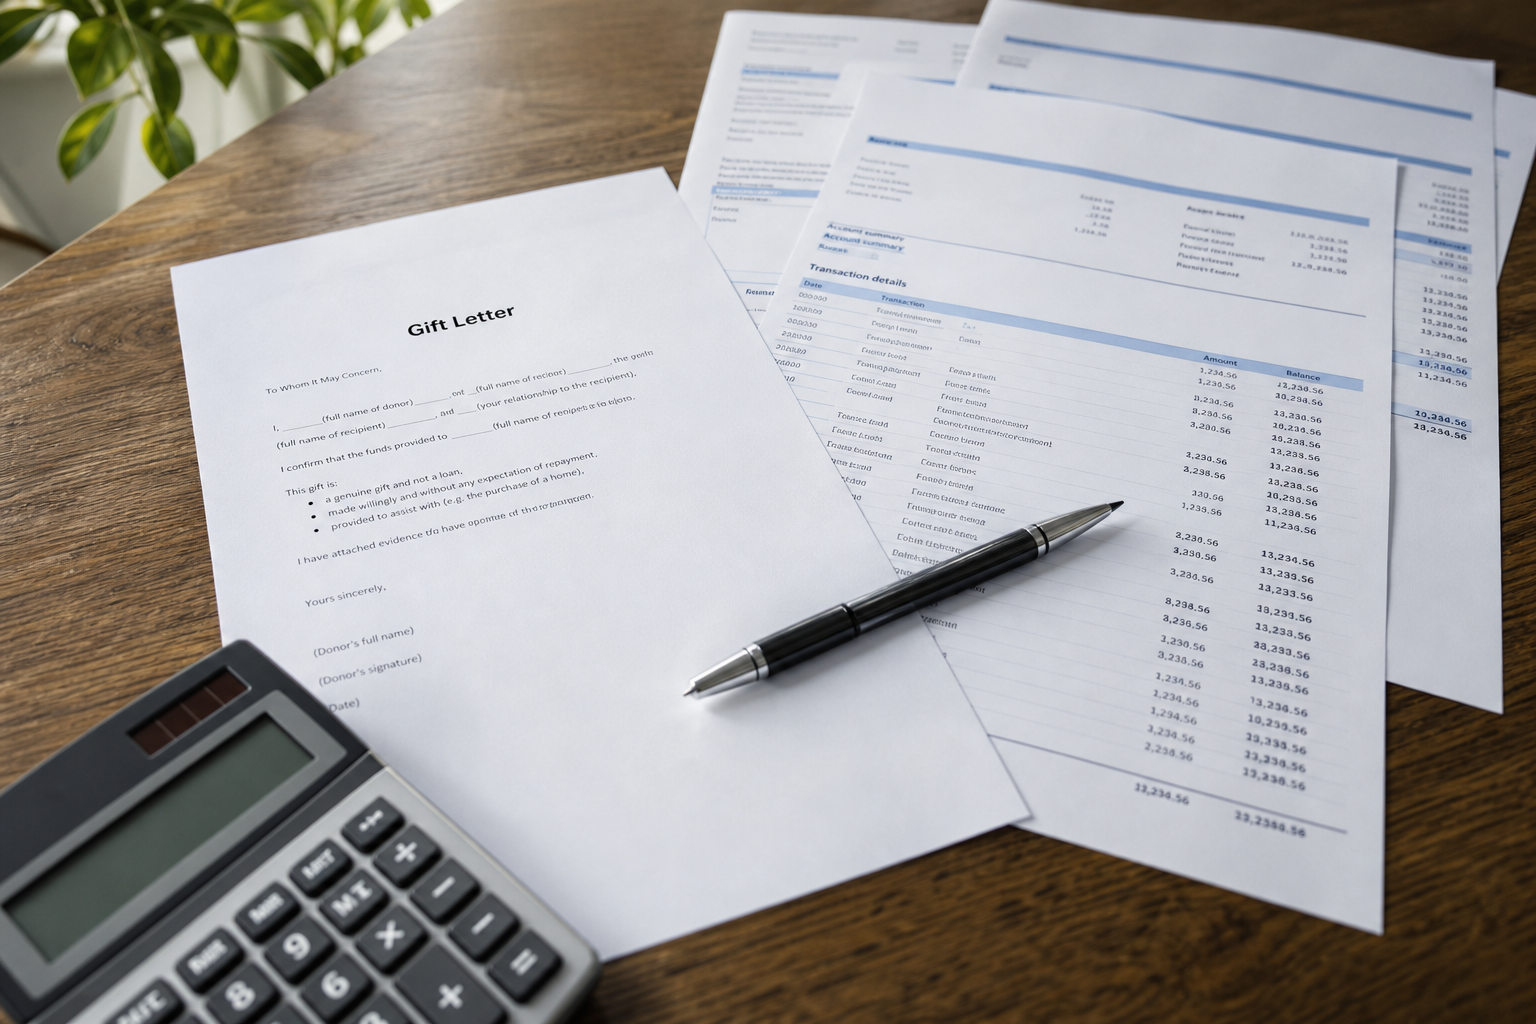
To approve a loan with a gifted deposit, banks generally require two things:
- A signed gift letter/statutory declaration; and
- Bank statements showing the funds in your account.
3.1 What goes in a gift letter
Every lender’s form looks a little different, but most want the following:
- Full name, address and contact details of the donor
- Full name of the recipient(s)
- Relationship (e.g. parents, grandparents)
- Exact amount of the gift
- Statement that the funds are a non‑repayable gift with no interest and no security
- Statement that the donor will not obtain any ownership in the property
- Signature of the donor (sometimes also the recipient), often witnessed
Some lenders insist on a statutory declaration instead of a simple letter.
3.2 Timing: when to transfer the money
Your bank or broker will usually want to see:
- The gift in your account at least 1–3 months before settlement; and
- A clear transaction record from the donor’s account to yours.
For off‑the‑plan, that might mean:
- A smaller initial transfer to cover the 10% deposit; then
- A later top‑up closer to settlement when your full costs are known.
Just be aware that last‑minute transfers from overseas or from a redraw/offset can cause delays or extra questions.
3.3 Money trail documentation
Expect the lender to ask for:
- Donor’s statement showing the money leaving
- Your statement showing the money arriving
- Evidence that neither account is an overdraft or business facility
If the donor pulled cash from their home loan or equity release, the lender may want to see that facility too – to understand if this is really a gift or a disguised guarantee.
4. Genuine savings workarounds: rent, equity and schemes
If you don’t have the full 5% genuine savings, there are still options – especially for first‑home buyers.
4.1 Rental history as genuine savings
Some lenders accept a properly documented rental history as genuine savings, particularly when:
- You’ve been on a formal lease for at least 6–12 months
- Rent has been paid on time from your account
- The rent amount is a solid reflection of future mortgage repayments
This can work well when parents are gifting the bulk of the deposit but you’ve demonstrated good financial discipline through rent.
4.2 Government schemes and gifted deposits
If you’re using the First Home Guarantee, FHBG, or other schemes, be very careful how gifts interact with them. The companion article “Combining First Home Guarantee, FHSS and Savings for Off‑the‑Plan Deposits” in this cluster goes deep on those rules.
In short:
- Some schemes have minimum savings or contribution requirements
- Over‑gifting can accidentally disqualify you from targeted assistance
- With FHSS, you need to understand which contributions can be released and how that sits alongside a family gift
4.3 Equity releases and deposit bonds
Parents who are asset‑rich but cash‑poor might use their home equity instead of writing a cheque. That can look like:
- An equity release loan in the parents’ names, then a cash gift to you
- An equity‑backed deposit bond/bank guarantee instead of cash at exchange
The strategy and timing of these options are explored in depth in /insights/structuring-equity-releases-deposit-bonds-off-the-plan. The key is to remember that the real risk point is final settlement, not the day you exchange or lodge the bond.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Can I use 100% gifted deposit for an off-the-plan purchase?▾
Do I pay tax on gifted money for a home deposit in Australia?▾
Can my parents’ gift be treated as a loan instead?▾
Will a big gift affect my parents’ Age Pension?▾
What happens if my off-the-plan valuation comes in lower than the contract price?▾
Do banks accept gifts from overseas family members?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.