Article
Match Your Loan Strategy To Your Eastern Suburbs Postcode
Not all Eastern Suburbs postcodes behave the same. This guide shows how family, investor, prestige and downsizer pockets each call for different loan structures, buffers and lender choices – so your finance fits the street you’re actually buying in.
Key Takeaway
This article explains how to match your loan strategy to different Eastern Suburbs postcode types by segmenting them into family strongholds, investor pockets, prestige strips and downsizer enclaves. It outlines how each segment behaves in rate rises and downturns, referencing that around 32.5% of Australian mortgage holders are now ‘At Risk’ of stress, and shows which loan structures, buffers and lender choices best fit each. Readers get a practical, postcode‑aware finance checklist to act on this week.
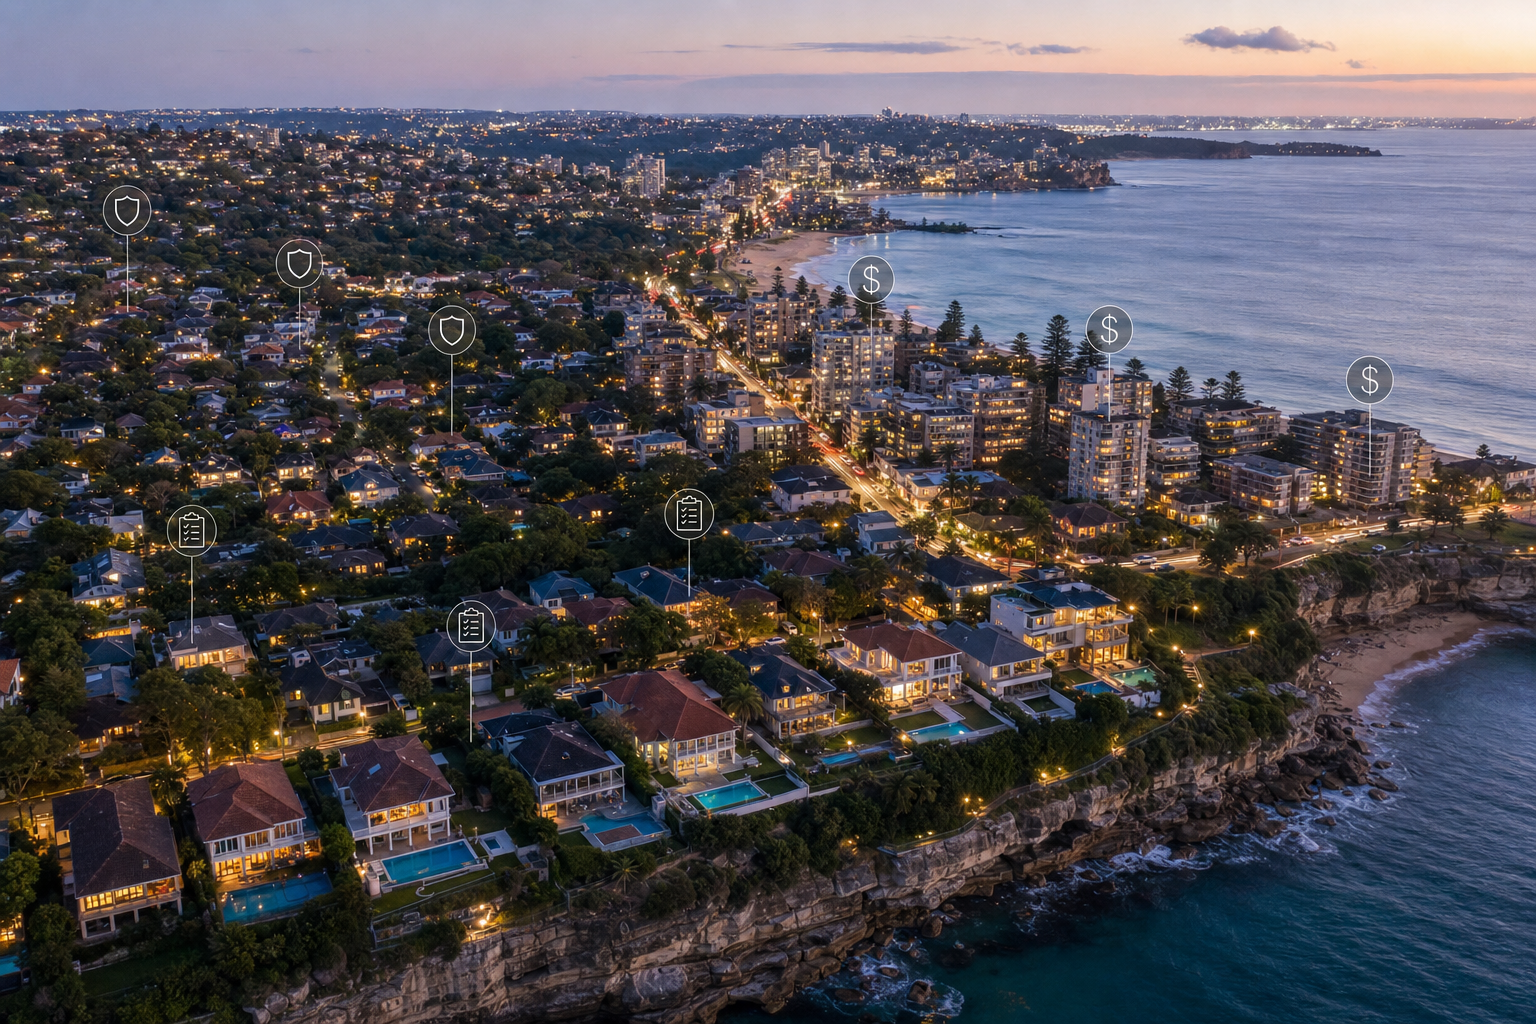
Not every Eastern Suburbs postcode behaves the same way – and your loan shouldn’t either.
Some pockets are investor-heavy and swing with yields. Others are tightly held family streets that barely trade. Prestige strips can move hundreds of thousands of dollars in a few months when confidence shifts. Downsizer enclaves react to very different pressures again.
If you use a one-size-fits-all loan in such different markets, you’re the one carrying the risk.
This guide shows how to match your loan structure, buffers and lender choice to your specific Eastern Suburbs postcode type, so your finance fits the street – not just the bank’s spreadsheet.
1. Why postcode type should drive your loan strategy
1.1 The 60‑second answer
- Different postcode types react differently to shocks. Investor pockets, family strongholds, prestige strips and downsizer enclaves do not move in sync when rates rise or credit tightens.
- Your loan should mirror that risk. More volatile, investor‑driven and fringe areas usually call for bigger buffers, cleaner exits and conservative valuations. Blue‑chip family streets or settled downsizer pockets allow a slightly different mix of risk and flexibility.
- APRA’s 3% buffer doesn’t protect you from lifestyle risk. Lenders test your borrowing at ~3% above today’s rates, but they don’t know about school fees, business volatility or your actual tolerance for stress.
You should deliberately choose loan structures, offsets, fixed vs variable and lender type based on your postcode’s behaviour in a downturn, not just the property’s glossy photos.
1.2 Why this matters more in 2026
Roy Morgan’s July 2026 research shows 32.5% of Australian mortgage holders are now ‘At Risk’ of stress, the highest in 18 years, as the cash rate sits around 4.35%. At the same time, the RBA notes that post‑COVID credit markets transmit rate rises more powerfully than before.
In plain English: the same loan mistake hurts faster than it used to.
In the Eastern Suburbs, where even a modest apartment can mean a $1m+ loan, a poorly matched structure can push you into:
- Forced sales in a soft patch
- Missed upgrade or investment opportunities because of tight servicing
- Tax headaches from blurred loan purposes
We’ll walk through each major postcode type and show you how to avoid that.
2. Mapping Eastern Suburbs postcode types to lending risk
Every suburb is unique, but from a lender’s point of view there are clear patterns. Building on the parent piece “Investor Hotspots vs Family Strongholds: Segmenting Eastern Suburbs Property Demand”, we’ll use four broad postcode types:
- Investor‑focused pockets – high proportions of rentals, smaller units, transient tenants
- Family strongholds – houses or large units near schools and parks, low turnover
- Prestige owner‑occupier strips – $3m+ stock, lifestyle‑driven, discretionary buyers
- Downsizer and empty‑nester enclaves – low‑maintenance, often near the water or villages
Within each, lenders quietly adjust how much they love (or dislike) your property, which feeds directly into borrowing power and policy. For a deeper “street‑level” view, see Finding Real Value in Sydney’s Eastern Suburbs: A Lender’s Street‑Level View.
2.1 Indicative postcode‑type risk matrix
These are general patterns, not hard rules, but they’re close to how credit teams think:
| Postcode type | Typical property | Liquidity in downturn | Volatility | Lender attitude (indicative) |
|---|---|---|---|---|
| Investor‑focused pockets | Small–mid units | Can slow sharply | Higher | More policy sensitivity |
| Family strongholds | Houses / big units | Relatively resilient | Moderate | Generally favourable |
| Prestige owner‑occupier strips | $3m+ houses / apts | Can freeze suddenly | High | Very case‑by‑case |
| Downsizer / empty‑nester enclaves | Quality low‑maintenance | Moderate | Lower | Usually solid, age‑aware |
Your loan strategy – LVR, buffers, fixed vs variable, how many splits – should lean more conservative as you move right and up that table.
3. Investor‑focused pockets: yields, vacancy and conservative leverage
These are the streets where rental listings outnumber prams. Think high‑density corridors, blocks favoured by students, professionals and short‑term renters.
3.1 How these postcodes behave
Investor pockets often:
- React quickly to RBA moves – yields shift as rates change
- See bigger spreads between over‑hyped and under‑the‑radar blocks
- Are more exposed to policy shocks (e.g. lending rule changes, Airbnb restrictions)
In the 2022–2024 tightening cycle, we saw:
- Some investor‑heavy corridors off the beach overshoot on the way up
- Later, valuations for small units became patchier, especially where supply was high
That doesn’t make them “bad”, but they demand a cleaner and more defensive loan plan.
3.2 Core loan strategy for investor‑focused pockets
Key principles:
- Keep LVR comfortable. Where possible, aim ≤80% to avoid LMI and give room if values dip.
- Separate purposes ruthlessly. Investment loan splits vs any owner‑occupied or personal debt. (Interest deductibility is about purpose, not which property secures it – see facts 2, 5, 8, 10 and 11 in the knowledge set.)
- Prioritise cashflow and buffers. You may cope with a vacancy, but your lender’s serviceability model won’t.
Recommended structures often include:
- 2+ loan splits:
- Split A – investment purchase (interest‑only or P&I depending on stage)
- Split B – costs / future improvements
- Separate offsets per purpose, so rent and investment expenses never mix with personal cash.
For a worked approach to debt consolidation in these areas, see Smartly Rolling Personal Debts Into Your Eastern Suburbs Mortgage.
3.3 Worked example – investor unit in an inner‑east block
- Purchase price: $1,000,000
- Loan: $800,000 (80% LVR)
- Rate: 6.0% p.a. (illustrative)
- Term: 30 years, interest‑only for 5 years then P&I
Interest‑only period:
- Annual interest ≈ $48,000
- Monthly ≈ $4,000
APRA serviceability test (approx 3% buffer):
- Assessed rate ≈ 9.0%
- Assessed repayment (P&I over remaining term) ≈ $6,400–$6,700 per month
If net rent covers $3,000 per month and you cover the rest, your true cashflow buffer needs to handle at least $3,500–$4,000/month if:
- Rent falls
- Rates move higher before your fixed/IO period ends
Following the knowledge facts on buffers for volatile income and short‑term letting (facts 3, 9, 15, 16, 20), a prudent buffer here is 6–12 months of stressed repayments plus essential living costs in offset.
3.4 Lender selection for investor pockets
In these postcodes, you’re usually weighing up:
- Big banks – strong appetite for vanilla investor loans but can be twitchy on high‑density or specific buildings
- Boutique lenders / non‑banks – more flexible on policy (e.g. high‑density, NRAS, company title) but often higher rates or fees
For a side‑by‑side comparison of lender types, see Eastern Suburbs Home Loans: Local Boutique Broker, Bank Or Call Centre?.
4. Family strongholds: stability, schools and upgrade pathways
Family strongholds are the postcodes where:
- Stock is tightly held
- School catchments and parks matter more than short‑term yields
- Most buyers are owner‑occupiers with long time horizons
4.1 How these postcodes behave
Historically, these pockets:
- Fall less and later in downturns
- See consistent demand from upgraders and local families
- Are deeply constrained on the sell side – few listings, many eyeballs
From a lender’s point of view, these are often “core” locations. Big loan sizes are common, but credit teams generally like the security.
4.2 Core loan strategy for family strongholds
Here the risk is less about catastrophic price falls and more about:
- Over‑gearing on a family home
- Rising repayments colliding with school fees and childcare
- One partner’s income dropping (parental leave, part‑time work, business slowdown)
Key strategy points:
- Anchor repayments to a stress‑tested ceiling. As in Designing a $2–5m Eastern Suburbs Loan That Can Take Pain, aim for 30–35% of after‑tax income at current rates +3%.
- Favour P&I on the home. Non‑deductible debt is your enemy. Knock it down methodically.
- Use offsets for flexibility. Avoid redraw for key buffers; true offsets are cleaner if you later convert the home to an investment (consistent with knowledge facts 2, 4, 5 and 11).
4.3 Worked example – upgrading to a family house
- Current unit value: $1,200,000, remaining loan $600,000
- New home price: $2,200,000
- Sale of unit: clears $600,000 debt, leaves $600,000 net equity after costs
- Required loan on new home: $1,600,000 (≈73% LVR)
At 6.0% over 30 years P&I (illustrative):
- Repayments ≈ $9,600/month
- APRA test at 9.0%: assessed repayment ≈ $12,800–$13,000/month
If combined after‑tax income is $30,000/month, your APRA‑stressed ratio is ~43% – on the high side of safe.
A safer structure could be:
- Aim to cap assessed repayments at ≤35% of after‑tax income
- That may mean:
- Buying at $2.0m rather than $2.2m, or
- Increasing deposit (family assistance, staged move), or
- Extending timeframe and building more savings
4.4 Buffer and contingency planning
For stable PAYG households, a robust target is:
- 6–12 months of total living costs plus mortgage repayments at a stressed rate in offset (see facts 1, 3, 9, 16, 17, 20).
This is particularly important before major renovations, as detailed in the Dover Heights renovation guide (fact 1).
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 10 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Why does my Eastern Suburbs postcode type matter for my loan?▾
How big should my buffer be for an Eastern Suburbs mortgage?▾
Should I use interest-only or principal-and-interest in Sydney’s East?▾
Do I need separate loan splits for my home and investment property?▾
How does being self-employed change my loan strategy in the Eastern Suburbs?▾
Is a boutique Eastern Suburbs broker better than going direct to a bank?▾
Can I safely rely on online calculators to plan my Eastern Suburbs mortgage?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.