Article
Designing Multi‑Lender Strategies To Bulletproof Your Property Portfolio
A multi‑lender strategy spreads your property loans across different banks and non‑banks so no single credit policy, rate rise or ‘computer says no’ decision can cap your portfolio. This guide shows how to design, sequence and stress‑test that structure in a week.
Key Takeaway
A multi‑lender strategy spreads a property portfolio’s loans across several banks and non‑banks so no single lender’s credit policy, appetite or rate changes can cap growth or force distressed sales. In Australia this is especially important as APRA’s 3% serviceability buffer and tighter investor tax rules have pushed more borrowers into policy bottlenecks. Structuring one primary loan per property and sequencing lenders by role lets investors protect borrowing power, ring‑fence risk and keep refinancing options open.
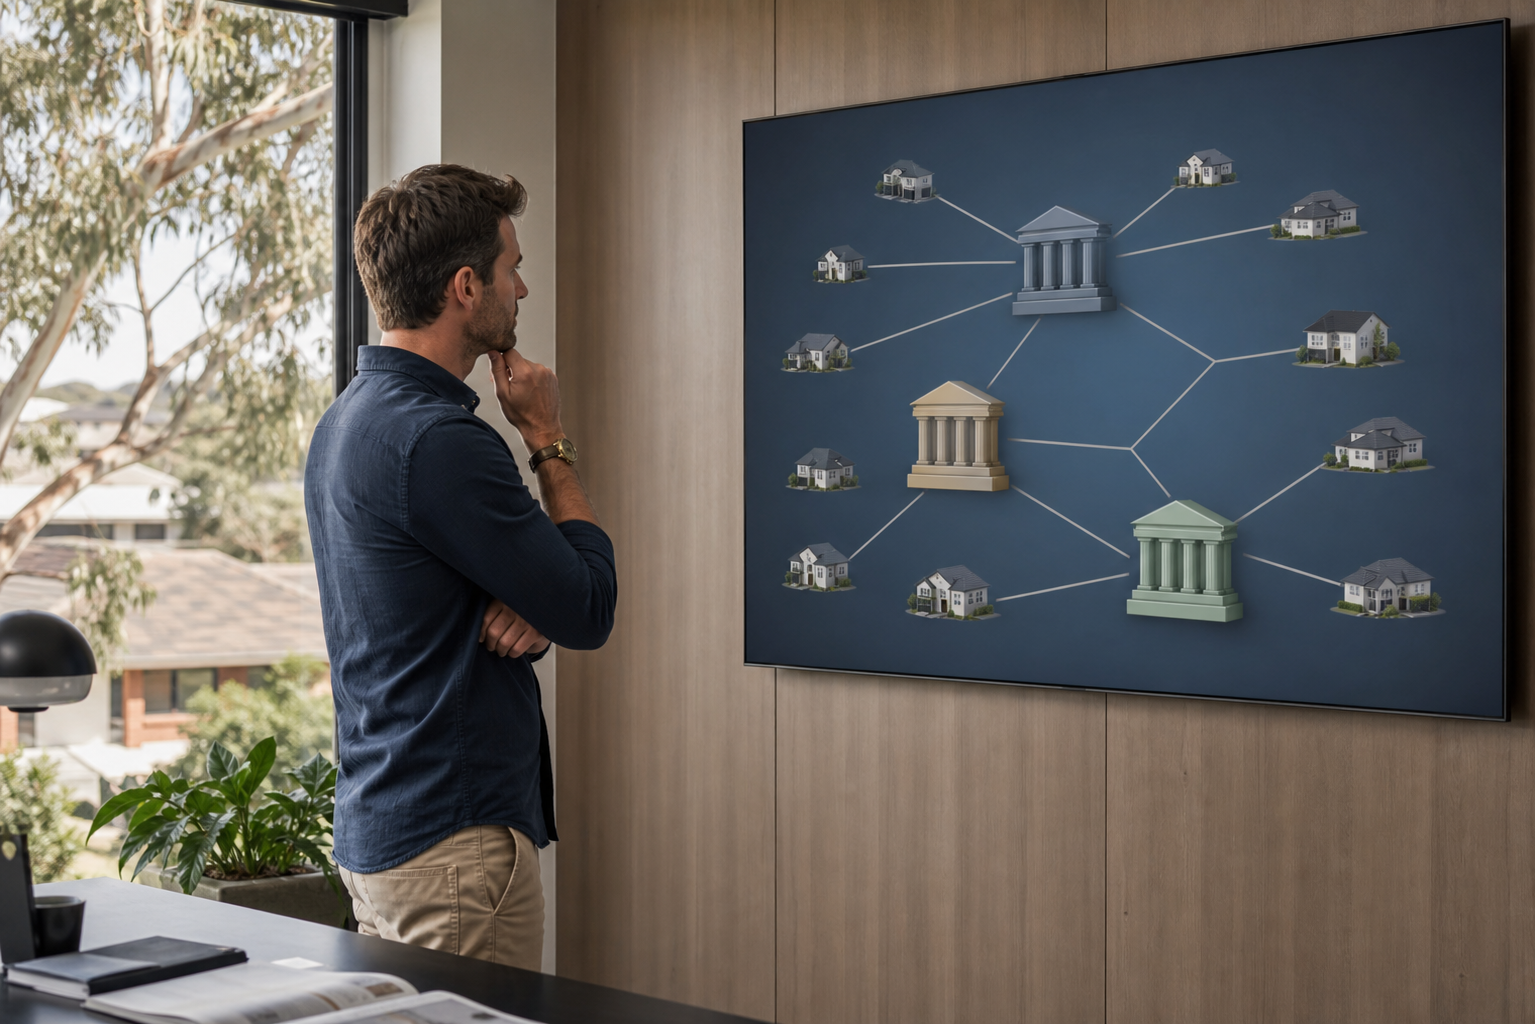
A multi‑lender strategy means deliberately spreading your property loans across different banks and non‑banks so no single lender controls your whole portfolio. For most Australian investors, this reduces concentration risk, sidesteps policy roadblocks and keeps refinancing options open as APRA rules, tax settings and bank appetites change.
In practice, that looks like: one primary loan per property, minimal cross‑collateralisation, and different lenders playing different roles (home, early investments, higher‑risk deals, business).
Why concentration risk is a real problem now
1. One lender can cap your whole strategy
If all your loans sit with one bank, that bank’s credit policy becomes your ceiling. When it tightens serviceability, shading of rental income or HEM assumptions, your entire borrowing capacity can drop even if other lenders would say yes.
The RBA and APRA have both highlighted tighter credit and higher mortgage stress since 2024, with APRA still expecting lenders to apply at least a 3% serviceability buffer. If your only bank is conservative, you wear the full impact.
2. Policy and tax changes are hitting investors unevenly
Post‑reform negative gearing rules and the recent investor tax changes described by the RBA have made some lenders more cautious with investment-heavy portfolios. Others remain more comfortable with interest‑only (IO) periods or higher debt‑to‑income (DTI) ratios.
A multi‑lender approach lets you place:
- your home loan with a sharp‑priced, conservative major
- your growth investments with a lender more tolerant on DTI and IO
- any temporary ‘messy’ deal with a specialist non‑bank
If one lender turns cold on investors, you still have options.
Single‑lender vs multi‑lender: key trade‑offs
| Strategy | Pros | Cons | Best for |
|---|---|---|---|
| All loans with 1 bank | Bundle discounts, 1 app, simple statements | High concentration risk, harder to sell/refi 1 property | Simple home + 1 investment |
| 2–3 banks, no structure | Some diversification, access to different policies | Ad hoc limits, hidden cross‑collateral, messy tax tracing | People who’ve added loans over time |
| Planned multi‑lender | Low concentration, flexible refi/sale, clearer buffers | More admin, need a map and good broker | Active investors, self‑employed, small business |
A planned multi‑lender strategy typically sits in the third column. It’s what we cover here and builds on the structures in Why smart investors use different lenders across their portfolio.
Core design principles for a safer portfolio
1. One primary loan per property, minimal cross‑collateral
Across our articles we keep coming back to this rule: one primary loan per property with minimal cross‑collateralisation materially improves your ability to sell, refinance or de‑gear individual assets.
Where you’ve already got cross‑collateralised loans, the techniques in Safely unwinding cross‑collateralised home and business loans apply equally to pure investment portfolios.
2. Allocate different roles to different lenders
Think of lenders as playing positions on a team:
- Anchor lender (usually a major) – holds your home loan, maybe your first investment; focus on sharp pricing and good offsets.
- Growth lender – more flexible on DTI, rental shading and IO; holds your 2nd–4th investments.
- Tactical/non‑bank lender – used sparingly for deals that don’t yet fit majors (complex income, recent self‑employment, unusual security). See Using non‑bank and near‑prime lenders in a property strategy.
Your structure should survive one lender changing its rules without forcing a fire sale.
3. Match APRA buffers and your own stress tests
APRA expects a 3% buffer over actual rates. In mid‑2026, with standard variable rates often around 6–7% for investors, assessment can occur at 9–10%.
You should also run your own stress test: add 3% to your current rate, hold rents flat, and assume up to three months’ vacancy per year. If the numbers only work at today’s rate, with full negative gearing benefits, they’re too tight.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is it bad to have all my property loans with one bank?▾
Do multiple lenders mean much more admin for my portfolio?▾
Will I always pay higher rates with a multi‑lender strategy?▾
How many lenders is ideal for a property portfolio?▾
When should I review my lender mix and structure?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.