Article
How To Bid Smart On High‑Demand Eastern Suburbs Streets
A decision‑grade guide to negotiating and bidding in the hottest Eastern Suburbs streets, balancing emotion, valuations and lender risk so you don’t overpay in a premium pocket.
Key Takeaway
This guide explains how to negotiate and bid safely in high‑demand Eastern Suburbs streets by anchoring offers to stress‑tested budgets and likely bank valuations, not crowd emotion. Premium pockets can see valuation gaps of 5–10% or more versus contract prices, which directly affects deposits, LVR and lender choice. Readers learn week-ready tactics to price micro-locations, plan for valuation risk, and structure loans that can withstand both RBA rate shocks and local market swings.
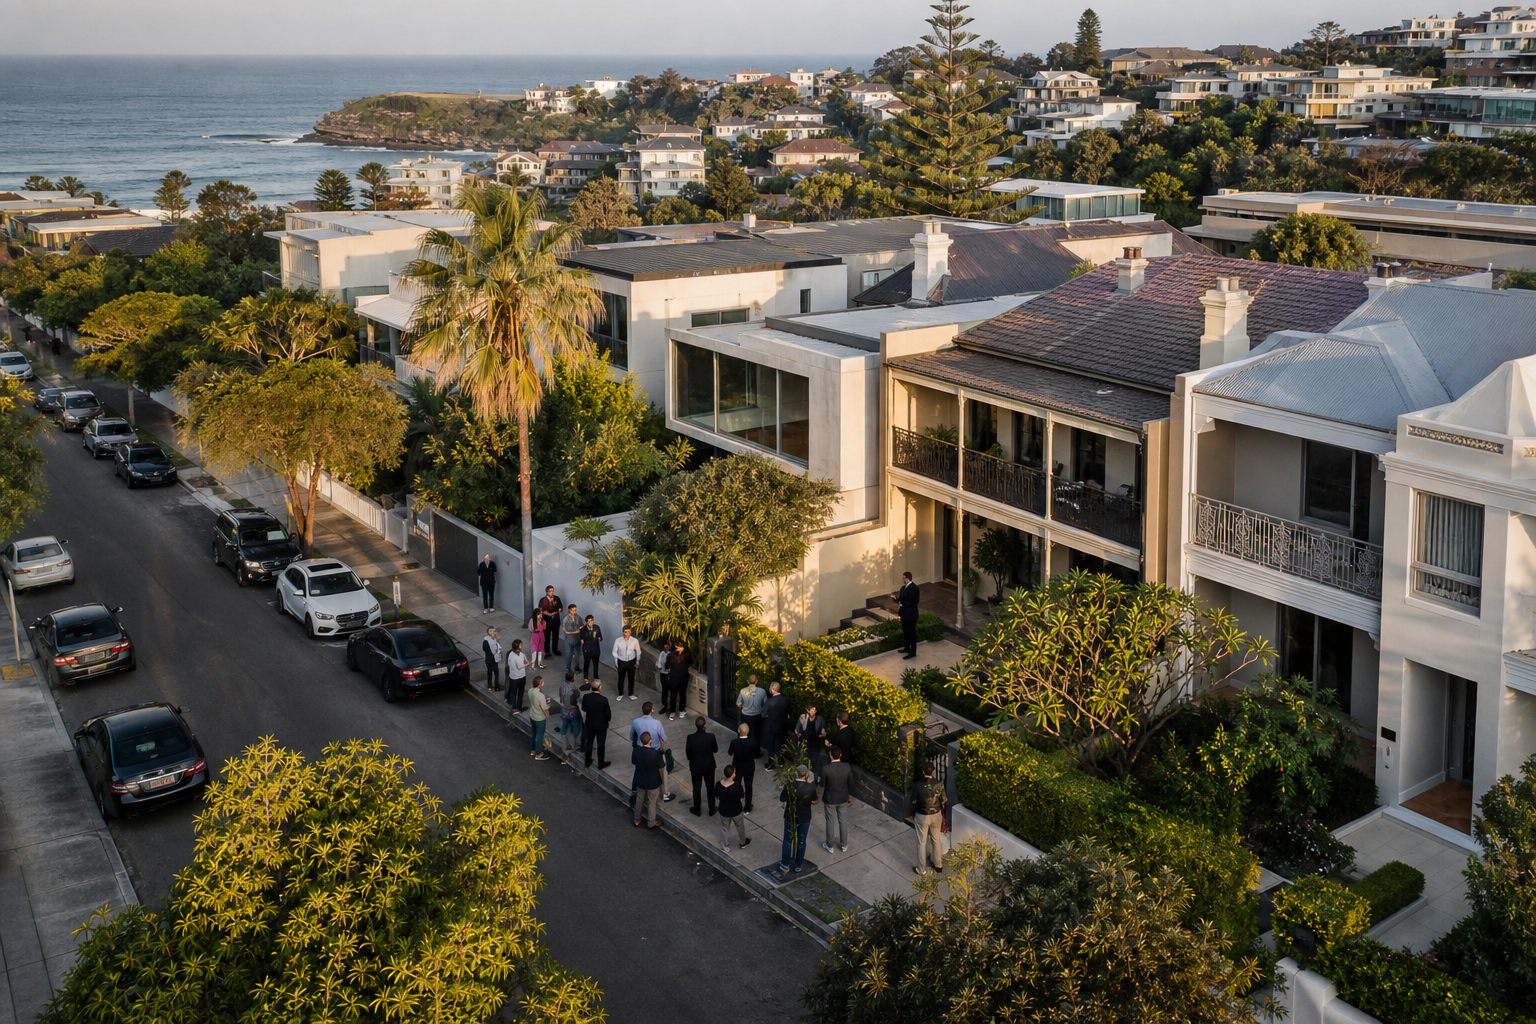
Buying or investing on a premium Eastern Suburbs street is not like buying in a normal suburb.
In these pockets, recent sales can be thin, neighbours bid with decades of equity, and buyers will stretch well past valuation for a school zone, view or walk‑to‑the‑beach lifestyle. To negotiate safely, you need a street‑level pricing view, a realistic sense of bank valuation risk, and a disciplined bidding plan you can execute this week.
In high‑demand Eastern Suburbs streets, your “safe price” is the point where your stress‑tested budget, likely bank valuation and buffer all still work – not the number the agent or crowd pushes you to. The tactics below assume current RBA guidance that financial conditions are restrictive and rate risk remains live through 2027–2028 (RBA Statements 2026), so stretching too far now is dangerous.
1. What Makes A “Premium Pocket” – Street By Street
Not every expensive area is truly premium. In Sydney’s East, true premium pockets combine scarcity with deep, emotional demand.
1.1 Typical premium streets in the Eastern Suburbs
You tend to see premium micro‑markets in streets that are:
- Within tightly held school catchments for top public schools
- One or two level walks to a beach or harbour foreshore
- Very close to light rail, trains or key bus corridors
- Elevated with protected views and limited development potential
- Heritage‑constrained, keeping supply permanently tight
These streets sit behind the broader suburb data you see on portals. An average suburb growth chart can be masking a handful of streets where:
- Turnover is under 5% per year
- Neighbourhood income and equity are above the suburb median
- Bidders are mainly upgraders and downsizers, not first‑timers
That mix makes price discovery messy and emotional.
1.2 Why premium pockets don’t follow the averages
Premium streets often:
- Fall later in a downturn, but if confidence cracks they can go quiet very fast
- Attract “money is cheaper than time” buyers who outbid valuers by large margins
- Hold value better, but only if the specific attributes (catchment, views, access) stay in favour
Our piece on how prestige and fringe markets react to shocks shows that blue‑chip pockets typically see shallower price declines but much lower liquidity when the RBA tightens [/insights/prestige-vs-fringe-eastern-suburbs-economic-shocks]. That matters for your risk: you can be asset‑rich but stuck if you need to sell in a hurry.
1.3 The three prices that matter on a premium street
For any property on a sought‑after street, think in terms of three different prices:
- Emotional market price – where the winning bidder actually signs.
- Bank valuation price – what a valuer can justify off recent comparable sales.
- Your safe price – the highest figure that still works under stressed cashflow and buffer rules.
Negotiating smart means knowing those numbers won’t match – and being prepared to stick to your safe price.
2. Working Out Your “Safe Price” Before You Negotiate
The biggest mistake buyers make in premium pockets is letting the market or agent drag them up to their bank‑approved maximum.
2.1 Start with a stress‑tested borrowing limit
Your real limit is where your household cashflow still works if:
- Rates rise another 2–3% (APRA’s buffer is 3% above the actual rate for serviceability)
- One income drops or business revenue softens
- Living costs rise faster than headline CPI – non‑discretionary costs have been outpacing discretionary ones in recent ABS data
Say you’re looking at a $2.5m terrace and your broker says the bank could lend up to $2.2m today at about 6.5% p.a.
If the RBA cash rate returned to 4.35% as in 2026, your actual rate could easily hit 8.0% on this loan. Your safe borrowing size is the figure where that higher rate is still survivable.
Worked example – stress‑testing a premium purchase
- Target purchase: $2.5m
- 20% deposit + costs from savings/equity: ~$600k
- Loan size: $1.9m
- Term: 30 years, principal & interest
At 6.5%:
- Monthly repayment ≈ $12,016
At 8.0% (rate shock):
- Monthly repayment ≈ $13,961
Difference: nearly $2,000 per month. If that extra $2,000 makes your budget uncomfortably tight, your safe borrowing limit is lower, even if the bank would say yes to $2.2m.
We’ve written extensively that in hot markets, a borrower’s safe price is defined by stress‑tested cashflow and buffer, not maximum bank approval [/insights/alexandria-auction-culture-agent-tactics-shape-loan-strategy]. Premium streets magnify this rule.
2.2 Lock in your buffer before you stretch
Across our Eastern Suburbs case studies, the consistent safety line is:
6–12 months of total loan repayments plus essential living costs held in cash or true offset immediately after settlement.
For a $1.9m loan at 6.5%, that’s roughly $72k–$144k in accessible reserves. If paying “one more bid” would wipe out that buffer, it’s almost always too much, no matter how good the street is.
2.3 Convert your safe borrowing into a safe bid range
Work backwards from your safe borrowing figure.
If 8.0% stressed repayments are only comfortable up to a $1.7m loan, then:
- Safe buy price ≈ $1.7m + deposit
- With 25% cash + costs, your safe price might be around $2.25m, not $2.5m
That difference is the gap you’ll fight with yourself over during a live negotiation. Decide now.
Write down:
- “Target price” – where you’d be delighted to secure it
- “Stretch but safe price” – your absolute limit that still respects your stress‑test and buffer
- “Walk‑away rule” – what you’ll do on the day if bidding crosses that line
3. Pricing A Single Street: Data, Walks And Valuers
Premium pockets are hyper‑local. You can’t price them from suburb medians or headline clearance rates.
3.1 Start with a lender’s street‑level lens
Banks and valuers don’t love hype. They look at:
- Sales in the same street or immediate block in the last 3–12 months
- Quality and scarcity of comparable stock (same side of the road, same light, same slope)
- Physical risks – clifftop exposure, slip, flood, heritage or structural constraints
Our guide on finding real value in Sydney’s East explains how some glossy streets quietly attract tougher lending treatment [/insights/over-hyped-vs-under-the-radar-eastern-suburbs-lender-view]. Use that lens:
- If a street is on a cliff edge, near a busy cut‑through, or full of heavily renovated homes, expect a more conservative valuer.
- If an almost identical property on the same side of the street sold six months ago, that sale will heavily anchor the valuer’s number.
3.2 Do a “micro‑comp” walk
Spend 30–60 minutes walking:
- The full length of the street on both sides
- Any cross‑streets that share the same amenity (park, school gate, beach access)
For each sale you can identify from agent boards or portals, note:
- Land size and orientation
- Elevation and view lines
- Street noise and traffic patterns
- Renovation level and floorplan functionality
You’re building your own internal price map so that when you hear, “Number 12 sold for $3.1m”, you instantly know that number 18 is worth more/less and why.
3.3 Sense‑check with a valuer‑style comparison
If three “A‑grade” recent sales sit between $3.0m and $3.2m, and your target is superior on two of the three big levers (land, view, condition), it may transact above $3.2m.
But a valuer may still peg it closer to those recent comps, especially if market conditions are softening. That’s where valuation gaps appear – and where your finance strategy matters.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How much above valuation is it reasonable to pay in a premium Eastern Suburbs street?▾
Do premium streets in Sydney’s East fall less in a downturn?▾
Are auctions or off‑market deals safer in premium pockets?▾
How do I compete with cashed‑up neighbours without over‑stretching?▾
Should investors avoid premium pockets because yields are low?▾
What’s the most important rule when bidding in a premium suburb?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.