Article
Choosing Old vs New Mascot Apartments: Finance, Strata & Resale
A decision‑grade guide to buying old or new apartments in Mascot, with lender rules, strata red flags, defect risks and resale factors you can act on this week.
Key Takeaway
Old and new Mascot apartments carry different lending, defect and resale risks, so buyers must assess the specific building, not just its age. Lenders often prefer low‑rise pre‑2000 blocks with simple strata and fewer known defects, while high‑density or recently built towers can face lower loan‑to‑value ratios and valuation haircuts. Given mortgage stress now affects over 30% of borrowers nationally, Mascot buyers should stress‑test repayments, read strata reports closely, and adjust deposits and buffers to the building’s risk profile.
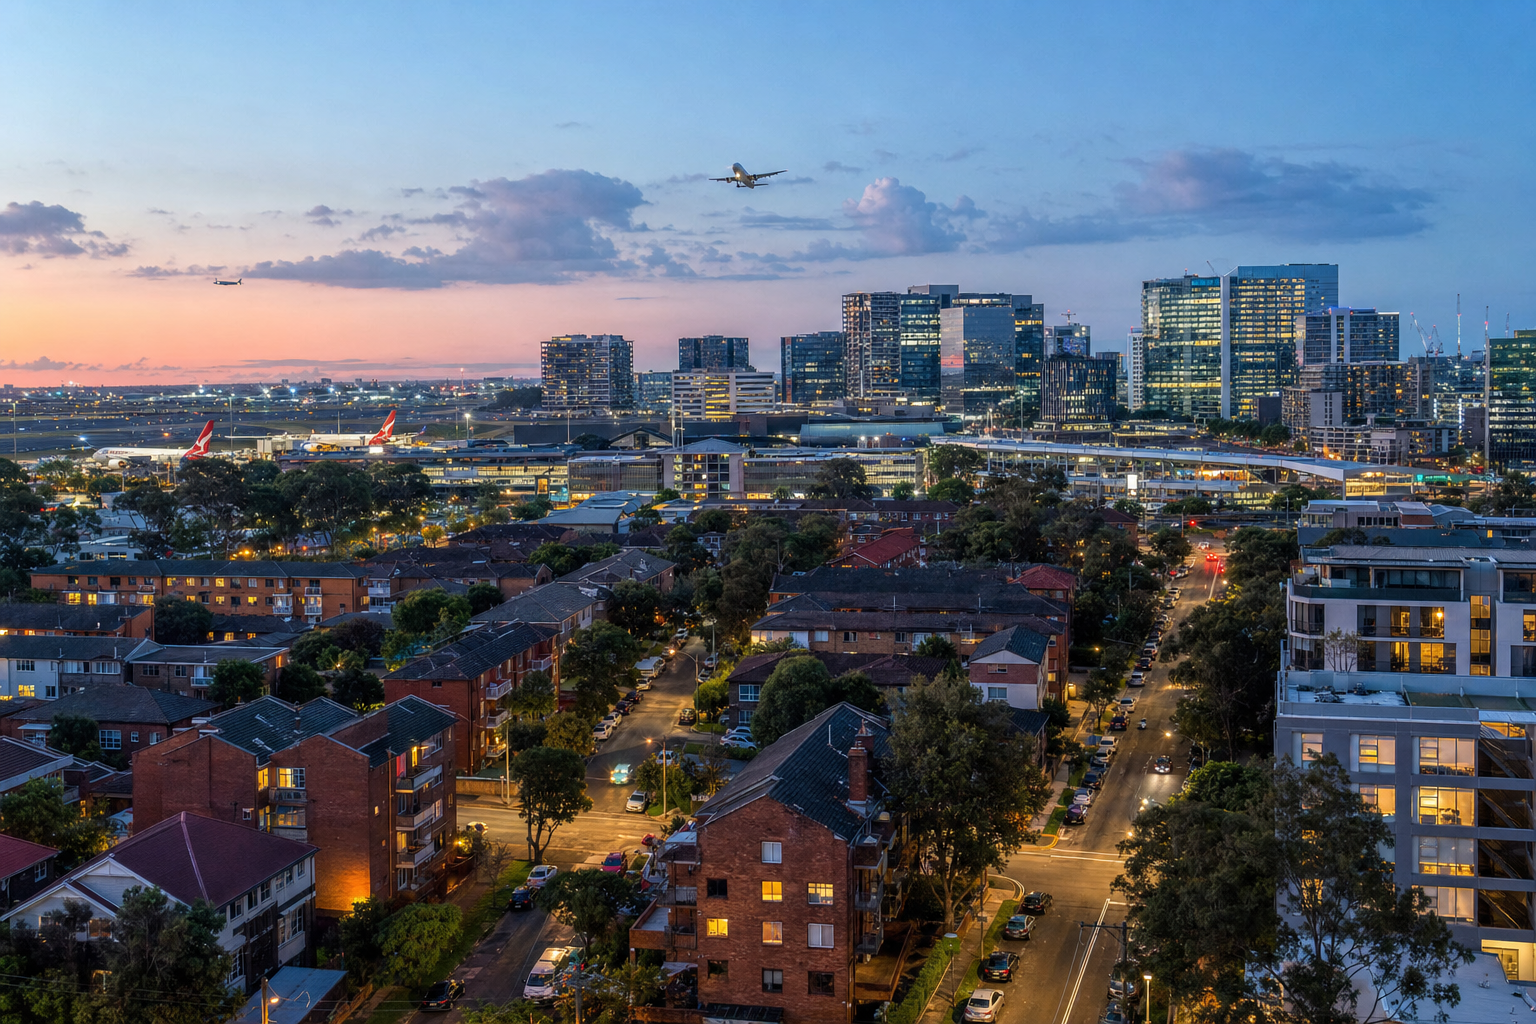
Buying in Mascot means facing a specific question: are you safer in an older low‑rise block or a newer tower closer to the station?
In Mascot, old vs new apartments are not just a style preference. Lenders, valuers and future buyers judge them differently. Older, smaller blocks can be easier to finance if they’re structurally sound with clean strata. Newer, high‑density buildings can offer lifts, gyms and better layouts – but defects, combustible cladding, high investor mixes and density can all trigger tighter lending rules and softer valuations.
This guide focuses on how building age in Mascot changes your borrowing power, strata risk and resale so you can decide what to inspect and negotiate this week.
1. Old vs new Mascot apartments – what actually counts as “old” and “new”?
1.1 Practical age brackets lenders and valuers think in
In Mascot, the market and lenders tend to think in rough bands:
- Pre‑2000 – typically low‑rise walk‑ups or small 3–5 storey blocks
- Early–mid 2000s – mid‑rise as the area started to densify
- 2010–2016 boom – many high‑rise, investor‑heavy complexes near the station
- Post‑2017 – newer stock under tighter building codes, but still some defect risk
No lender has a single Mascot “year cut‑off”, but high‑density, post‑2010 towers often attract more scrutiny than older, boutique blocks.
For a deeper comparison of older vs newer Sydney stock generally, see [Older Art-Deco Blocks vs New Builds in Sydney’s East: Finance Rules].
1.2 Old vs new in Mascot – the big trade‑offs
Think in terms of three levers, not just age:
- Finance friction – how hard your loan and valuation will be
- Ongoing costs and hassle – strata levies, defects, repairs
- Resale and refinancing flexibility – future demand and lender appetite
Older blocks often win on #1, sometimes on #3, and can be mixed on #2.
Newer blocks can win on lifestyle and accessibility, but you must work harder on #1, #2 and #3.
2. How building age in Mascot changes your borrowing power
2.1 Lender risk lens on Mascot apartments
Many lenders maintain postcode risk lists for high‑density suburbs. Mascot often appears on these lists, especially for:
- Large complexes near Mascot Station
- Mixed‑use buildings above retail
- Investor‑heavy towers with lots of one‑bed and studios
Typical lender responses can include:
- Lower maximum LVR (e.g. 80–85% instead of 90–95%)
- No lender’s mortgage insurance (LMI) waivers even for professionals
- Stricter valuation commentary (defect history, cladding, settlement data)
These rules bite harder for newer high‑density blocks than for older, small blocks on quieter streets.
2.2 Example: same borrower, different building
Assume:
- Owner‑occupier couple, combined income $190,000 PAYG
- Sensible buffers in place (3–6 months’ costs plus repayments in offset – see knowledge fact #15)
- APRA serviceability buffer of 3% applies
Two options:
-
Older 2‑bed in 1995 low‑rise block (12 units)
- Purchase price: $900,000
- Lender happy at 90% LVR with LMI
- Max loan: $810,000
- Minimum deposit (plus costs): ~$120,000–$140,000
-
New 2‑bed in 2015 high‑rise tower (200+ units, mixed‑use)
- Same price: $900,000
- Lender caps at 80% LVR due to postcode and building
- Max loan: $720,000
- Minimum deposit (plus costs): ~$200,000–$220,000
Same income, same price, but the newer high‑rise needs $60,000–$80,000 more cash purely because of lender settings.
2.3 Alt‑doc and self‑employed buyers
For self‑employed Mascot borrowers, building risk stacks on top of income complexity.
- Lenders already apply higher shading to variable or self‑employed income.
- If you’re alt‑doc (BAS, accountant letter), some lenders won’t touch certain Mascot towers.
- Others will cap LVR even lower (e.g. 70–75% on a risk‑listed building).
That’s why having one broker coordinate home, investment and business lending across Mascot can help – see [One Specialist Broker To Coordinate Home, Investment And Business Loans In Mascot].
3. Strata and defect risk: why newer isn’t always safer
3.1 The Mascot defect context
Mascot has seen headline construction issues in the past decade, including serious defects in some big complexes. You should assume lenders and valuers remember the headlines, even when a specific building is fine.
For older buildings, major structural issues are often already discovered and (hopefully) addressed. For newer towers:
- Early years can reveal hidden waterproofing or structural problems
- Some defects are still under builder’s warranty, but enforcing them can be slow and stressful
- Strata may be under‑funded because developers initially set levies too low to keep marketing attractive
3.2 Strata report differences – old vs new Mascot blocks
In Mascot, a good strata report is non‑negotiable. Here’s what often differs by age.
| Aspect | Older low‑rise (pre‑2000) | Newer high‑rise (post‑2010) |
|---|---|---|
| Major defect history | Often known and documented; may be resolved | Risk defects still emerging; NCAT actions more common |
| Strata levies | Moderate; fewer lifts & amenities | Higher; lifts, gyms, concierge, large common areas |
| Capital works fund | Healthier if long‑term owners; but can be under‑saved for big jobs | Often thin early on; heavy reliance on future special levies |
| Insurance premiums | Reasonable unless many claims | Higher for large towers; flammable cladding risk a factor |
| Meeting minutes | Plainer issues (painting, roofing, parking) | Complex issues (defects, legal action, building managers) |
Action this week: pick 2–3 target buildings in Mascot (old and new), order strata reports, and compare:
- % of budget going to capital works vs day‑to‑day
- Size and frequency of special levies
- Any mention of waterproofing, fire compliance, cladding or structural movement
This is the same lens we use for downsizers buying high‑spec apartments – see [How to Choose a Luxury Apartment Building You’ll Love for Decades].
3.3 Worked example: levies and cashflow
Two 2‑bed Mascot apartments at $850,000 with a $680,000 loan (80% LVR), 30‑year P&I at an indicative 6.5%.
- Monthly repayment ≈ $4,305 (illustrative only)
Now compare strata and total monthly outgoings:
-
Older block – no lift, basic garden
- Strata: $950/quarter ≈ $317/month
- Total housing cashflow: $4,622/month (excluding rates, utilities)
-
Newer tower – lift, gym, concierge
- Strata: $2,200/quarter ≈ $733/month
- Total housing cashflow: $5,038/month
Difference: ~$416/month or nearly $5,000/year.
When you stress‑test at rates 3% higher (APRA buffer), and remember mortgage stress is already impacting over 30% of borrowers nationally (Roy Morgan, 2026), that extra $5,000 per year matters.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do banks blacklist specific Mascot buildings?▾
Are older Mascot apartments always easier to finance?▾
Should I avoid all new Mascot towers because of defects?▾
How do strata levies affect my borrowing power?▾
Is it better to buy a cheaper new unit or a smaller old one in Mascot?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.