Article
Postcode Policy Exceptions: Using Local Broker Insight To Unlock Approvals
Many postcodes are on bank “high‑risk” lists, but a good local broker often knows which lenders will bend their postcode rules—and exactly what evidence they need. This guide shows how postcode policy really works, when exceptions are realistic, and the steps you can take this week.
Key Takeaway
This article explains how Australian lenders use postcode risk policies to cap LVRs or decline loans, and how a skilled local broker can often secure postcode exceptions when risk is mispriced. It outlines common high‑risk postcode triggers, such as high‑rise oversupply and single‑industry towns, and notes that lenders typically cap LVRs at 70–80% in these areas. It concludes with actionable steps borrowers can take this week to test broker expertise, target flexible lenders, and assemble evidence to improve approval odds.
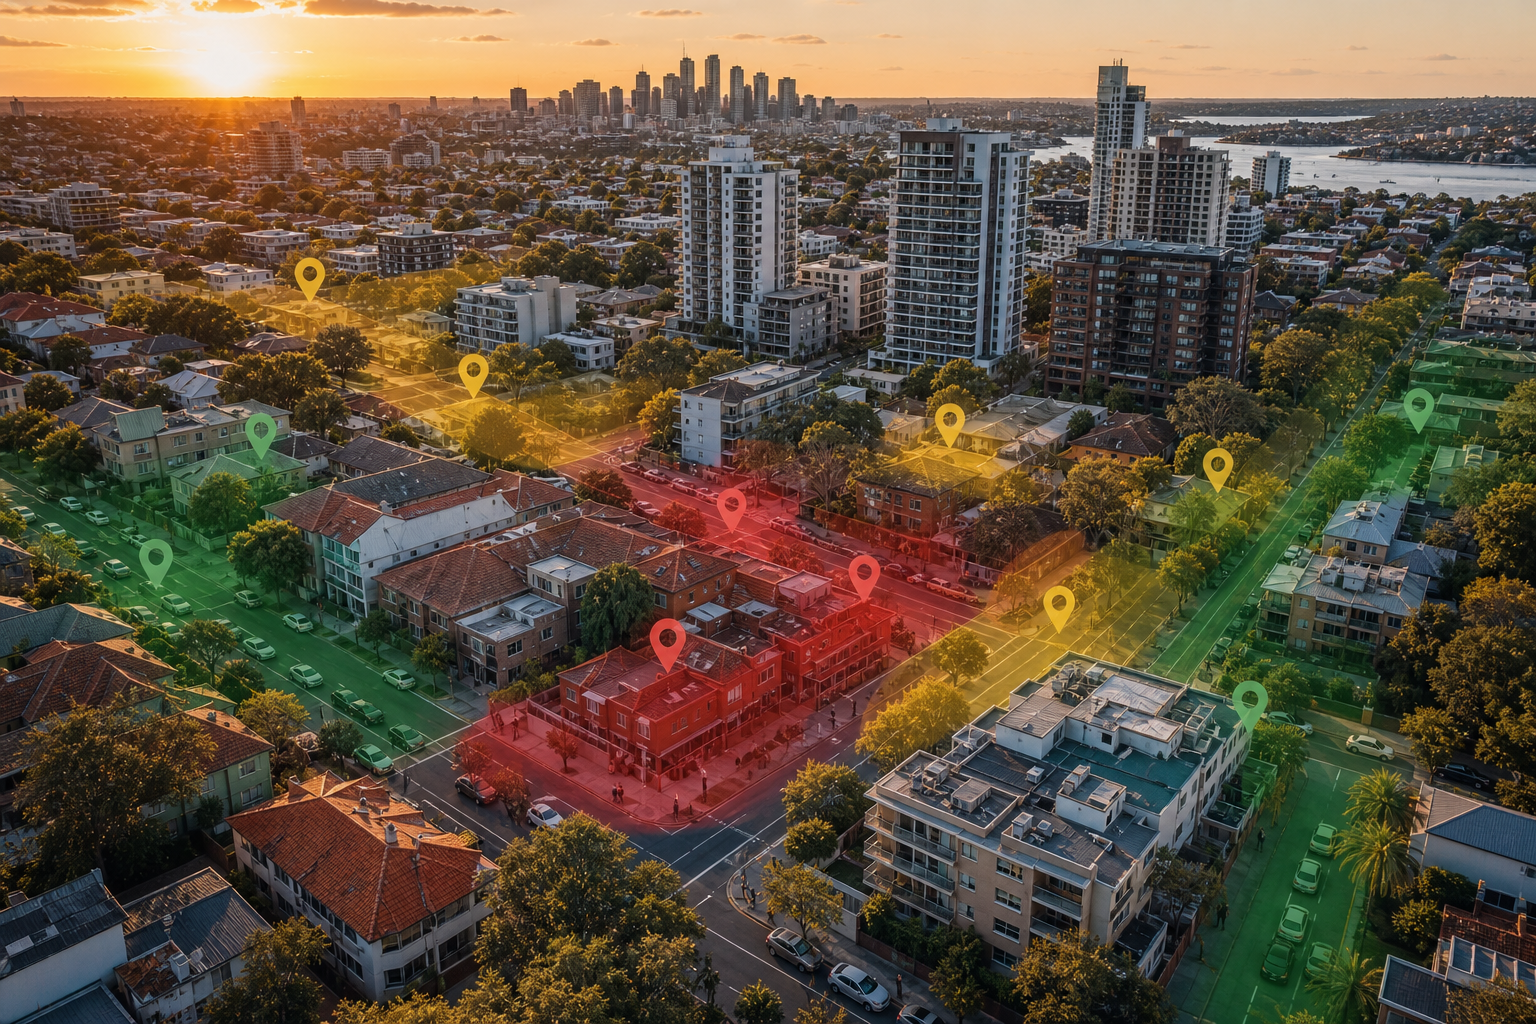
Buying or refinancing in a “red flag” suburb doesn’t always mean a hard no from the banks.
Australian lenders use postcode risk lists to quietly cap borrowing power or decline loans. But those lists are blunt tools. A good local broker often knows which lenders bend their postcode rules – and exactly what it takes to convince them.
This guide explains how postcode policy really works, when exceptions are realistic, and what you can do this week if your dream property is in a high‑risk suburb.
1. What postcode policy exceptions actually are – in plain English
A postcode policy exception is when a lender agrees to approve a loan (or a higher loan‑to‑value ratio) in a suburb they normally treat as higher risk.
Most lenders tag certain postcodes as riskier and respond by:
- Reducing maximum LVR (for example, from 95% to 80% or 70%).
- Refusing LMI over a set LVR (e.g. no LMI above 80% in that postcode).
- Banning certain property types (e.g. studios under 40 m², off‑the‑plan, some high‑rise towers).
- Requiring stronger income or bigger buffers.
An exception is the lender saying, in effect:
“Our default is ‘no’ or ‘lower LVR’ for this postcode – but on the strength of this specific case, we’re comfortable approving it anyway.”
This usually happens when:
- The property is better quality than the suburb’s average.
- The borrower is stronger than the typical risk profile in that area.
- A broker presents hard local evidence that the lender’s risk settings are too blunt for this case.
Not every case gets an exception. But in many borderline postcodes, a well‑argued submission can turn a “probably no” into a “yes, on these terms”.
2. Why lenders mark some postcodes as high risk
Lenders don’t pick on suburbs randomly. Their credit and risk teams build postcode lists based on:
2.1 Common reasons a postcode lands on the “red” list
-
High‑rise oversupply
Lots of similar apartments, heavy investor ownership, incentives to sell. Seen in parts of inner‑city CBDs and big growth corridors. Lenders worry about:- valuation risk (too many near‑identical sales)
- resale risk if the market softens.
-
Single‑industry or mining towns
Where employment, rents and values move with one commodity or one big employer. Lenders saw sharp losses in past mining downturns. -
Very small / remote markets
Low transaction volumes make valuations unreliable. If a lender has to sell, there may be few buyers. -
Known building / construction issues
Cladding, structural defects, major litigation, or a reputation for high special levies. -
Severe flood, bushfire or environmental risk
Especially where insurance is very expensive, limited or repeatedly claimed. -
Socio‑economic stress indicators
High arrears rates, low wage growth, or concentrations of higher‑risk lending from past cycles.
2.2 How that risk shows up in policy
Rather than assess every application from scratch, lenders apply broad postcode rules like:
- Max 70–80% LVR for units in specific postcodes.
- No interest‑only above 80% in these areas.
- No studio units under 40 m² internal in this postcode.
- No high‑density buildings over X apartments in this suburb.
Those rules allow quick decisions, but they also misprice risk for good properties in average postcodes.
That’s where targeted exceptions – often driven by a broker who knows the street, the building and the valuer – can matter.
If you’re unsure whether your area is on a list, a good starting point is asking a broker who actually writes loans there regularly. Our piece on when it’s worth travelling for a local specialist explains how to test that quickly: /insights/travel-for-local-broker-vs-call-centre-broker.
3. How postcode restrictions really bite: LVR, LMI and structure
3.1 The usual caps you’ll see
Below is a simplified view of how one property can attract very different treatment by postcode and lender.
| Scenario | Standard Suburb (indicative) | High‑Risk Postcode (no exception) | High‑Risk with Exception (indicative) |
|---|---|---|---|
| Max LVR, owner‑occupied unit | Up to 95% with LMI | 70–80% (no LMI allowed) | 80–90% (case‑by‑case) |
| Max LVR, investor unit | 90–95% with LMI | 70–80% | 80–85% |
| Acceptable unit size | 35 m²+ (some lenders 30 m²) | 50 m²+ | 40–45 m² with strong profile |
| IO availability | Up to 80–90% | Often banned | Maybe allowed up to 80% |
| Valuation approach | Full/desktop | Often full valuation only | Full valuation with extra commentary |
All figures indicative only. Each lender/LMI insurer runs its own rules.
3.2 The impact on real borrowing power
Assume:
- $800,000 purchase price
- $80,000 savings (10%)
- Strong income and clean credit
In a standard postcode, a lender might allow 90% LVR with LMI:
- Loan: $720,000
- Deposit: $80,000
- Plus costs and LMI (say ~$20,000, added to loan)
In a high‑risk postcode with 80% LVR cap:
- Max loan: $640,000
- Required deposit (excluding costs): $160,000
You now have an $80,000 deposit shortfall – enough to collapse the deal unless:
- You reduce the purchase price
- You access more equity / family help
- Or a broker secures an exception to lift your LVR.
In current conditions, with mortgage stress at the highest level in 18 years and 32.5% of owner‑occupiers “At Risk” according to Roy Morgan’s July 2026 research, lenders are understandably cautious. But they are also open to well‑argued exceptions where the numbers and local story are compelling.
4. When a postcode exception is realistic – and when it’s fantasy
Not every postcode restriction is negotiable. A good broker’s first job is to separate “might bend” from “won’t budge” before wasting time.
4.1 Strong candidates for an exception
You’re more likely to get a postcode exception where:
-
The issue is historic, not current
E.g. rents and values slumped 5–10 years ago, but data now shows stable owner‑occupier demand, low vacancy and rising prices. -
The property is clearly superior to local stock
Larger floor area, better outlook, high owner‑occupier ratio, standout sales evidence. -
The borrower profile is strong
High surplus income, clean credit, low other debts, solid employment or diversified business income. -
The requested LVR is modestly above policy
For example, policy says 80% but you want 85%, not 95%. -
You’re not stacking risk factors
A high‑risk postcode plus:- interest‑only, and
- short employment history, and
- minimal savings
is usually a non‑starter.
-
There’s a strong exit or fallback
Significant liquid buffers, other unencumbered property, or clear downsizing options.
4.2 Cases where lenders rarely move
Exceptions are much harder when:
- The postcode has current, severe distress – high arrears, heavy forced sales.
- There are active cladding or structural issues in the building or precinct.
- The property is a tiny studio or serviced apartment in a flagged high‑density area.
- You’re seeking very high LVR (e.g. 95% with 5% genuine savings).
- The credit score or conduct is weak.
In those cases, a better strategy may be to change the property target rather than beat your head against a brick wall.
Our guide on how good brokers actually pick the right lender walks through how we decide when to fight for an exception vs when to pivot early: /insights/how-brokers-choose-right-lender-for-your-borrowing-story.
5. How a local broker actually secures postcode exceptions
There’s a big difference between a broker who simply “submits and hopes” and one who pre‑negotiates and builds a case.
5.1 The pre‑work: sounding out credit appetite
Before any application goes in, a strong local broker will usually:
- Map your situation – income, debts, buffers, property.
- Short‑list lenders who are:
- active in your postcode;
- open to case‑by‑case exceptions;
- priced reasonably for your profile.
- Call business development managers (BDMs) and, where possible, credit teams to run an anonymised scenario:
- postcode and property type;
- proposed LVR;
- key strengths/risks;
- what extra evidence would make them comfortable.
Think of this as testing the water before you dive. It avoids hard declines on your credit file and shapes the strategy.
5.2 The submission: what a strong exception request contains
When an exception is worth pursuing, the broker’s written submission to the lender will often include:
-
Local market data
Recent comparable sales, vacancy trends, rental yields, time on market, and commentary from trusted data sources. -
Property‑specific strengths
- Larger floor area than typical stock
- Dual aspects or special features
- High owner‑occupier ratio in the building
- Evidence of strong sinking fund and proactive strata
-
Borrower risk profile
Clear explanation of income stability, buffers, conservative internal servicing (we often aim to keep total repayments near ~30–35% of after‑tax income even if the bank allows more – see related guidance in our work with high‑income professionals). -
Mitigants and conditions
For example:- slightly lower LVR than requested;
- principal and interest instead of interest‑only;
- verification of rental demand from a local agent.
-
Valuation support
Where possible, we steer towards valuers who actively work that micro‑market and know its true resale performance.
That sort of submission shows credit you’re not asking them to roll the dice – you’re re‑calibrating their risk lens for a specific, well‑documented case.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 9 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Can I still get 90–95% LVR in a high‑risk postcode?▾
Do all banks use the same postcode blacklist?▾
Will a postcode exception request hurt my credit score if it’s declined?▾
Are non‑bank lenders better for properties in risky postcodes?▾
How often do lenders change their postcode policies?▾
Should I avoid buying in any postcode that a bank restricts?▾
Can a postcode exception overturn a building ban due to cladding or defects?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.