Article
Ring‑Fence ATO Money Without Starving Your Mortgage Offset
How to set up separate tax, GST and PAYG accounts so the ATO is always paid on time, your bank statements look clean, and your home loan offset still pulls its weight.
Key Takeaway
This article explains how Australian self-employed borrowers can ring‑fence ATO money by setting up separate tax, GST and PAYG holding accounts alongside their home loan and offset. With around 28–32% of mortgage holders already ‘At Risk’ of stress (Roy Morgan 2026), mixing tax money with living cash is dangerous. The guide outlines practical account structures, automation rules, and lender‑friendly bank statement habits so readers can avoid surprise ATO debt and protect their mortgage position this week.
Most ATO debt I see didn’t start as tax avoidance. It started as “I’ll fix it next quarter” while GST and PAYG quietly paid the mortgage, the reno and school fees. By the time the accountant runs the numbers, the money’s long gone.
Ring‑fencing ATO money means quarantining every dollar that really belongs to the Tax Office into separate accounts, away from your day‑to‑day spending and your core mortgage buffer. Done properly, it stops ATO debt building up, keeps your bank statements clean for lenders, and still lets you use your offset strategically.
Here’s exactly how to set this up in a week.
What I tell my clients about ATO money and mortgages
The mistake I see most is using one or two accounts for everything: sales, rent, personal spending, GST, PAYG, tax and loan repayments. It feels efficient. It’s actually a slow‑motion train wreck.
What I tell my clients:
- Treat the ATO like a silent business partner who always gets paid first.
- Never rely on home loan redraw as a tax buffer – use a true offset or separate savings account instead.
- Assume your next lender will forensically read your last six months of statements (because they will).
If you only take one idea from this article: set up a separate tax holding structure and automate it. A simple structure, maintained for 6–12 months, will do more for your borrowing power than any glossy business plan.
For context on how BAS, instalments and loan risk tie together, read this alongside /insights/bas-gst-payg-instalments-structure-cashflow-mortgage.
The core structure: four buckets around your home loan
Let’s start with a simple version that works for most sole traders and small companies where the owner has a home loan.
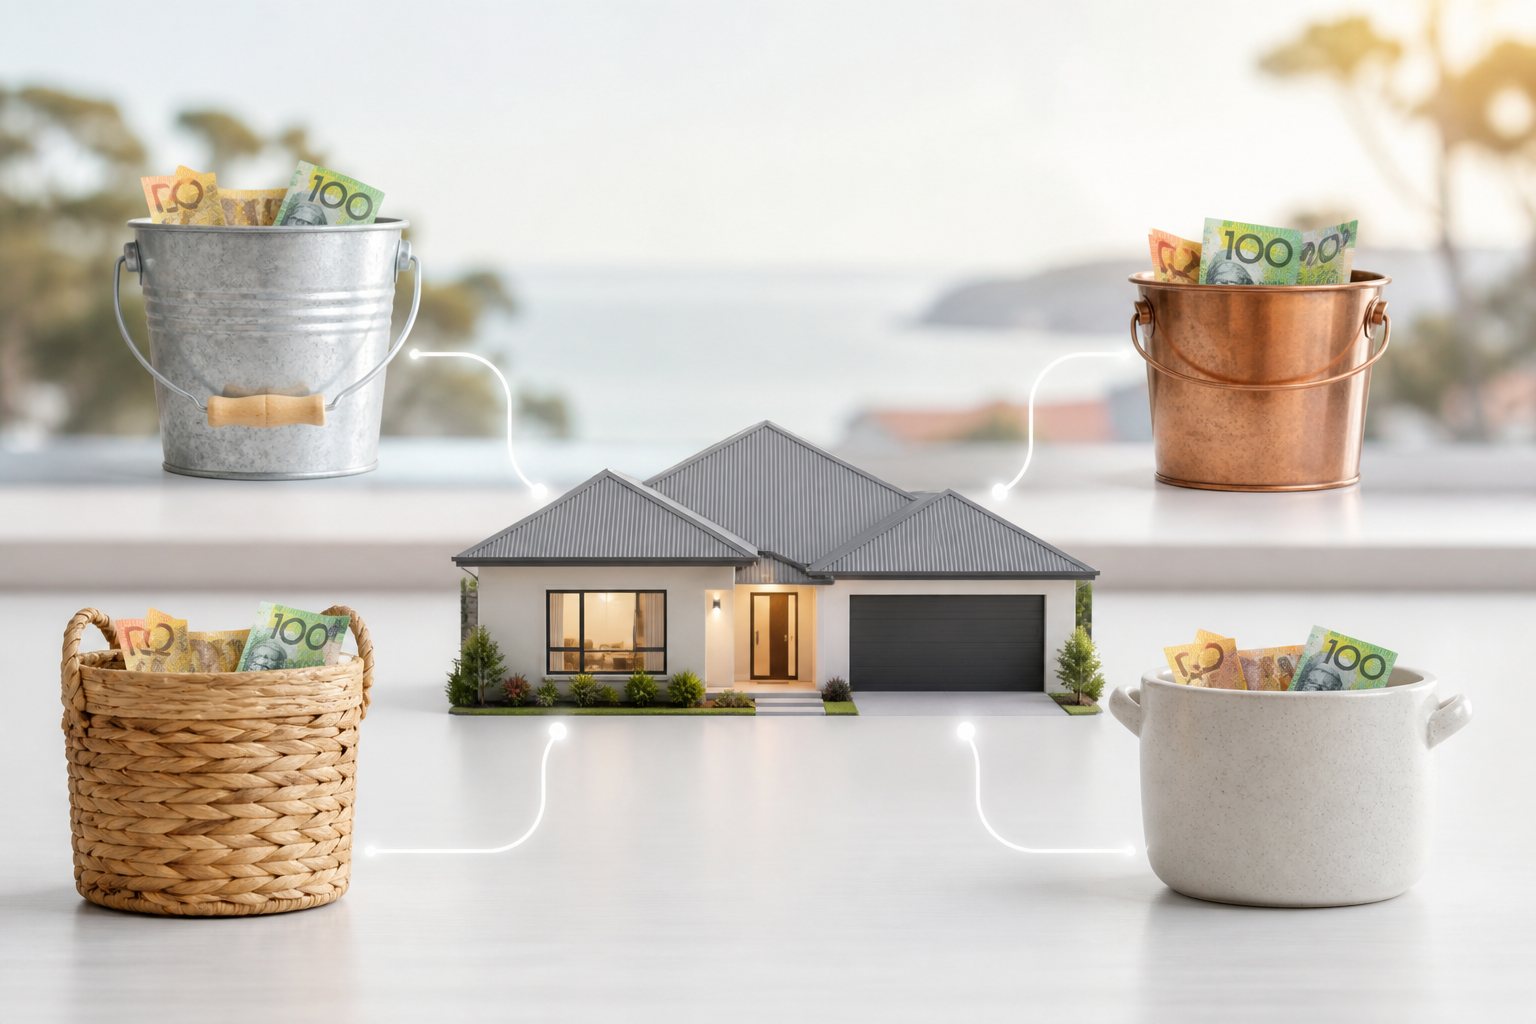
The four essential buckets
You want four distinct categories of money:
- Business trading account – all business income and business expenses.
- ATO holding accounts – separate buckets for GST and income tax/PAYG.
- Personal hub account + primary offset – your “household income” flows here.
- Lifestyle and savings accounts – discretionary spending and non‑ATO goals.
A practical bank setup might look like this (names are for your internal discipline, not the bank’s):
- Account 1 – Business Trading (everyday transaction account in the business name)
- Account 2 – GST Holding (high‑interest saver, business name)
- Account 3 – Tax & PAYG Holding (high‑interest saver, business name)
- Account 4 – Personal Income Hub (everyday personal account)
- Account 5 – Home Loan Offset (linked to your owner‑occupied loan)
- Account 6 – Personal Spending / Joint account (cards, groceries, etc.)
No ATO money should ever sit in Account 6.
Why not just dump tax money in the offset?
Using your home loan offset as a temporary tax buffer can be fine if:
- the purpose is clearly tracked,
- you don’t redraw for business cashflow, and
- you move the tax money out to a separate ATO holding account well before it’s due.
But using redraw or offset as your ongoing business overdraft effectively turns your home loan into a business facility and, as I’ve written elsewhere, that increases risk to the family home and muddies the tax story (see the principle in /insights/keeping-business-and-home-debt-legally-separate-without-hurting-borrowing-power).
The cleaner approach: tax and GST live in dedicated ATO holding accounts. Your offset holds your personal buffer, not the ATO’s money.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Why should I keep ATO money in separate accounts?▾
Can I use my home loan offset as my tax account?▾
Will having ATO debt stop me getting a home loan?▾
How much should I set aside for GST and tax each month?▾
Do lenders look at my business bank accounts or just personal ones?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.