Article
Using Stepping‑Stone Suburbs To Eventually Afford A Bronte Home
A detailed, numbers‑based guide to using stepping‑stone suburbs, rentvesting and timing to move your way into Bronte over 5–15 years without blowing your risk limits.
Key Takeaway
This guide explains how to use stepping-stone suburbs and rentvesting to eventually buy a home in Bronte, combining location choice with conservative borrowing and cash buffer rules. It outlines typical prices, deposit needs, and repayment stress-tests under APRA’s 3% buffer, and shows how to sequence trades over 5–15 years. Readers learn how to choose target suburbs, model equity growth, and set clear risk limits so each move improves their position rather than over-stretching them.
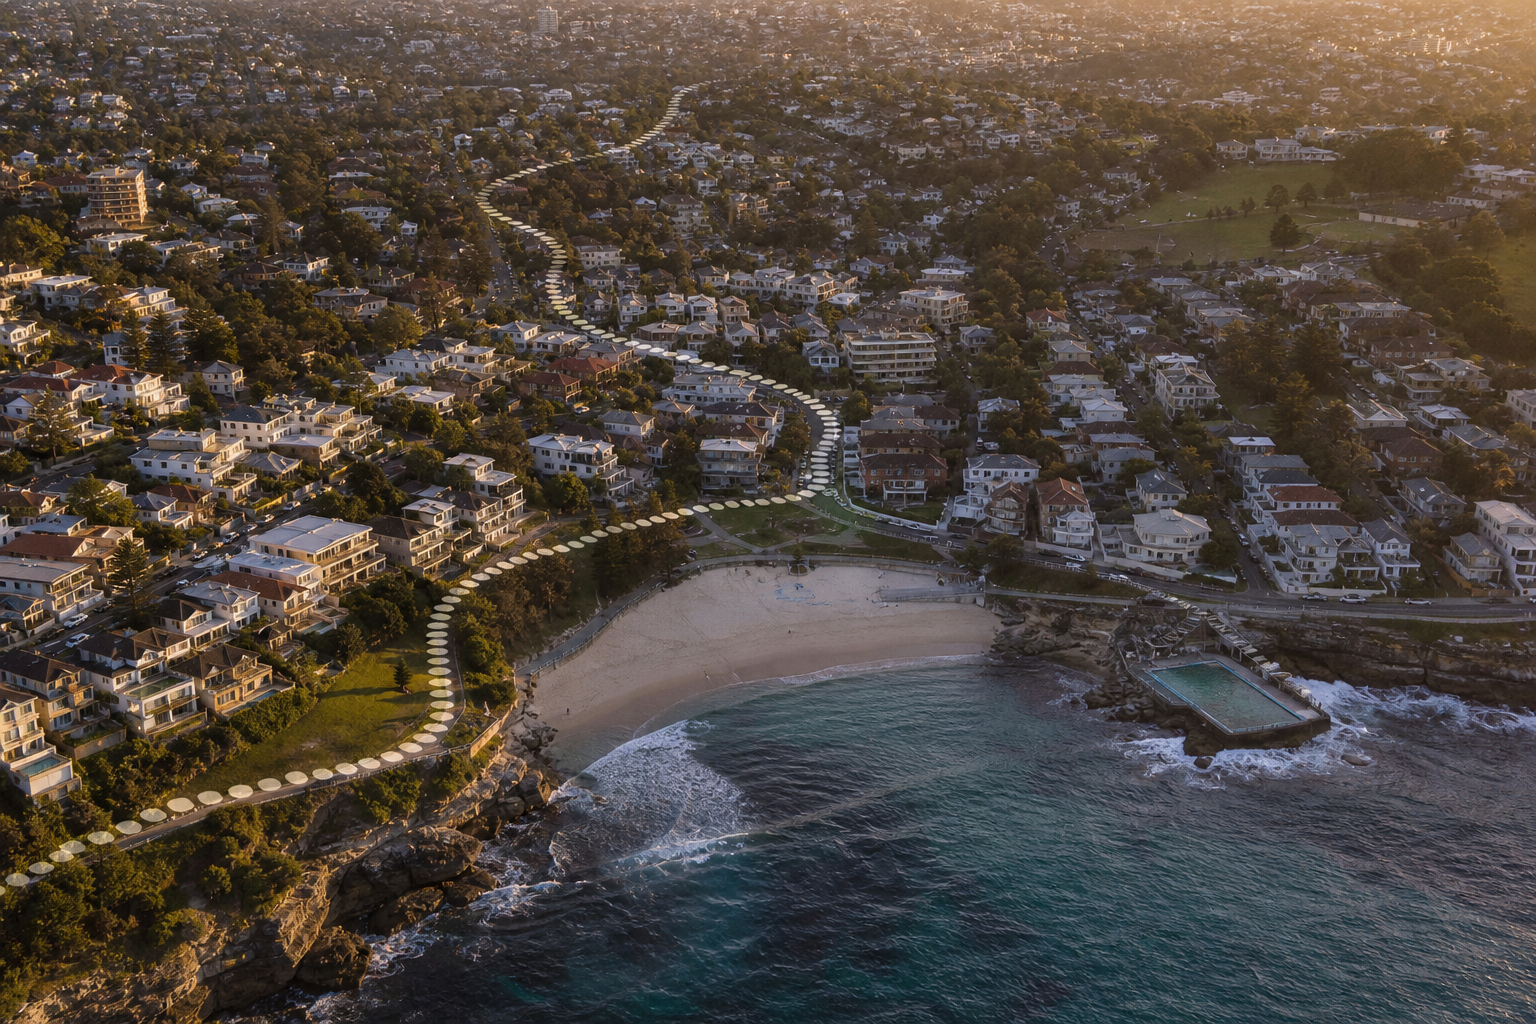
Targeting Bronte as your long‑term home but can’t see how you’ll ever afford it?
A realistic path is to treat Bronte as the end point, and use stepping‑stone suburbs and possibly rentvesting to build equity and income first. You buy where the numbers stack up today, then trade up in 5–15 years as your borrowing power and equity grow – without pushing yourself into unsafe debt.
This guide walks through how to design that path, what numbers to watch, and how to avoid the common traps.
1. What a “Stepping‑Stone Suburb” Strategy Really Is
1.1 Simple definition
A stepping‑stone suburb strategy is when you:
- Buy in a suburb you can afford now (often nearby, or with similar growth drivers to Bronte).
- Use that property to build equity and/or rent income over time.
- Sell, refinance or leverage that equity later to buy in Bronte when your finances, family and work situation can support it.
Sometimes you live in the stepping‑stone property. Sometimes you rentvest – renting in or near Bronte while owning an investment property elsewhere.
1.2 Why Bronte usually needs a multi‑step plan
Even a modest Bronte house can be several million dollars. For many professionals, even with strong income, that means:
- A 20% deposit is hundreds of thousands of dollars.
- APRA’s 3% serviceability buffer means banks test your borrowing at rates far higher than today’s.
- Loan repayments at those levels can easily push you into the 35–40% of after‑tax income danger zone where distress is more likely.
Trying to jump straight into Bronte can therefore:
- Limit your borrowing power.
- Leave you with no cash buffer.
- Make you vulnerable to rate rises or job changes.
Building up in stages can be safer and more realistic.
Action this week: Decide if Bronte is a 5‑year, 10‑year or 15‑year goal. Your timeframe will drive how aggressive you can be with location and leverage.
2. The Key Levers Between You And A Bronte Purchase
2.1 The three numbers that matter most
For almost every Bronte‑focused plan, three levers dominate:
- Equity – value of assets minus debts.
- Borrowing power – how much a bank will lend based on income, expenses and the 3% buffer.
- Risk buffers – cash and capacity to handle shocks.
If any one of those is weak, Bronte stays out of reach.
This is why we emphasise in other pieces that maintaining 6–12 months of essential living costs plus total loan repayments in cash or true offset is a practical safety line for Eastern Suburbs borrowers, especially when debt is high (see the principles we use in /insights/borrowing-power-upgrade-unit-to-semi-terrace-eastern-suburbs and related articles).
2.2 How stepping‑stone suburbs help each lever
A good stepping‑stone choice can:
- Grow equity faster than your savings alone.
- Boost your future borrowing power by showing stable repayment history and, if rented, additional income.
- Let you stay under safe debt ratios, even as prices move.
By contrast, forcing Bronte too early can consume all three: little equity, maxed‑out borrowing, and no buffer.
2.3 Where this fits in your broader strategy
This article sits alongside:
- A numbers‑first view of Bronte affordability in Can You Afford to Buy a Home in Bronte? A Practical Numbers Walkthrough.
- Risk analysis in Stretching from Bronte Apartment to House: Borrowing Limits and Risks.
- Auction and valuation nuances in The Quiet Advantages a Bronte Broker Knows Before Auction Day.
Use those together as your Bronte “playbook”.
3. Mapping The Bronte Price Gap You’re Trying To Bridge
3.1 Indicative price ladder
Exact figures move month by month, but as a broad, illustrative ladder:
| Property type (indicative) | Approx. price band (Bronte & surrounds) |
|---|---|
| Older 1‑bed unit (non‑view) | $900k – $1.2m |
| 2‑bed unit Bronte/Clovelly/Waverley | $1.5m – $2.2m |
| 3‑bed semi / small townhouse nearby | $2.5m – $3.5m+ |
| Freestanding family home Bronte | $4m – $6m+ |
These are order‑of‑magnitude ranges only, not valuations or advice. Always check current sales data.
Your “gap” is the difference between what you can afford now and the property you want in Bronte.
3.2 Worked example: the couple who want a Bronte family home
Assume:
- Combined after‑tax income: $260,000 p.a.
- Savings: $250,000.
- No other debts.
You want a $4.0m Bronte house.
- 20% deposit + costs (~6% stamp duty/legals etc) ≈ $1.04m.
- With $250k saved, you’re short about $790k (ignoring options like parental support).
- A $3.2m loan at, say, 6.0% P&I over 30 years is about $19,180 per month.
- That’s nearly 90% of take‑home pay, far beyond any safe range.
Even if some of those numbers flex, your borrowing capacity and cashflow are the real problem, not just the deposit.
A stepping‑stone strategy asks a different question: “What can you safely buy today that helps close that gap over time?”
4. Choosing Stepping‑Stone Suburbs Around Bronte
4.1 What makes a good stepping‑stone suburb?
You’re looking for “Bronte‑adjacent” characteristics without the full Bronte price tag. In practice:
- Transport and access: Reasonable commute to the CBD and key employment hubs.
- Lifestyle drivers: Cafés, beaches, parks, village feel – the things that underpin demand.
- School catchments and amenity: Often a major driver in Eastern Suburbs purchases (see /insights/financing-move-key-school-zones-bronte).
- Diverse buyer pool: Strong owner‑occupier demand plus rental demand.
- Value relative to Bronte: Cheaper per square metre, but with similar long‑term demand drivers.
4.2 Types of stepping‑stone locations for a Bronte goal
Broadly, buyers considering Bronte usually look at three “rings” of options:
- Inner ring: Bronte‑adjacent suburbs like Waverley, Clovelly, Queens Park, Randwick pockets.
- Middle ring: Still Eastern Suburbs, but further from the beach – e.g. Kensington, Kingsford, Maroubra, parts of Coogee if Bronte is the ultimate stretch.
- Outer ring / other corridors: Well‑connected suburbs on the Illawarra or Inner West lines where you can buy more space or yield.
The right ring depends on your income, family plans, and risk appetite.
4.3 Comparing example stepping‑stone profiles
Below is a hypothetical comparison to illustrate trade‑offs. It’s not a suburb recommendation.
| Option | Example area (illustrative only) | Typical buy‑in (2‑bed unit) | Yield profile | Pros | Cons |
|---|---|---|---|---|---|
| A | Waverley / Clovelly fringe | $1.5m – $1.9m | Lower (2.5–3.0%) | Strong owner‑occupier demand, similar to Bronte, easier later trade‑up | High entry cost, lower rental support on cashflow |
| B | Randwick / Queens Park fringe | $1.2m – $1.6m | Moderate (3–3.5%) | Good mix of families and professionals, strong rental market | Not quite “walk to Bronte Beach” for most properties |
| C | Kensington / Kingsford | $900k – $1.3m | Higher (3.5–4%+) | Lower price point, student + professional rental demand | Different demographic / feel vs Bronte, more supply risk |
Again, treat this as directional only; real numbers vary street by street.
Action this week: List 3–5 candidate suburbs with: (1) your approximate budget; (2) whether you’d live there or rent it out; (3) your best guess of likely hold period (e.g. 7–10 years).
5. Live In It Or Rentvest? Two Main Stepping‑Stone Models
5.1 Owner‑occupier first, then trade up
Here you buy a home in a stepping‑stone suburb and live there. Later, you either:
- Sell it to help fund the Bronte upgrade, or
- Keep it and convert it to an investment when you move to Bronte.
Pros:
- Emotional benefit: stability, control over your home.
- Possible main residence CGT exemption for some or all of the ownership period.
- Banks often like seeing stable living arrangements.
Cons:
- You might still be commuting to Bronte amenities.
- If the property becomes an investment later, you need to be careful with loan purpose and deductibility – interest on the original home loan is non‑deductible even if the property later becomes a rental; deductibility is based on original use of funds (see /insights/six-year-rule-main-residence-exemption-geared-properties).
5.2 Rentvesting to stay near Bronte now
With rentvesting, you:
- Rent in or near Bronte (or another lifestyle suburb you value now).
- Buy an investment‑grade property where the numbers work – this could be in the Eastern Suburbs or elsewhere.
Pros:
- You experience the lifestyle now.
- Your purchase can be chosen purely on investment metrics.
- Potentially higher yields or better growth drivers.
Cons:
- Emotional trade‑off: you don’t “own” where you live.
- You miss some main residence CGT benefits on the stepping‑stone property.
- You must be disciplined about separating investment and personal debt, so you don’t blur tax outcomes.
In practice, many Bronte‑oriented professionals use a hybrid: rent in or close to Bronte for a few years, then shift to owner‑occupier stepping‑stones when children and schools become more central.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 9 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How many properties do I need before I can buy in Bronte?▾
Is rentvesting the best way to eventually buy in Bronte?▾
What if Bronte prices grow faster than my stepping‑stone suburb?▾
How big should my buffer be if I’m self‑employed and aiming for Bronte?▾
Should I focus on paying down my stepping‑stone loan or saving for Bronte?▾
Can future tax changes ruin a Bronte stepping‑stone strategy?▾
Can parental guarantees replace the need for stepping‑stone suburbs?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.