Article
Changing Investment Loan Repayments: What Actually Changes For Tax
Changing investment loan repayments can change cashflow and future deductions, but the ATO mainly cares about how you use the borrowed money, not whether you pay IO or P&I.
Key Takeaway
Changing investment loan repayments from interest-only to principal-and-interest rarely changes immediate interest deductibility; the ATO focuses on how borrowed funds are used, not repayment style. Under Australian rules, any redraw for private purposes instantly makes that portion of the loan non-deductible, and mixed-use splits create ongoing apportionment headaches. With negative gearing reforms from 1 July 2027 reducing wage-offset benefits, investors should prioritise clean loan purposes, avoid using redraw for private spending, and plan IO-to-P&I shifts around cashflow, not tax hopes.
Changing your investment loan from interest‑only (IO) to principal‑and‑interest (P&I), or upping repayments, usually doesn’t change what’s deductible today.
For the ATO, the core rule is: interest is deductible to the extent the borrowed money is used to produce assessable income, not whether you pay IO vs P&I or how fast you pay it down.
Where people get hurt is when they change how they use the loan – redraws, offsets, and messy splits.
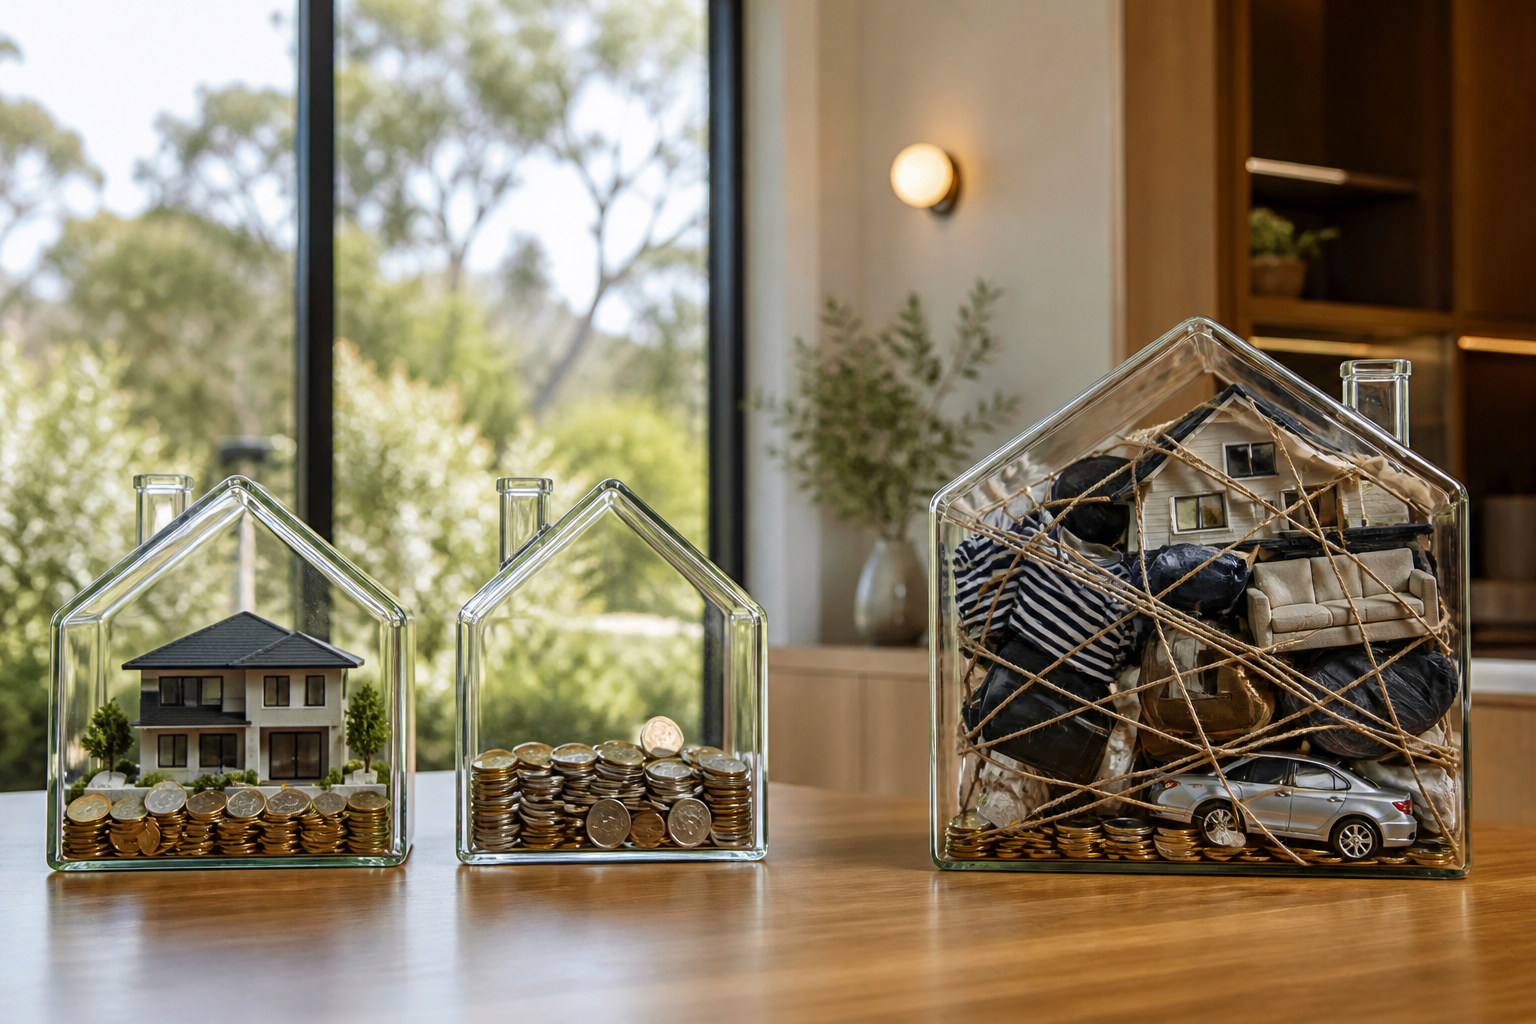
What the ATO actually cares about (not your repayment type)
From a tax perspective, three things matter:
- Purpose of the borrowing – what the funds were used for.
- Tracing – whether you can show that purpose clearly.
- Changes of use – redraws, refinances, or mixed private/investment use.
Whether you pay IO or P&I is mostly irrelevant to deductibility.
If the entire loan funded an investment property deposit and costs, the interest on that balance is generally deductible. If part of it funded a car or holiday, that part is not.
This is why keeping separate loan splits for each purpose is so powerful. It aligns with the principle that purpose, not security, drives deductibility (see also /insights/using-equity-release-next-investment-without-breaking-ato-rules).
IO vs P&I: does switching change your deduction?
On its own, no.
- Interest portion: stays deductible to the extent the loan is investment‑purpose.
- Principal portion: never deductible – it’s just returning capital.
Change from IO to P&I and you usually:
- Pay less interest each year over time (so smaller deductions).
- Build equity faster.
That’s a cashflow and strategy decision, not a tax win or loss. If you’re weighing up timing, see how this article connects to /insights/refinance-investment-loan-interest-only-to-principal-and-interest.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Does switching from interest-only to principal-and-interest change what I can claim?▾
Is it better for tax to put extra cash in redraw or in an offset?▾
Can I refinance my home and investment loans into one to get a better rate?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.