Article
Structuring Equity: Cross‑Collateral vs Standalone to De‑Risk Property
How to use equity from one property to support another without putting your whole portfolio at risk. Clear explanation of cross‑collateralisation vs standalone loans, worked numbers, and a one‑week action plan.
Key Takeaway
Using equity from one property to de-risk another works best with standalone loans rather than cross-collateralisation, because one-loan-per-property structures ring‑fence risk and keep refinancing or selling flexible. In an environment where Roy Morgan reports 32.5% of mortgage holders ‘At Risk’ of stress in 2026, avoiding structures that let one distressed asset endanger an entire portfolio is critical. Investors should prioritise a standalone security structure with purpose-based loan splits and conservative LVRs before choosing specific lenders or products.
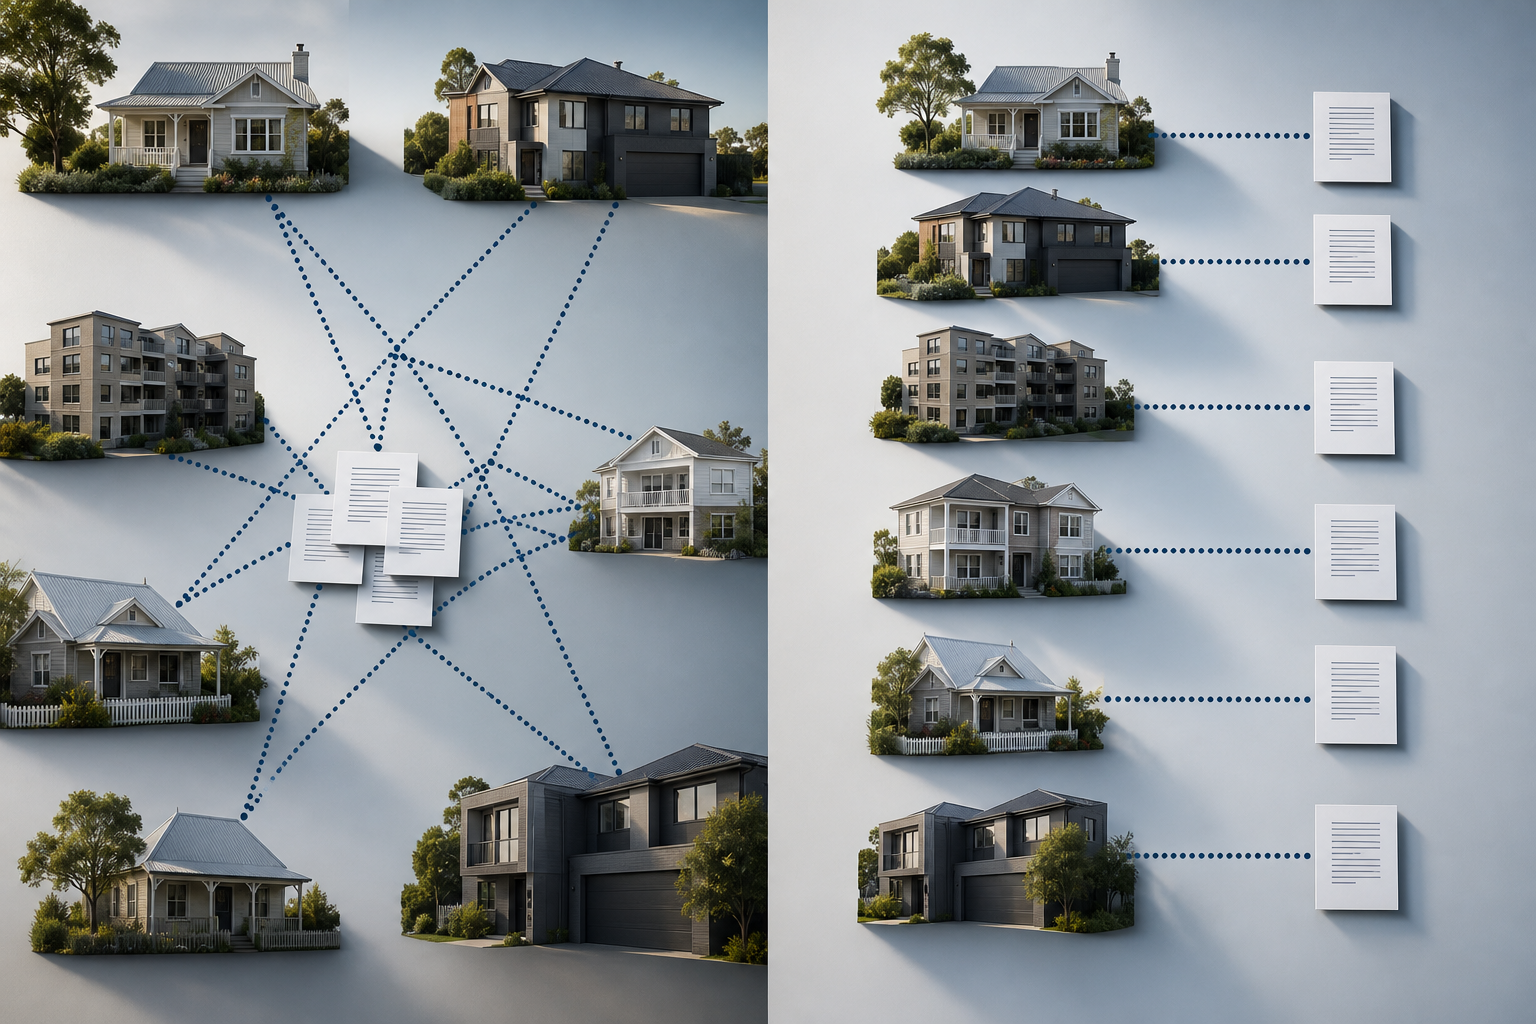
Using equity from one property to reduce the LVR and risk on another is smart – if you get the loan structure right. In most portfolios, that means favouring standalone loans (one primary loan per property) over cross‑collateralised loans where multiple properties secure one debt.
Here’s the short version: use equity, but keep securities clean. Let one property help, without giving a bank control over all of them.
Cross‑collateral vs standalone: what’s the real difference?
Quick definitions
- Cross‑collateralisation: two or more properties secure one or more loans together. The lender looks at the combined LVR and can require valuations or changes across the lot.
- Standalone structure: each property has its own primary loan, secured only by that property, with separate equity‑release splits where you’ve used another property for a deposit or costs.
The money can flow the same way in both. The difference is who controls what if something goes wrong or you want to sell.
Why it matters more in 2026–27
With the cash rate around 4.35% and Roy Morgan estimating over 30% of borrowers are ‘At Risk’ of mortgage stress, structures that let one distressed asset drag others down are dangerous. Cross‑collateralisation does exactly that.
Side‑by‑side comparison
| Feature / risk point | Cross‑collateral loans | Standalone structure (one loan per property) |
|---|---|---|
| Who controls multiple properties? | One lender controls the whole group | Each property mainly tied to its own loan |
| Selling one property | Bank can revalue all, demand extra debt reduction | You can usually sell and adjust just that property’s loan |
| Using equity to reduce LVR elsewhere | Uses portfolio LVR, can trap equity at one lender | Equity released via clean splits, can refinance selectively |
| Impact if one property underperforms | Whole portfolio can be dragged into negotiations | Risk is ring‑fenced to that property and its splits |
| Tax record‑keeping | Messy, especially with mixed purposes | Cleaner – purpose‑based splits per property |
| Fit with multi‑lender strategy | Hard – one lender ‘owns’ everything | Ideal – simple to allocate each property to a lender |
For portfolio risk management, standalone almost always wins.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is cross-collateralisation always bad for property investors?▾
Can I use equity from my home to reduce LMI on an investment without cross-collateralising?▾
How do I know if my loans are cross-collateralised?▾
Is it expensive to unwind cross-collateralised loans?▾
Should I spread my properties across multiple lenders at once?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.