Article
How Vacancy Rates, Rent Caps and Tenant Laws Shape Your Loan
Vacancy rates, rent caps and tenant protections directly shape how banks assess risk, rent and borrowing power. Here’s how to read local rental laws the way lenders do.
Key Takeaway
Vacancy rates, rent caps and tenant protections affect Australian borrowers because lenders use them to assess rental risk, shade rent and set loan-to-value ratios. Areas with vacancy above roughly 3% or strong rent-control rules can see lower assessed rent and tighter LVRs, reducing borrowing power by tens of thousands of dollars. Investors and small businesses should check local rental laws, stress-test cashflow and align loan structure with realistic rent and vacancy assumptions before committing to a purchase or refinance.
Vacancy rates, rent caps and tenant protections matter because lenders use them to judge how reliable your rent is, how quickly it can grow, and how hard it will be to cover the loan if something goes wrong. Higher vacancies or strict rent/tenant rules usually mean more conservative rental income, lower borrowing power and, sometimes, tougher loan terms.
Fast answer:
- Low vacancy (under ~2%) generally helps borrowing because rent is seen as secure.
- Strong rent caps or tenant protections can reduce the rent banks will count.
- Together, they influence LVRs, interest margins and how much buffer you really need.
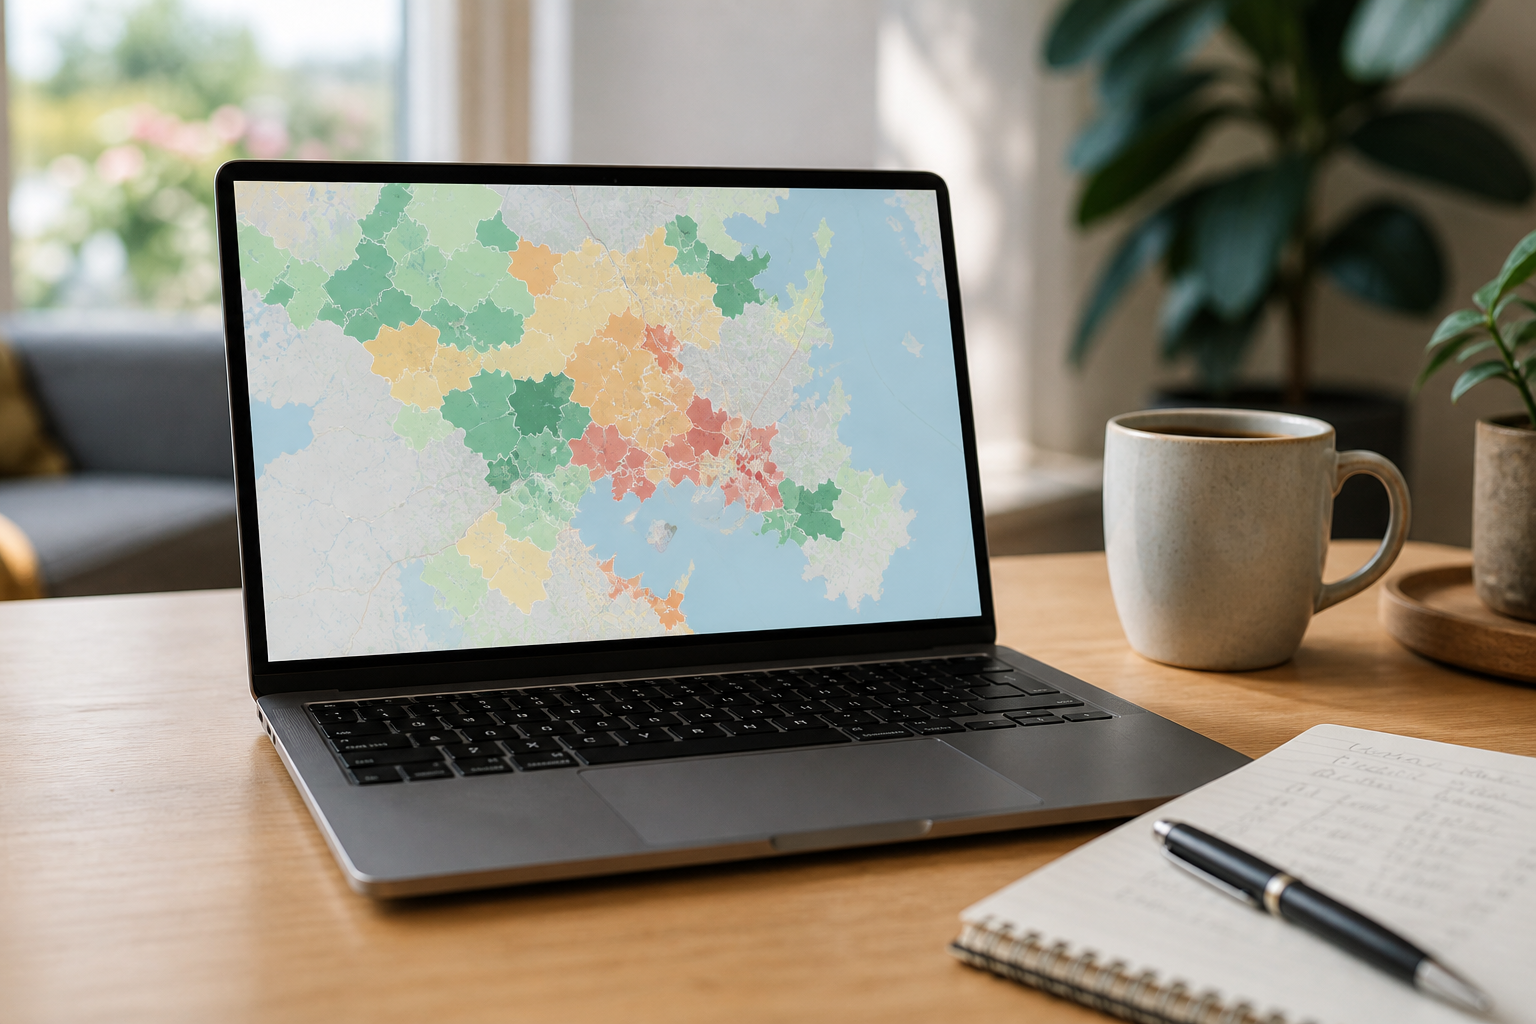
1. Vacancy rates: the first filter lenders use
Vacancy rate is the share of rental properties sitting empty. For lenders, it’s a quick read on how easily your property can be re‑let.
As a rough rule of thumb:
- Under 1.5% – super tight; rent is sticky, re‑letting is fast.
- 1.5–3% – balanced; normal assumptions apply.
- Above 3% – soft; lenders start to assume longer vacancies.
Lenders already shade rent (often using 70–80% of gross rent) to allow for costs and downtime. In higher‑vacancy suburbs, they may go more conservative again or be picky about property type.
Example: how vacancy can quietly cut borrowing
Say a lender normally uses 80% of rent.
- Market rent: $650 per week ($33,800 p.a.)
- Standard shading (80%): $27,040 used in servicing.
If the local vacancy rate is trending high and stock is sitting longer, a cautious lender might only count 70%:
- 70% of rent: $23,660
That $3,380 annual difference can trim borrowing power by tens of thousands of dollars, especially once APRA’s 3% serviceability buffer is applied.
For investors building a portfolio, combine this with how banks already weigh yield vs risk in different suburbs – see /insights/high-yield-vs-blue-chip-suburbs-rent-risk-borrowing-power.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 5 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do banks actually look at suburb-level vacancy rates when assessing my loan?▾
How do rent caps affect my ability to refinance an investment property?▾
Are stronger tenant protections always bad for landlords when borrowing?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.