Article
Have You Outgrown Your Mortgage Broker? A Guide For Property Investors
How to know when your growing property portfolio has outpaced your current broker, and whether to switch or add a specialist so your finance structure doesn’t quietly cap your future growth.
Key Takeaway
Property investors should consider switching mortgage brokers or adding a specialist once they move beyond 1–2 properties, face lender policy walls, or have cross‑collateralised loans limiting flexibility. With around 32.5% of Australian borrowers ‘At Risk’ of mortgage stress (Roy Morgan, July 2026), poor structures can sharply increase risk as portfolios grow. Investors can act within a week by auditing their current loans, stress‑testing cashflow, and interviewing specialist brokers using structured questions.
Investors should consider switching mortgage brokers – or adding a specialist alongside their current broker – once their portfolio moves beyond simple, single‑property lending into more complex territory. Common trigger points include owning multiple properties, hitting lender policy walls, seeing deals fall over late in the process, or sensing your broker is reacting to your ideas rather than proactively shaping a strategy. At that point, the wrong structure can quietly cap your future borrowing and increase risk.
This guide walks through clear warning signs, what a property‑portfolio specialist actually does differently, and a practical one‑week plan to review your current broker and, if needed, move or add a specialist without blowing up existing relationships.
1. Why the “right broker” changes as your portfolio grows
For a first home or single investment, a competent generalist broker can often do a fine job: find a decent rate, navigate policy, get the loan approved.
Once you’re juggling multiple loans, rising rates and tighter tax rules, the game changes. The question shifts from “Can I get this loan?” to:
- “Does this structure protect my borrowing power for the next 5–10 years?”
- “Can I safely de‑gear or sell one property without disturbing the whole portfolio?”
- “How does this loan choice interact with negative gearing changes, cashflow and tax?”
Post‑COVID credit markets and APRA’s settings mean the RBA now needs higher cash rates to slow the economy (RBA Bulletin, Feb 2026). At the same time, Roy Morgan’s July 2026 research shows about 32.5% of owner‑occupier borrowers are ‘At Risk’ of stress. When rates and rules are moving, the cost of an average broker becomes much higher for investors.
A property‑portfolio specialist broker designs around:
- Stand‑alone securities (one primary loan per property, minimal cross‑collateralisation).
- Strong tax tracing: clearly labelled splits for deposits, costs and renovations.
- 3%+ rate stress tests, conservative rent assumptions and vacancy buffers.
- Per‑property cashflow, not just “portfolio average” numbers.
If your current broker isn’t working at that level, you’ve probably outgrown them.
2. Clear signs you’ve outgrown your current broker
2.1 Portfolio complexity triggers
You should at least review your broker fit if any of these are true:
- You hold (or are about to hold) three or more properties.
- Total debt is pushing 5–7x gross household income, especially in prestige suburbs like Rose Bay where 6–7x can be a sensible cap.
- You’ve used your home equity to fund deposits and the loans are now tangled across multiple securities.
- You’re self‑employed, have trust/company structures or SMSF borrowing.
- You’re planning post‑2027 purchases that will sit under tighter negative gearing rules.
In these situations, structure matters as much as rate. A specialist or more strategic broker can become as important as a good accountant.
For more on the generalist vs specialist decision, see Deciding Between a Specialist or Generalist Mortgage Broker in Rose Bay.
2.2 Structural red flags in your loans
Pull up your current loan statements and look for these warning signs:
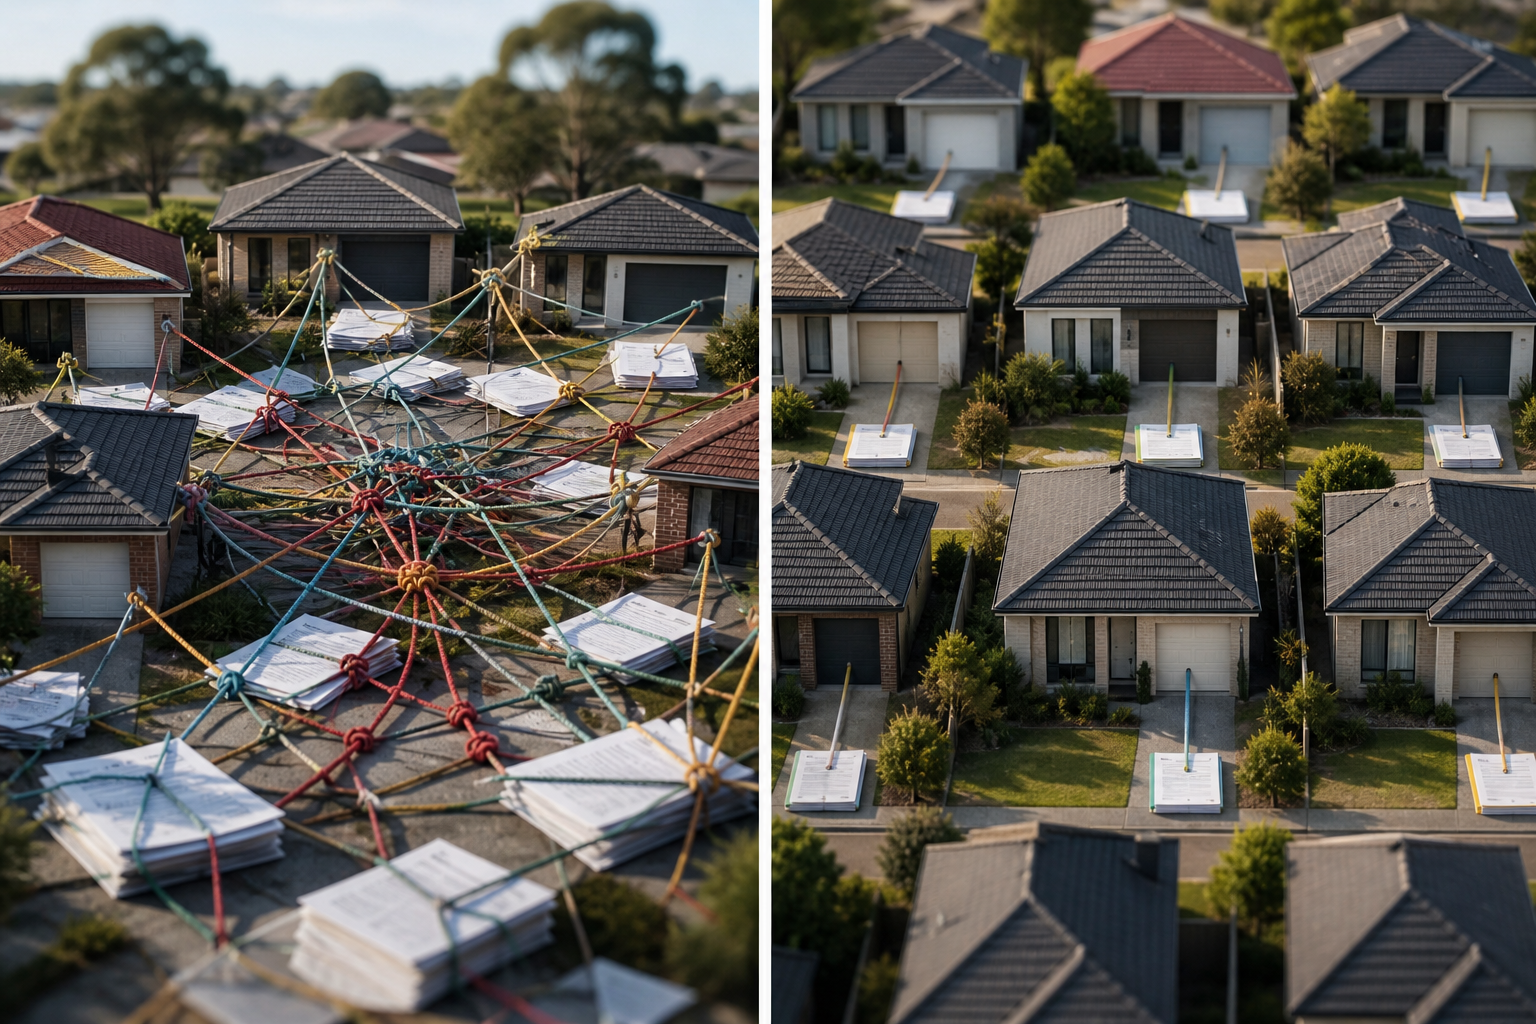
- Cross‑collateralisation everywhere: multiple properties tied into a single umbrella facility. This can block sales, refinances and equity release.
- One giant mixed‑purpose loan that funded both personal and investment costs, making tax deductions messy and future restructuring hard.
- No clear per‑property splits: you can’t easily see the loan amount, rate and repayments tied to each property.
- Offset and redraw used interchangeably without regard for tax tracing, particularly where investment and personal cash is mixed.
Existing knowledge in this hub shows that stand‑alone securities with one primary loan per property and minimal cross‑collateralisation make future de‑gearing, refinancing and targeted sales far easier (see /insights/how-much-equity-safely-release-investment-property-australia and /insights/red-flags-over-gearing-property-portfolio-de-risk-gently).
If your file looks like spaghetti, it’s a sign your broker hasn’t been structuring with future moves in mind.
2.3 Service and strategy red flags
Red flags that your broker isn’t thinking like a portfolio adviser:
- They only contact you when your fixed rate is ending, not annually.
- Every discussion is about the next purchase, never about your endgame or exit options.
- They’ve never run a full 3% interest‑rate stress test of your portfolio.
- They can’t clearly explain why each loan is IO vs P&I, or how that lines up with property roles (core hold vs probation asset).
- They dismiss tax, legal or estate‑planning questions as “your accountant’s job” without at least framing the finance implications.
A good portfolio broker works in concert with your accountant and planner, not in a silo.
3. What a property‑portfolio specialist broker actually does differently
3.1 From “rate shopper” to portfolio architect
A specialist broker doesn’t start with “Which bank has the best rate?”
They start with a blueprint:
- One primary loan per property, with internal splits by purpose.
- Separate equity‑release splits for each deposit and cost, to preserve tax tracing.
- Minimal cross‑collateralisation, so each property can be sold or refinanced on its own.
- Property‑by‑property roles: which to hold long‑term, which are on probation, and what that means for IO vs P&I.
- Clear cashflow stress testing: at least a 3% rate rise, flat or slightly lower rents, and three months’ vacancy per investment.
Only once that’s mapped do they select lenders and products – echoing the principle that structure should precede lender choice (see /insights/switch-big-4-to-boutique-lender-rose-bay).
3.2 Dealing with post‑2027 negative gearing changes
With negative gearing reforms from 1 July 2027, many investors will hold a mix of:
- Grandfathered properties: full wage‑offset negative gearing still available.
- Post‑reform properties: quarantined rental losses, where decisions must stand on pre‑tax cashflow.
A portfolio broker helps you:
- Track each property separately for tax and strategy.
- Prioritise P&I and debt reduction on non‑deductible or weaker‑performing assets.
- Model new purchases assuming no wage‑offset negative gearing and a 3% rate rise.
This aligns with our hub’s guidance that post‑2027 established residential investments should be modelled on pre‑tax cashflow with no wage‑offset benefit.
3.3 Risk management in an elevated‑rate world
The RBA’s August 2026 Statement on Monetary Policy notes that financial conditions remain tight, with higher scheduled mortgage payments and softer housing sentiment. At the same time, Roy Morgan reports over one in five borrowers are ‘Extremely At Risk’.
A portfolio broker should therefore:
- Run annual stress tests across your portfolio.
- Cap combined home + investment repayments at roughly 30–35% of after‑tax income when modelled at 3% above current rates (for high‑income geared investors).
- Maintain buffers: offsets, undrawn limits or clear access to low‑cost funds.
If your broker isn’t doing this, your risk settings may not match today’s environment.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How many properties should I own before using a specialist mortgage broker?▾
Do I have to refinance everything if I change mortgage brokers?▾
Is it worth switching brokers just for a better rate on investment loans?▾
What are the risks of staying with a generalist broker as my portfolio grows?▾
Can I use different brokers for my home and my investment properties?▾
How often should an investment‑focused broker review my portfolio?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.