Article
Financing Company Title and Strata Quirks Around Green Square
A plain‑English guide to financing company title and quirky strata apartments around Green Square, Zetland and the inner south, with lender red flags, deposit rules and one‑week action steps.
Key Takeaway
This guide explains how to finance company title and quirky strata apartments in Sydney’s inner south, where lenders often cap LVRs below standard loans and scrutinise by‑laws and building issues more closely. It outlines key risks like oversupply, small sizes, and unusual usage that can reduce valuations and borrowing capacity. Readers learn practical steps to confirm lender appetite, structure deposits, and stress‑test repayments so they can act on a purchase or refinance within a week.
Buying or refinancing around Green Square, Zetland, Rosebery or Alexandria gets more complicated when you mix in company title or quirky strata by‑laws. These properties are often still financeable, but banks put them in a higher‑risk bucket, which means tighter loan‑to‑value ratios (LVRs), more conservative valuations and more questions before approval.
In practical terms, if you’re looking at a company title unit or a strata apartment with unusual rules or building issues, you need to check financeability before you bid or waive cooling‑off. That means understanding how lenders see title type, by‑laws, usage and the wider inner‑south risk factors like oversupply and investor ratios.
1. Company title vs strata: what you’re actually buying
1.1 Quick definitions
Strata title
- You own a defined lot (your unit) plus a share of common property.
- You have a separate title at NSW Land Registry.
- The owners corporation runs the building; decisions are by majority vote.
Company title
- A company owns the building; you buy shares in that company.
- Your shares give you an exclusive right to occupy a particular unit.
- There’s no separate Torrens or strata title for your unit.
- The board can often approve or refuse buyers, tenants or renovations.
Most Sydney apartments are strata. Company title is more common in older blocks in the east and pockets of the inner ring, including some small, older buildings not far from Green Square.
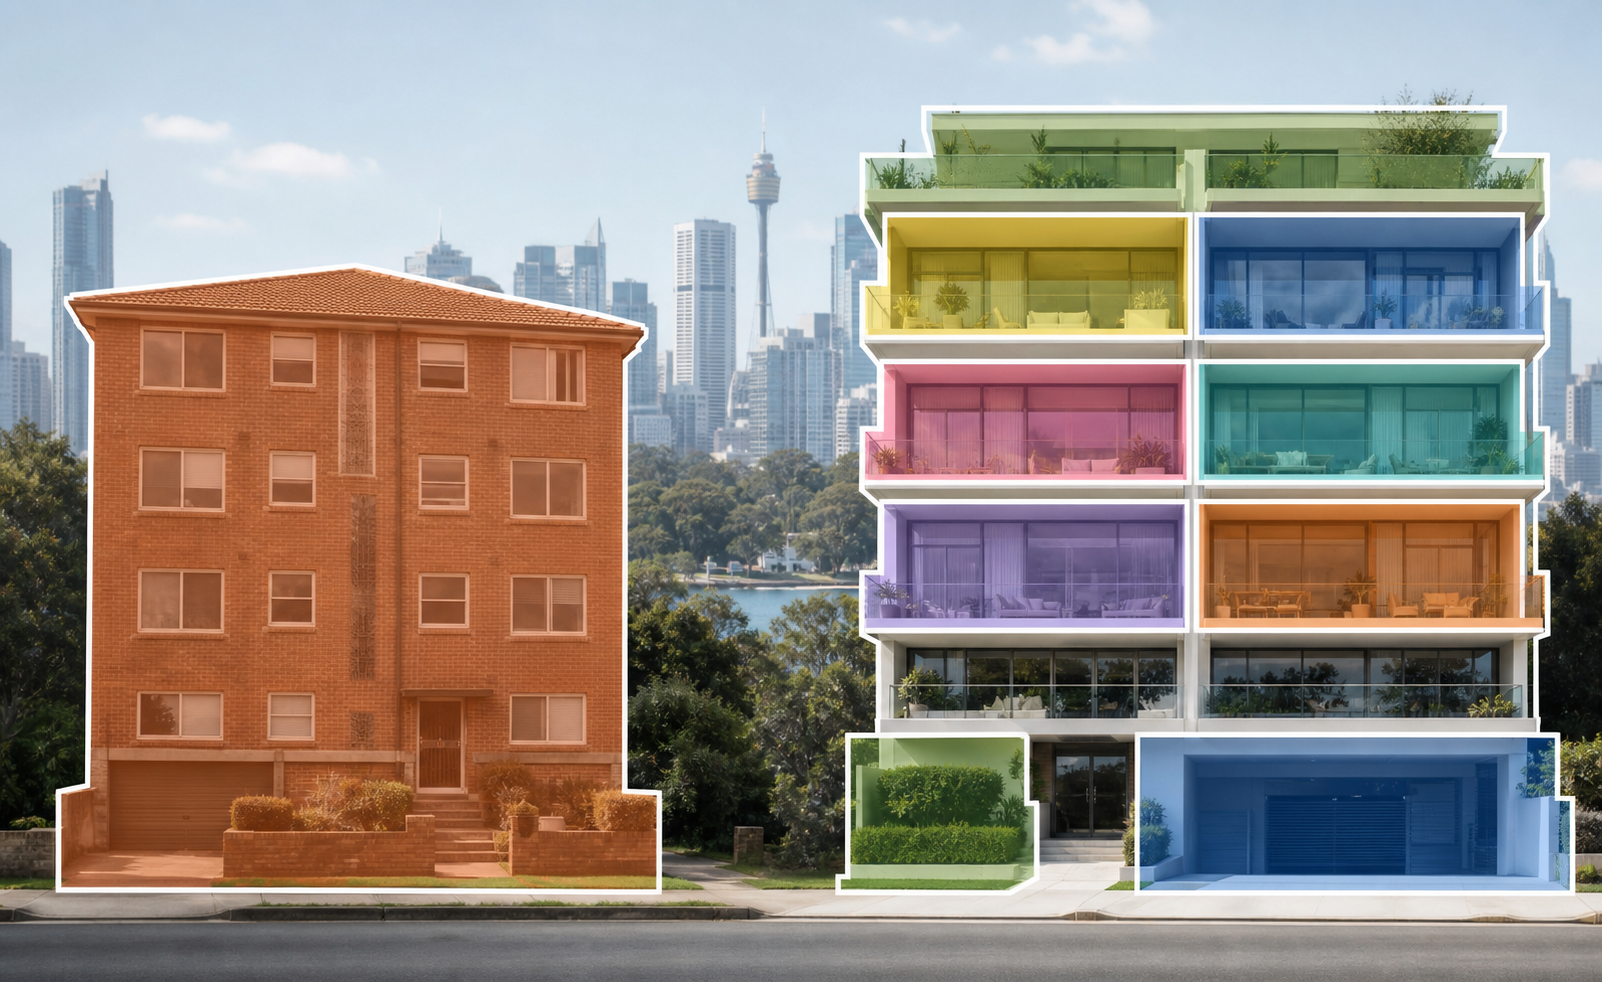
From a lender’s perspective, company title is less standard security. If they ever had to sell, the pool of buyers is smaller and the process is more complex. That’s why maximum LVRs are usually lower and credit teams look harder at the company constitution and share structure.
1.2 Why inner-south lenders already start cautious
Many lenders already treat parts of Green Square and Zetland cautiously due to:
- Oversupply risk – lots of similar units, many in the same price bracket.
- High investor ratios – more rental stock, more volatility in rents and values, as explored in Green Square Oversupply, Incentives and Investor Ratios: A Lending Playbook.
- High-density and mixed-use buildings – commercial components, short‑stay accommodation and complex facilities can all trigger tighter policy.
Layer company title or quirky strata rules over the top and you get a niche that only some lenders want to play in – and usually on more conservative terms.
2. How lenders look at company title units
2.1 Typical LVR limits and conditions (illustrative)
Every lender is different, but for company title loans in the inner south you’ll often see:
- Owner‑occupier, principal & interest: indicative max LVR 70–80%.
- Investor or interest‑only: indicative max LVR 60–75%.
- No LMI support: many lenders won’t use lenders mortgage insurance on company title, so once you’re above their internal LVR comfort line, it’s simply a no.
Compare that with a standard strata unit in a low‑risk suburb where 90–95% LVR may be possible (subject to policy, income and LMI).
| Scenario | Title type | Usage | Indicative max LVR* | Likely deposit needed* |
|---|---|---|---|---|
| Green Square apartment, standard | Strata | Owner‑occupied | Up to 90–95% | 5–10% + costs |
| Green Square apartment, high density | Strata | Investor | 80–90% | 10–20% + costs |
| Inner‑south older block | Company title | Owner‑occupied | 70–80% | 20–30% + costs |
| Inner‑south older block | Company title | Investor | 60–75% | 25–35% + costs |
*Illustrative only – not current policy or an offer. Real limits depend on lender, income, valuation and building.
2.2 Key documents banks will want
For company title, expect requests for:
- Company constitution and share schedule.
- Latest financial statements and ASIC extracts for the company.
- Minutes of recent meetings and evidence of building insurance.
- Details of any company‑level borrowing secured over the building.
The big fear for a bank is double‑gearing – a company with its own debt secured over the whole building, plus your personal loan secured over your shares. They need to be comfortable the company can operate and maintain the building without putting your security at risk.
2.3 A quick worked example: deposit and repayments
Say you’re eyeing a $850,000 company title unit near Green Square.
- Lender indicative max LVR for owner‑occupied P&I: 75%.
- Maximum loan on that figure: $637,500.
- That means you need $212,500 cash or equity plus stamp duty and costs (roughly another $40–50k in NSW at that level).
If the rate was, say, 6.2% p.a. P&I over 30 years (illustrative only), repayments would be around $3,910 per month. To stay clear of early mortgage stress, you’d want that stressed repayment (say at 9.2% with the APRA‑style 3% buffer) to sit well below the 35–40% of after‑tax income warning line discussed in Nine Debt Stress Red Flags For Inner‑South Borrowers To Act On.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is it harder to get a loan for company title than strata?▾
Can I still get 90% LVR on an inner-south apartment with quirks?▾
Do unusual strata by-laws stop a loan being approved?▾
Are company title loans more expensive than normal home loans?▾
Can I refinance a company title or quirky strata unit to release equity?▾
Should I avoid quirky properties altogether as an investor?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.