Article
Eastern Suburbs Postcodes That Hold Value Best When Prices Fall
A practical suburb‑by‑suburb look at which Sydney Eastern Suburbs postcodes have held up best in past downturns, why they’re more resilient, and how to use that insight this week whether you’re buying, refinancing or investing.
Key Takeaway
When Sydney prices fall, Eastern Suburbs postcodes with tight supply, strong amenities and diverse buyer demand tend to hold value best, typically losing 30–50% less than the wider market in past downturns. These include blue‑chip coastal and school-zone areas versus more volatile fringe investor pockets. By combining postcode-level performance, micro‑street checks and conservative loan structures, borrowers can pick more defensive locations and reduce the risk of forced sales or negative equity in future cycles.
Sydney’s Eastern Suburbs don’t move in one block. When the market turns down, some postcodes barely budge while others give back years of gains. In practice, the postcodes that hold value best combine scarce land, deep owner‑occupier demand, strong rental back‑up and realistic price expectations.
This guide looks at which Eastern Suburbs postcodes are typically more resilient in downturns, why that is, and how to apply it this week if you’re buying, refinancing or investing.
Fast answer: in past downturns, blue‑chip Eastern Suburbs postcodes with limited new supply and strong lifestyle or school drivers have usually fallen less and recovered faster than fringe, investor‑heavy pockets. Think established parts of Bondi, North Bondi, Bronte, Clovelly, Randwick and Woollahra versus high‑rise or busy‑road stock on the margins.
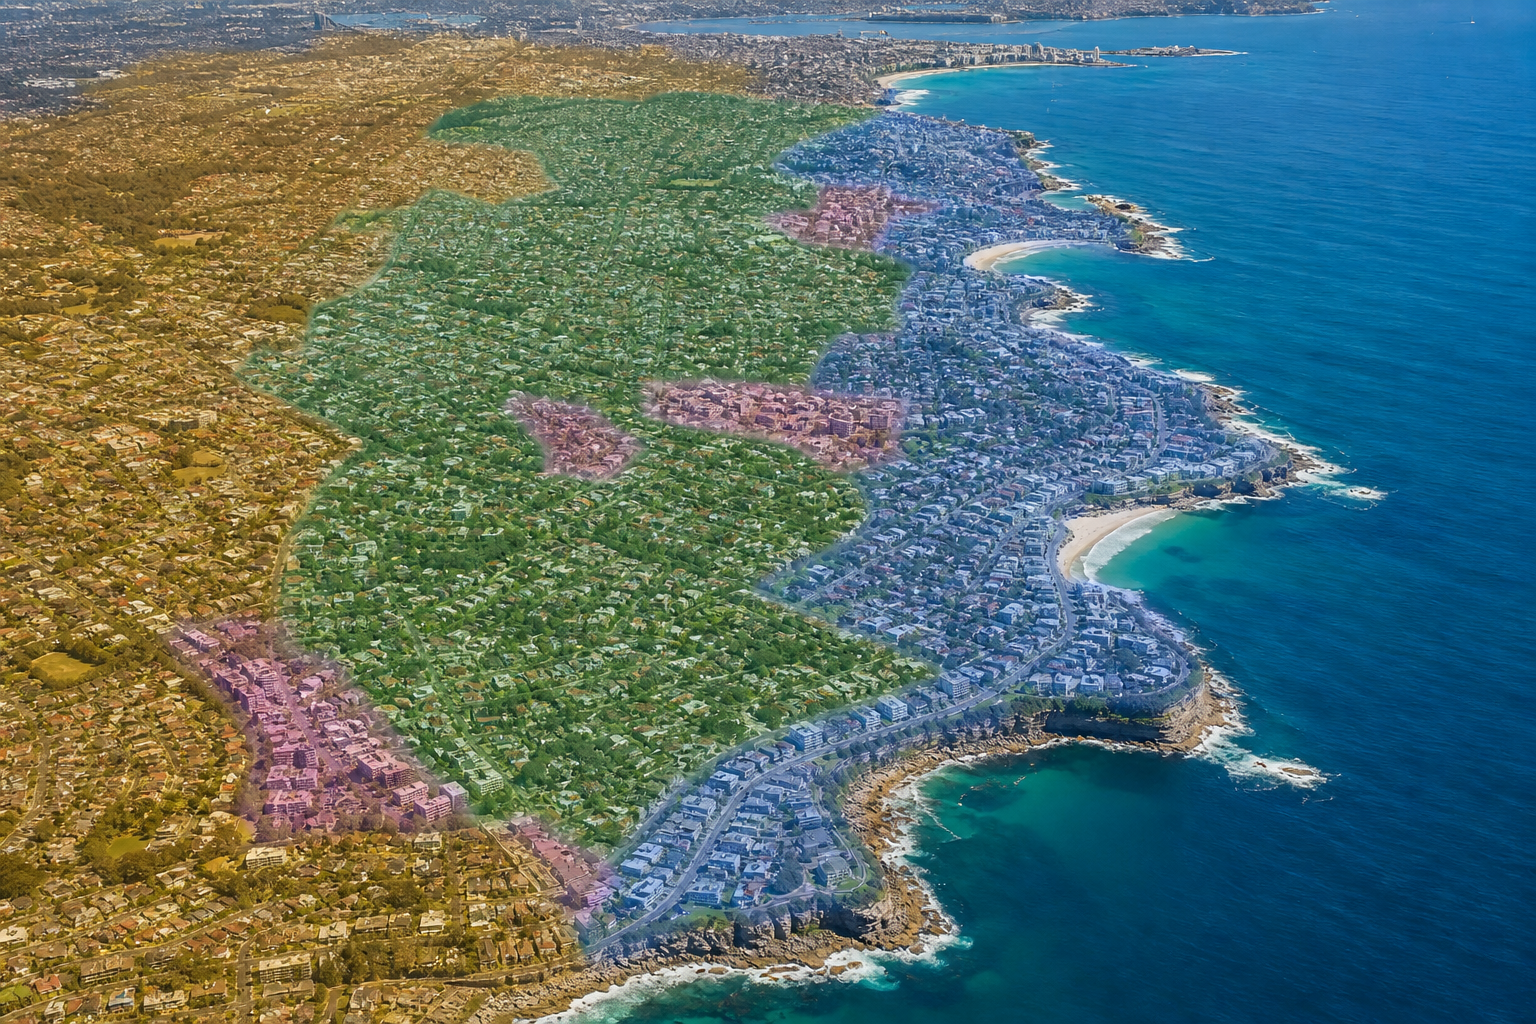
1. What “price resilience” in the Eastern Suburbs actually means
Before naming postcodes, it’s worth defining what “holds value” really looks like in a downturn.
1.1 Working definition
A resilient postcode typically shows three traits over a full cycle:
- Smaller price falls than the broader Sydney median in downturn years.
- Shorter time on market – properties still sell within a reasonable time without savage discounting.
- Quicker recovery – prices regain their previous peaks sooner than the city average.
In the 2022–23 rate‑rise cycle, for example, many Sydney regions saw peak‑to‑trough falls of 10–15%. In parts of the Eastern Suburbs, well‑located houses fell more like 5–8%, while some investor‑heavy unit pockets dropped 15–20% or more.
1.2 Why this matters for finance decisions
If you’re borrowing heavily, resilience matters because:
- Bank valuations follow the market down. A 10–15% postcode drop can kill refinance options or equity release plans.
- APRA’s 3% buffer bites harder. When rates are high and serviceability tests are tight, a softer valuation can be the difference between approval and rejection.
- Concentration risk rises. If most of your wealth is in one or two Eastern Suburbs properties, a sharp local fall can lock you in or force sales at the worst possible time (see the concentration risk framework in /insights/diversifying-wealth-when-most-net-worth-family-home).
Resilient postcodes don’t remove risk, but they can reduce the depth and duration of the pain.
2. The four big drivers of Eastern Suburbs price resilience
The specific postcodes change at the edges, but the drivers of resilience are consistent.
2.1 Scarce land and tight planning controls
Across Sydney, the ABS “Total Value of Dwellings” data shows the same pattern: suburbs with limited new supply tend to outperform over the long run and fall less in downturns.
In the Eastern Suburbs, resilience is strongest where:
- There’s minimal high‑rise capacity or heritage/height limits.
- Blocks are small but land is irreplaceable – near beaches, parks, harbour or ridge lines.
- Owners are sticky – fewer speculative developers, more long‑term families.
2.2 Deep owner‑occupier demand (not just investors)
Postcodes dominated by investors and short‑term rentals tend to be more volatile. When confidence falls, investors pull back first.
More resilient postcodes usually have:
- Strong family and professional owner‑occupier presence.
- Good public and private school catchments.
- Easy commute options and local employment.
This aligns with the lender view in /insights/over-hyped-vs-under-the-radar-eastern-suburbs-lender-view: banks often quietly favour “boring” owner‑occupier streets over shinier investor corridors.
2.3 Lifestyle anchors that don’t turn off in a recession
Some lifestyle features hold up even when budgets tighten:
- Surf beaches and coastal walks.
- Thick café/retail strips that stay busy.
- Hospital and university precincts.
Others are more discretionary (high‑end luxury retail, purely prestige views with limited utility) and can see sharper discounting when bonus‑driven incomes fall.
The prestige vs fringe dynamic is explored further in /insights/prestige-vs-fringe-eastern-suburbs-economic-shocks.
2.4 Rental demand as a safety net
When the RBA lifts the cash rate (it’s back at 4.35% after the 2026 energy shock, per Ian Harper’s June 2026 speech), some owners who’d like to sell instead choose to rent their property out while they wait for better conditions.
Postcodes with:
- Tight rental vacancy (near hospitals, universities, transport, beaches), and
- A range of price points
provide a safety net – owners can often cover a decent chunk of repayments via rent, which reduces forced sales and caps price falls.
3. Eastern Suburbs postcode patterns in recent downturns
We’ll stay high‑level here – different data providers cut the numbers in different ways – but the pattern across downturns is clear.
3.1 Typical “defensive” Eastern Suburbs postcode traits
These postcodes generally show shallower falls and faster recoveries:
- Bondi / North Bondi – iconic beach, limited land, owner‑occupier and investor mix.
- Bronte / Clovelly – family‑heavy, small catchments, scarce supply.
- Randwick / Coogee – hospitals, UNSW, beaches, strong rental base.
- Waverley / Queens Park – village feel, Centennial Park access, family‑oriented.
- Woollahra / Paddington – terrace and prestige stock, very limited new supply.
Within those postcodes, houses on quiet, well‑positioned streets tend to be the most defensive. Generic, older units in walk‑up or small blocks close to amenities can also be surprisingly resilient due to their price point and limited competition.
3.2 More volatile Eastern Suburbs postcode pockets
Postcodes that have seen bigger swings in past cycles often include:
- Fringe or transport‑light pockets further from trains, hospitals or beaches.
- High‑rise corridors with ongoing supply or many near‑identical apartments.
- Investor‑heavy buildings with lots of short‑term rentals.
These areas can boom hard when credit is cheap, but they can give back 15–20% or more when interest rates jump and sentiment turns.
3.3 Houses vs units in a downturn
Across Sydney, downturns often hit houses first in dollar terms, but:
- Quality units in scarce locations can hold value well – they remain the entry point for young professionals.
- Investor stock with high body corporate costs, poor natural light or noisy positions tends to get hit harder.
The valuation case studies in /insights/why-two-eastern-suburbs-properties-valued-so-differently show how two similar‑looking properties can diverge sharply once valuers consider micro‑location and recent comparable sales.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do Eastern Suburbs house prices always fall less than the rest of Sydney?▾
Are beachside Eastern Suburbs postcodes safer than inland ones in a downturn?▾
How much could my Eastern Suburbs home drop in a recession?▾
Are prestige Eastern Suburbs suburbs always the most resilient?▾
Which is safer in a downturn: an Eastern Suburbs house or unit?▾
How should I factor postcode risk into my borrowing limit?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.