Article
Major banks vs specialist strata lenders: choosing for your building
Major banks suit simple, strong strata schemes, while specialist strata lenders fit buildings with defects, big upgrades or complexity. Learn which way your committee should lean this week.
Key Takeaway
Major banks suit low‑risk, well‑run strata schemes seeking lower rates, while specialist strata lenders better fit buildings with defects, complex works, arrears or urgent timelines. Rate differences of 0.75–1.50 percentage points are common, but flexible terms and faster approvals can outweigh the cost. Committees should compare total per‑lot levy impact, documentation readiness and risk profile, then select a lender type that aligns with their building condition and owners’ cashflow.
Watch the short answer
Can you buy a property before your tax return is done?
While you weigh up lenders for your building, this video covers how buying can work if your latest tax return is not yet lodged.
Read the transcript
Think you can't buy a property this year because your accountant hasn't finalised your 2026 tax returns? Think again. If you are a freelancer, a contractor, or a growing business, that means months of lost opportunity. We use alternative documentation pathways that completely bypass the ATO delay. We assess your true borrowing capacity using the last 6 months of your business bank deposits, getting you approved while your competitors are still waiting on paperwork. Stop waiting on tax portals to dictate your property goals. Message me 'ALTDOC', to fast-track your FY27 approval.
General information only, not personal advice. Your situation is assessed before any recommendation.
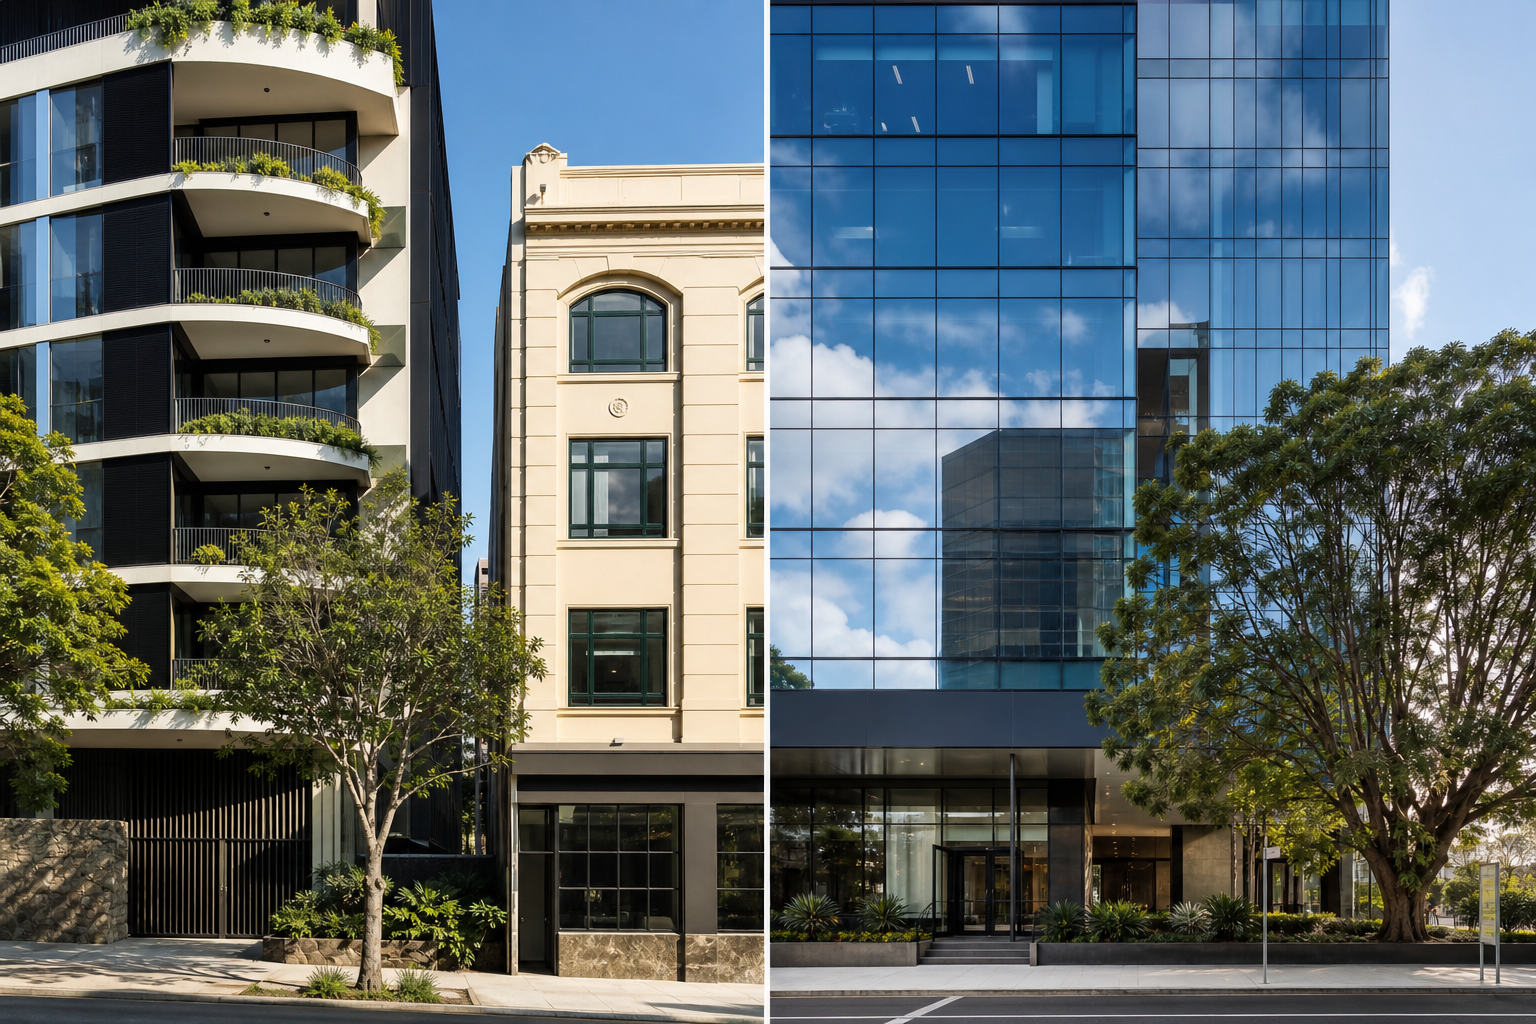
For most strata buildings, major banks suit simple, low‑risk schemes chasing the sharpest rate, while specialist strata lenders suit buildings with defects, complex works or patchy finances that need flexibility and speed. The right choice comes down to your building’s risk profile, how urgent the works are, and what per‑lot levy impact owners can actually live with.
In other words: if your scheme is clean and boring, start with the banks. If it’s messy, time‑sensitive or politically fraught, assume a specialist lender and only drop back to a bank if the numbers still stack up.
1. Major banks vs specialist strata lenders: what’s the real difference?
How each lender type looks at your building
Strata loans are assessed on the building and scheme health, not your personal incomes. If you’re new to this, start with Strata Loans Explained: Structures, Rules And What Lenders Really Want.
Typical differences you’ll see in the market (figures indicative only, not live offers):
| Feature / Issue | Major Bank (typical) | Specialist Strata Lender (typical) |
|---|---|---|
| Interest margin vs home loan | +1.00% to +2.00% p.a. | +1.75% to +3.00% p.a. |
| Loan term | 5–10 years | 7–15 years (sometimes 20) |
| Appetite for known defects / cladding | Low | Moderate to high (priced for risk) |
| Appetite for higher arrears | Very low (often <5% lots in arrears) | More tolerant with plan to fix |
| Documentation standard | Bank‑grade, strict policy | More tailored, often strata‑specific |
| Speed to decision | 4–10+ weeks | 1–4 weeks in many cases |
| Flexibility on structure & covenants | Limited; standardised | Higher; bespoke covenants common |
Major banks compete on price and policy. Specialist strata lenders compete on flexibility, structure and speed.
Worked example: same loan, two very different levy paths
Assume a $1,000,000 strata building loan, interest‑only for 3 years then principal and interest (P&I) over 7 years (10‑year term), comparing an indicative bank and specialist lender.
- Major bank rate: 7.00% p.a.
- Specialist lender rate: 8.25% p.a.
Year 1 interest‑only repayments:
- Bank: $1,000,000 × 7.00% ÷ 12 ≈ $5,833/month
- Specialist: $1,000,000 × 8.25% ÷ 12 ≈ $6,875/month
For a 40‑lot scheme on unit entitlements, that’s roughly:
- Bank: about $146 per lot per month on average
- Specialist: about $172 per lot per month on average
That $26 per‑lot difference can matter, but if the bank won’t approve you (defects or arrears), the cheaper option is theoretical.
2. When a major bank is the better fit
Building and scheme profile that banks like
A major bank tends to suit your building when:
- The building is structurally sound, with no unresolved serious defects.
- Fire safety and cladding issues (if any) are already rectified or fully funded.
- Arrears are low and falling, and financials are clean.
- The works are important but not emergency‑level (you can live with a longer approval process).
Banks also prefer straightforward residential schemes. Mixed‑use or mostly commercial buildings are more likely to be pushed towards specialist or commercial banking channels; see Commercial strata finance rules: how they differ from residential for those nuances.
Pros and cons of a major bank for strata loans
Pros
- Lower interest margins if you qualify.
- Strong brand comfort for nervous owners.
- Often easier to refinance later to another bank if performance is good.
Cons
- Narrow credit appetite – one issue (defects, arrears, weak records) can derail the application.
- Slower decision cycles and more layers of approval.
- Less flexible on bespoke levy structures or covenant tweaks.
If you’re considering a bank and will also need to refinance personal home or investment loans, read how banks view schemes with strata loans at Refinancing An Investment Property When Your Strata Has A Loan.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 3 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Which is better for a strata loan, a major bank or a specialist lender?▾
Can we refinance from a specialist strata lender to a major bank later?▾
Do individual owners have to apply for the strata loan?▾
Are specialist strata lenders more expensive than major banks?▾
How do we decide if our building should approach banks or specialist lenders?▾
Speak with a specialist advisor
Confidential consultation, bespoke advice for your situation.